You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:

The first veto of Joe Biden’s presidency, in March 2023, came on a bill that would have overturned a Department of Labor rule allowing retirement funds to consider environment, social, and governance factors — commonly known as ESG — when making investment decisions. At the time, it seemed like a good representation of where the issue stood: Though there was a conservative backlash against ESG investing, much of which revolves around whether companies are incorporating climate risks into their planning, the backlash was more bark than bite. ESG not only seemed here to stay, it was gaining in prominence as more investors and Wall Street firms realized they could no longer ignore the effects of climate change on the economic prospects of the companies they were funding.
Less than two years later, the picture looks rather different — at least politically. There is still over $3 trillion invested in ESG funds worldwide, the vast majority of it in Europe. But here in the U.S., the backlash has only grown stronger, and with Donald Trump’s election, there has been a Wall Street stampede away from public commitments to assess climate risk as a key component of investment decisions. There’s no way to know how much long-term effect this change will have on emissions, but the reversal in the public stance of the financial sector has been swift and intense.
Let’s begin with the banks. In the space of a month, the six largest banks in the United States — Goldman Sachs, Bank of America, Wells Fargo, Citi, Morgan Stanley, and JPMorgan — all pulled out of the Net-Zero Banking Alliance, an international United Nations-sponsored group under which member banks commit to pursuing net-zero carbon emissions from their lending and investments by 2050.
While Trump’s election may have been the tipping point, it comes after an organized campaign waged at the state level over the past couple of years, as Republican attorneys general have pressured and threatened the finance industry into abandoning its efforts to contribute to the mitigation of climate change.
In the spring of 2023, 23 Republican AGs threatened the Net-Zero Insurance Alliance (like the NZBA, a UN-sponsored group) with antitrust action, saying it was pursuing “an activist climate agenda.” Companies began leaving, and a year later, the group disbanded. The effort against the banking alliance followed a similar pattern: Threats of legal action from Republican attorneys general, followed by a pullback from the banks.
Like insurance companies and banks, investment firms are clearly feeling the pressure. BlackRock, the largest asset manager in the world, recently pulled out of the Net-Zero Asset Managers Initiative, a group similar to those for insurers and banks, citing “legal inquiries from various public officials.” That included a lawsuit filed by Texas and 10 other Republican states, alleging that BlackRock and other firms were unfairly harming the fossil fuel industry with their investment decisions. This week, the NZAMI released a statement saying that in response to “different regulatory and client expectations,” it is launching an internal review, and meanwhile “suspending activities to track signatory implementation and reporting” of climate goals.
Meanwhile, Republicans in Congress have been issuing reports and press releases condemning the “woke ESG cartel,” which they claim consists of “left-wing activists and major financial institutions that collude to impose radical environmental, social, and governance goals on American companies.” After the election, those Republicans now control both houses of Congress, as well as the White House.
So it’s a good bet that the pressure on the finance industry from Washington will only increase, especially with a new administration that combines dismissal of climate change with an eagerness to bring corporations to heel. In many cases, key administration positions will be staffed by former employees of the very fossil fuel companies that oppose real climate action, or at least by their allies. One vivid example: Lee Zeldin, Trump’s nominee to lead the Environmental Protection Agency, revealed in disclosure forms that he was paid tens of thousands of dollars to pen op-eds attacking ESG investing. His forms list only the PR firms that paid him, not the clients on whose behalf they did so.
These pullbacks from climate pledges are clearly motivated by fear, and may even be taken with regret by some of the CEOs making the decisions. If that is the case, however, it is not a universal sentiment. The Financial Times reports that “Some Wall Streeters also feel able to embrace making money openly, without nodding to any broader social goals. ‘Most of us don’t have to kiss ass because, like Trump, we love America and capitalism,’ one said.”
Here’s the kicker: These alliances that are now wavering began with few requirements in order to bring in as many participants as possible; only later would companies have to meet more reporting and emissions goals. But “as accountability mechanisms started to come into play, at the same time we started to see the conservative backlash against it,” Tensie Whelan, founding director of the NYU Stern Center for Sustainable Business, told me. Now, “they’re all running scared.”
Though some critics charge that ESG is mostly about greenwashing, many financial actors — banks, asset managers, investors — have embraced greener investing because it is both good for the planet and good for business. If a company is exposed to climate risk but fails to account for it in its long-term strategy, that company is probably a bad investment. Investments incorporating sustainability considerations tend to perform as well or better than ordinary investment vehicles — the S&P 500 ESG Index, for instance, has outperformed the standard S&P 500. And a study by HIP Investor showed that public pension funds in blue states that incorporated ESG factors have generated higher returns than red-state funds that eschewed them.
“I would hope and assume that at some point there will be some class-action suits” against states that have turned away from ESG investing, and in so doing cost taxpayers money, Whelan said. In 2024, 17 Republican-run states passed bills restricting ESG investments with state funds, while eight Democratic states passed pro-ESG bills.
When banks or investment firms abandon climate alliances or pull back from climate goals in other ways, they nearly always put out statements reiterating their commitment to reducing emissions. While those might be sincere, the most important message is that the threats and pressure are effective. And that’s what has become so clear: Conservatives are energized and emboldened to roll back corporate efforts to address climate change, and are using every tool they have — legislation, litigation, threats, public pressure campaigns — to destroy those initiatives.
Nevertheless, there is plenty of room for pressure from the other side. Whelan notes that blue states “are very adamant about having key sustainability criteria” in their investments, and as younger generations accumulate more wealth, they are more likely to demand sustainability where they put their money. As for Wall Street responding to political pressure by backing away from its climate goals, “this retrenchment is unfortunate,” Whelan told me, but “I do think it’s temporary, and I think they know that. Because they’re not stupid.”
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
The bill would let states and utilities discriminate against data centers and crypto miners, requiring them to pay higher rates to cover the full cost of any system upgrades.
Call it the data center double tap.
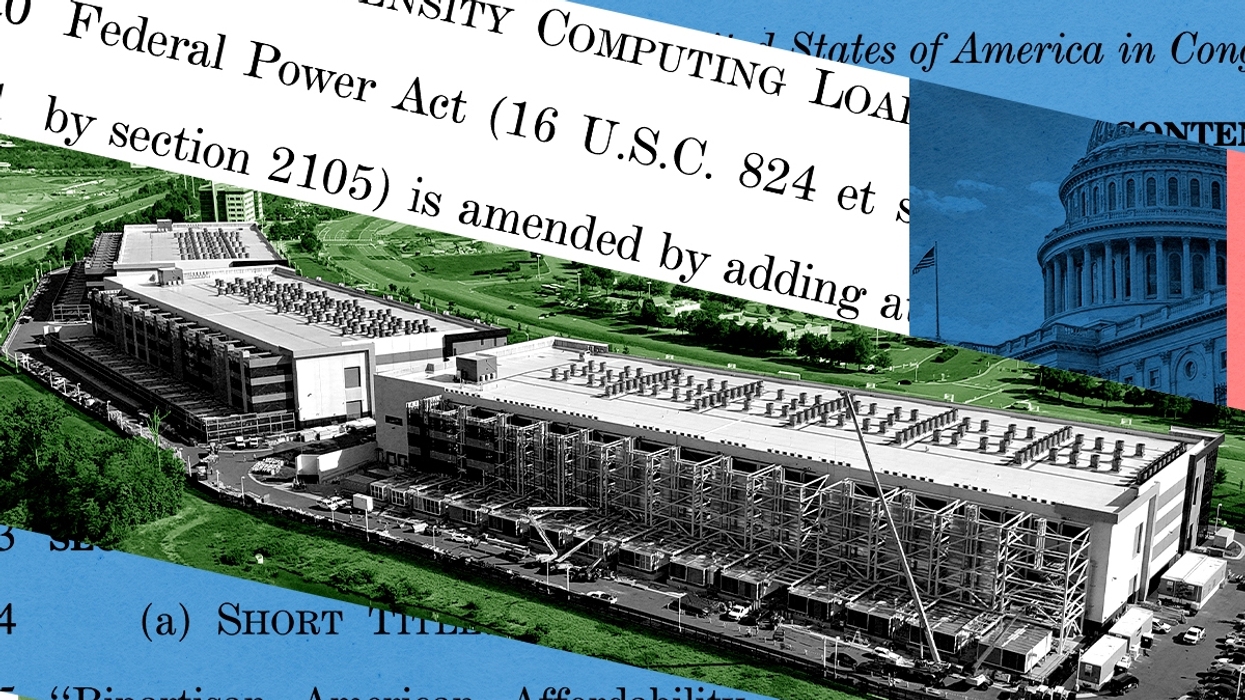
A wonky set of provisions in the Senate’s bipartisan permitting deal would rewrite federal electricity law to allow states and utilities to discriminate against artificial intelligence data centers and crypto miners for the first time.
The proposal would force AI data centers to pay for any new transmission infrastructure required to serve them — while still paying full freight to use the rest of the power grid. It could even let states require the facilities to subsidize other customers’ power rates.
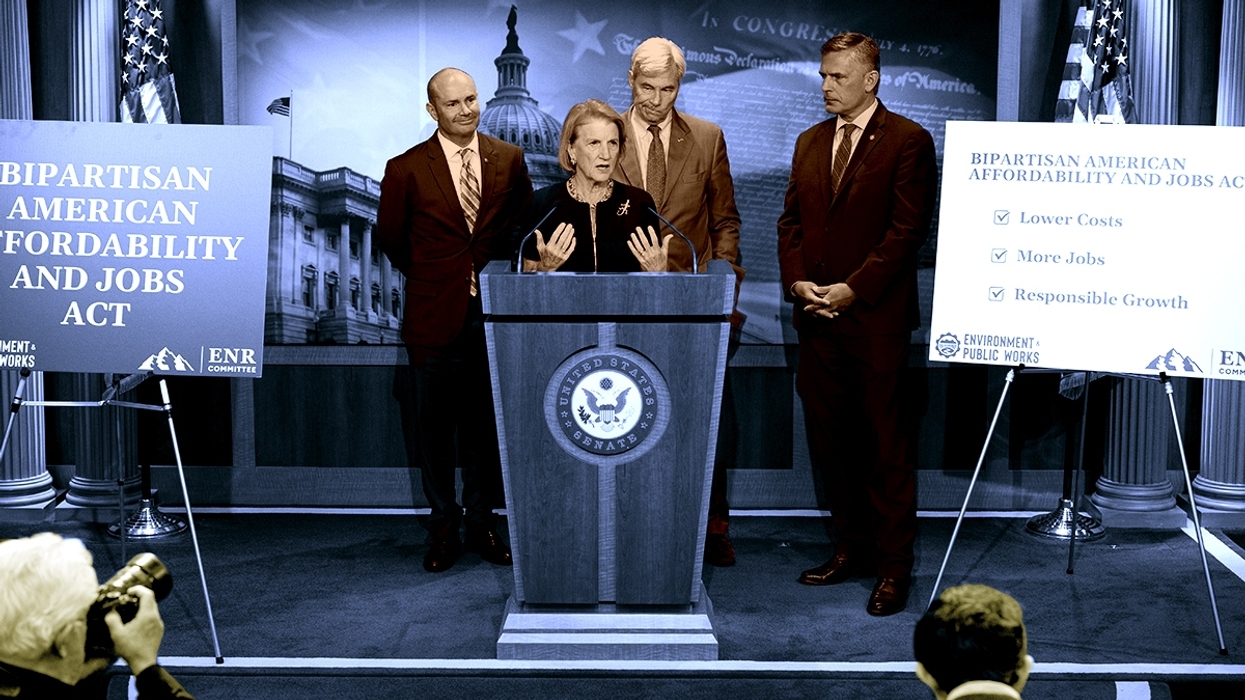
Senator Martin Heinrich, the ranking Democrat on the Senate energy committee, mentioned the provisions during a press event announcing the deal on Wednesday, but they have so far attracted less attention than the bill’s other measures.
If enacted, the bill will “mean that we actually require big load centers — whether that’s a factory or a data center — to not pass those costs on to the American consumer by statute, not suggestion,” he said.
The bill arguably goes further than that summary. It creates new carve-outs in federal law that disadvantage data centers and crypto miners specifically, allowing states to discriminate against them as compared to other large-scale customers. It also protects electricity customers from the future risk of data centers failing to pay their bills.
The proposal comes at an auspicious time. Utilities are already gearing up to spend tens of billions of dollars building new transmission lines and power infrastructure to meet energy demand from AI data centers. The law would seek to ensure that tech companies and data center developers bear the cost of those upgrades.
Since the data center boom got underway, just about everyone involved — tech companies, utilities, environmentalists, and even President Trump — has agreed on one thing: Normal Americans should not pay for data centers’ burden on the power system.
These expenses can be significant, especially for the transmission system. Because a single computing facility can guzzle gigawatts of energy at once, compressing a city’s worth of power demand into just a few acres, it often requires the construction of specialized new infrastructure, or it risks causing blackouts and brownouts for nearby customers.
In 2024, utility customers in the country’s largest power market paid $4.3 billion for transmission upgrades to supply data centers, according to a Union of Concerned Scientists report.
Trump enshrined guarantees against these payments in his Ratepayer Protection Pledge in March. That document vowed that data center companies must pay for all of the electricity used to run their facilities, any new power plants required to generate that electricity, and any “new power delivery infrastructure upgrades.”
There’s just one issue: Under federal law, the last part of that pledge is nearly impossible.
Since the early 1990s, federal law has prohibited utilities from charging customers for both the cost of using specific transmission infrastructure and the cost of using the rest of the power grid.
The origins of that ban go back to a 1992 case where a power plant in one utility’s service area wanted to sell electricity to a neighboring utility. The local utility wanted to charge it the “normal” cost of using its power grid, plus a special fee to cover the cost of crowding its own customers off the necessary transmission lines.
The Federal Energy Regulatory Commission ruled that was illegal. Instead, it said, utilities could make a customer pay for the “incremental” cost of using specific transmission lines, such as those built to service their facility. Or they could charge for the “embedded” costs of the existing power grid.
Utilities could not charge customers for both “incremental and embedded” costs, it said; instead, utilities had to choose the higher of the two. FERC formalized the policy in 1994.
Electricity law has changed significantly since then, and those FERC rules don’t apply to power plants, Ari Peskoe, the director of the Electricity Law Initiative at Harvard Law School, told me.
But the ban still applies to electricity customers — even very big ones, like data centers. Peskoe wrote a Utility Dive article in April credited with first identifying the clash between the FERC rules, the data center boom, and the White House’s pledge.
The rules have serious implications for energy affordability. In practice, virtually every utility today is charging data centers for the “embedded” cost of using the existing grid, he told me on Thursday. Utilities want to avoid fights with each data center about which transmission upgrade costs are “incremental” and which are “embedded.”
Instead, utilities are forcing all of their customers to pay for the cost of transmission upgrades to serve those data centers. That means data centers will likely drive up normal Americans’ electricity rates for the next decade or so, even if officials, lawmakers, and tech companies say they don’t want that to happen.
The Senate proposal would change this, instructing FERC to require utilities to charge data centers for the cost of any new grid upgrades required to serve them as well as the costs of the underlying grid. In other words, it would mandate data centers pay for embedded and incremental costs.
These types of customers “should incur the full cost of the transmission service they require,” the bill says. This change would apply narrowly to data centers, crypto mining operations, and any facilities doing AI training — essentially discriminating against data centers under federal law.
The bill would also write a new section into the Federal Power Act that would require data centers, crypto miners, and other computing facilities larger than 20 megawatts to cover the entire cost of their service. The bill says utilities can’t spread the cost of providing energy or building infrastructure for data centers to any other customer.
If data centers leave a contract early, they will still have to pay for the full cost of those grid upgrades. And before a utility can upgrade any of their infrastructure to serve a data center, it must get “financial assurances or contributions” from that facility to cover the costs of doing so.
The bill also allows states to go further than these provisions — they can discriminate against data centers, set special rates by which data centers subsidize other customers’ power rates, and auction off the right to connect to the power grid.
Since I’ve learned about these provisions, I’ve struggled with what to call them. They aren’t quite a new tax on data centers, because the government does not collect the revenue. But many of them have tax-like qualities: They impose significant new costs on future data centers that would then be used to pay for upgrades to the broader power grid, and they protect the power system from the downside risks of a data center bust. They also allow for cross-subsidy of the power system, where payments from data centers can reduce everyone else’s electricity rates.
The law would bring federal rules governing electricity somewhat closer to those that already exist for natural gas, though it goes much further than those rules, too. Since 1999, FERC has generally assumed new interstate natural gas pipelines should be entirely paid for in an “incremental” way, meaning that new shippers or customers are supposed to bear the costs of service expansion alone. Having customers pay for embedded and incremental pricing remains illegal under federal natural gas law.
When combined with other provisions in the bill — such as those that make building new interstate transmission lines much easier — the new policies could help spur a large-scale buildout of electricity infrastructure paid for by the data center boom.
But even setting that more ambitious potential aside, the law would cover existing holes in the laws protecting Americans from paying for the data center boom.“I think it’s an improvement on the status quo,” Peskoe told me. “I think it’s consistent with data centers paying their ‘fair share,’ and consistent with the text of the Ratepayer Protection Pledge.”
And it is also “consistent,” he added, “with how normal people might think about these issues.”
Spoiler: They’re mostly winners.
There’s seemingly plenty to celebrate in the Senate’s new 400-plus-page permitting reform bill, the Bipartisan American Affordability and Jobs Act, or BAAJA. The headline benefit — and the one drawing the most praise from energy hawks — is that expediting the buildout of energy infrastructure and transmission lines ought to bring tons more zero-carbon energy online. No doubt it will speed up fossil fuel projects as well, but modeling shows that renewables like wind and solar are disproportionately held back by the notoriously contentious and slow planning and permitting processes the bill seeks to overhaul.
Old-school renewables aren’t the only technologies that stand to benefit from BAAJA, however.
Here are four more climate tech sectors — and the startups working in them — that are probably pretty happy to see that, after four years of debate and countless failed negotiations, a permitting bill finally appears poised to become law.
No surprises here: It’s well known at this point that geothermal is a beloved bipartisan technology, and BAAJA affirms the government’s commitment to bringing more of this clean, firm energy source online as soon as possible.
The bill would categorically exclude drilling exploratory geothermal test wells from review under the National Environmental Policy Act, and exempt lower-impact activities such as mapping and surface surveying from NEPA entirely. It would also require the Interior Department to hold annual geothermal lease sales, and drop the federal drilling permit requirement for geothermal exploration on non-federal land, so long as the government owns less than half of the underground resource.
Next-generation geothermal companies such as Fervo Energy, Sage Geosystems, Mazama Energy, and Quaise Energy stand to benefit, of course, as finding viable sites to trial their tech and build early commercial projects requires plenty of mapping and exploratory drilling. This cohort aims to expand geothermal beyond the relatively small number of geographies with the ideal combination of high heat at shallow depths, naturally occurring subsurface water or steam, and permeable rock that conventional geothermal power plants rely on. But a company like Zanskar, which uses AI to identify overlooked conventional geothermal resources, stands to benefit, too — its approach also depends on scouting and drilling across many sites.
BAAJA is intent on advancing tech that can squeeze more capacity out of the transmission lines we already have. The bill requires utilities to conduct recurring evaluations on technologies that could increase the capacity of existing transmission infrastructure, such as higher-capacity replacement wires or monitoring systems that determine when the lines can safely carry more power. Investor-owned utilities have historically had little incentive to adopt any of this, since they earn money by building new infrastructure, not by making existing infrastructure more efficient. Now, that math could change. If the evaluations find this tech will provide net benefits, utilities are required to deploy it within a certain timeframe, lest the Federal Energy Regulatory Commission impose penalties.
That’s welcome news for dynamic line rating startups such as LineVision and Heimdall Power, which use sensors to monitor power lines in real time to determine when they’re capable of carrying more electricity than their fixed ratings allow. Companies building higher-capacity lines are also likely to see more business. This includes TS Conductor, which makes a carbon-fiber core wire that it says can double or even triple a line’s capacity, and VEIR, which originally aimed to build “high-temperature superconducting transmission lines,” though it recently pivoted to data center power solutions. Startups like NewGrid, whose software finds ways to avoid congested lines and route more electricity through the existing grid, could benefit, too.
The bill also opens doors for virtual power plants, networks of distributed energy resources such as rooftop solar panels, batteries, smart thermostats, and electric vehicle chargers that operate like a single power plant, responding to spikes in energy demand or shifting load to off-peak hours. Like grid-enhancing technologies, VPPs can reduce the need for new poles, wires, and power plants by making better use of the energy resources already installed in homes and businesses. And they also include an added perk: They pay these customers for adjusting their energy use when the grid needs it.
While FERC ordered grid operators to open their markets to these aggregators in 2020, implementation has dragged. BAAJA would speed things up by requiring operators to allow VPPs into their markets within 18 months of the bill’s passage and setting a low, 100-kilowatt threshold for device networks to be considered VPP-eligible. It would also require utilities to connect VPPs quickly and allow them to export power, while barring utilities from requiring aggregators to install the utilities’ own equipment like separate submeters and switches, which adds delays and added costs for hardware and installation. Separately, the bill directs the Department of Energy to fund efforts to streamline local government permitting and inspections for distributed energy resources like rooftop solar and batteries.
This is a boon for aggregators including Voltus, Renew Home, and David Energy, which sell grid services like demand response, capacity, and frequency regulation into utility programs and wholesale markets. Under this bill, they could do so more easily thanks to guaranteed market access and lower entry thresholds.
VPP software platforms like Leap could benefit, too. Leap helps manufacturers of devices such as smart thermostats and EV chargers enroll customers in VPP programs, so fewer utility equipment requirements and what will presumably be a much bigger addressable market would help. Home battery companies such as Lunar Energy and Base Power, which aggregate their residential batteries into VPPs, and smart panel-maker Span, which coordinates home appliances to respond to grid needs, could see similar benefits.
Hard rock mining is also among the bill’s clear winners. It clarifies that miners can use as much federal land as is “reasonably necessary” to store waste rock and tailings, and opens additional federal land for hard-rock mining leases. It also requires lawsuits challenging mining approvals to be filed within 150 days. Broader changes to NEPA, the National Historic Preservation Act, and the Clean Water Act will also accelerate the mining approval process.
This will undoubtedly be controversial for many climate advocates; while the energy transition demands more critical minerals, mining itself is a dirty endeavor. Yet there are a number of climate tech-adjacent companies focused on extracting, refining, and processing materials like lithium, nickel, cobalt and copper that stand to benefit.
One of the buzziest startups trying to develop new critical minerals mines, AI-driven exploration and development company KoBold Metals, is mainly working abroad right now. But a more favorable domestic environment could prove an enticement to invest more at home. Mariana Minerals, a software-driven developer working to bring mines online faster and cheaper, definitely stands to benefit given its current domestic focus. So could startups like Jetti and Endolith, which are developing technology to extract more copper from low-grade ores. Both work with existing mines, so could stand to profit from a domestic mining boom.
Of course not everyone will win here. For the horde of climate-tech adjacent startups trying to jump on the data center bandwagon — perhaps those working on chip cooling or capturing and recycling the waste heat from data center servers — maybe the added costs this bill imposes on data centers will reduce demand for their services just a bit. But I wouldn’t count on that. The bill certainly won’t stop the buildout so much as change who pays for some of the infrastructure required to serve it, shifting the cost of new power lines and grid upgrades from ratepayers onto the tech giants and developers themselves.
Then there are the myriad software startups such as Nira Energy, Paces, and Piq Energy that help energy developers navigate the grid interconnection process. Since the bill requires regional grids to streamline their queues, this could reduce demand for their services. But developers will still need to know where the grid has room and where projects pencil out, and utilities and grid operators will have to rebuild their interconnection processes, a transition that could generate demand for software of this sort.
There’s also just an array of climate industries that go largely unaddressed. While the Inflation Reduction Act offered incentives for practically every decarbonization technology under the sun, this bill is far more targeted, leaving sectors such as EV manufacturing, industrial decarbonization products like clean cement and steel, agricultural technologies, and methane abatement relatively untouched.
Carbon capture and removal projects, EV charging, and hydrogen get only minor nods: protection from administrative delays for carbon management projects and DOE funding to help local governments expedite permitting for EV chargers and hydrogen refueling stations. All of these industries could still benefit when building manufacturing plants or other facilities that need federal sign offs. But they could also lose ground if speedier approvals for fossil fuel infrastructure make cleaner alternatives less competitive.
On Korean reactors, California plug-in solar, and Europe’s green steel champion
Current conditions: Floodwaters from the remnants of Hurricane Polo breached a 20-foot dam in southern New Mexico, forcing evacuations • The Pacific’s active hurricane season continues as Hurricane Rachel threatens dangerous rip tides off Baja California • Further north in the Pacific, Tropical Storm Choi-wan is headed toward the Northern Mariana Islands.
It’s 417 pages — or, for those of you who think in such terms, roughly two-and-a-three-quarters the length of a standard environmental impact statement. And it the landed yesterday with much fanfare. The Senate’s grand compromise on permitting reform, dubbed the Bipartisan American Affordability and Jobs Act, or BAAJA, is packed with sweeping changes that promise to upend how data centers are built, whether transmission lines get constructed at all, and speed up deployments of all kinds of energy infrastructure. My colleagues — there are five bylines on this sucker, if you have any doubt about how seriously Heatmap is taking this — have a dense and comprehensive explainer here.
Whether the bill becomes law is another question. Already, House Democrats are casting doubt over whether they will vote for the legislation during the lame-duck session after Republicans likely lose control of at least the lower chamber of Congress in November’s midterm elections. “Most Democrats will want to see how things go on Nov. 3 and then do a reality check,” Representative Jared Huffman, a California Democrat, told Bloomberg reporter Ari Natter. “If we’re on our way to a majority in one or both Houses, it makes no sense to fold our hand when we could wait a few months and have a much better deal early next year.” Any hope of brokering a deal to vote on the bill before the election seems unlikely. A GOP source told me “there is no way” House Speaker Mike Johnson, the Louisiana Republican, “will call back people from the campaign trail to vote on this in the House.” So it may be too soon to turn the acronym into a name. But my humble suggestion is to pronounce BAAJA as BAH-zhuh, which sounds like Basha, my late grandmother’s name. I can only assume the rest of you are equally moved by that association.
South Korea is the only country in the democratic world with a strong, recent track record of building nuclear reactors competently and on time. Seoul’s state nuclear giant is also bound by a settlement with America’s flagship nuclear company, Westinghouse, which accused Korea Hydro & Nuclear Power of ripping off the design of the U.S. reactor, the AP1000. As a result, the Koreans can’t build their own reactors in North America or Europe. But in a bid to stave off President Donald Trump’s tariffs, South Korea has agreed to spend $200 billion on U.S. energy projects. That includes an investment into Alaska LNG, a major liquified natural gas terminal, a gas-fired station in Texas, and eight nuclear reactors, according to Bloomberg and Politico. The deal is the culmination of talks ongoing since the spring, as I previously reported, and comes amid swirling rumors in the South Korean press over whether Seoul could secure a stake in Westinghouse if the American company makes a debut on the stock market. In a statement, the Canadian uranium giant Cameco, which owns 49% of Westinghouse, said the eight reactors in the Korean deal “contemplates” the construction of as many as six new AP1000s and up to two Korean APR1400 reactors. Still, the company emphasized that it was focused on the Department of Energy’s condition loan commitment to finance AP1000 components for any joint venture between Westinghouse and a utility building one of its reactors. But it said that, if both the American and Korean reactors can be built successfully, “both technologies are expected to be deployed on federal sites designated” by the U.S. government, “beginning with the deployment of two AP1000 reactors.”
It’s unclear when the South Korean money will flow into actual projects on the ground. But New York is putting up dollars. On Tuesday, New York Governor Kathy Hochul awarded another $10 million to the New York Power Authority to support workforce development programs in a bid to train more people to staff the nuclear power stations her administration has tasked the state utility with financing. “Advanced nuclear is a cornerstone of my all-of-the-above strategy to keep the lights on and costs down for New Yorkers,” Hochul said in a statement. “The $10 million in funding approved today by the NYPA board will help ensure New York’s advanced nuclear future will be built by and for New Yorkers and also re-energize an industry that will create thousands of high-quality jobs while complementing our nation-leading efforts on wind and solar.” Canada, meanwhile, is upping its ambition. Saskatchewan’s provincial government announced plans this week to build at least two large-scale reactors by the early 2040s, NucNet reported.
When Secretary of Energy Chris Wright sat down with my colleague Robinson Meyer last week, he said he doubted the Trump administration would impose a temporary ban on exporting diesel amid record-high prices. But the Financial Times reported Wednesday that the White House was holding “crisis talks” to determine whether the move was merited. Experts have cautioned that it could lower diesel prices in the U.S. slightly, but would send prices soaring in Europe.
Russia, meanwhile, just renewed its ban on diesel exports, blunting both the effects of the global market chaos and the profits the Kremlin could be yielding given its rising crude exports, Bloomberg reported.
Sign up to receive Heatmap AM in your inbox every morning:
California Governor Gavin Newsom signed a series of bills Wednesday that clear the way for more homeowners in the state to slash their electricity costs and personal carbon footprints. Under one new law, utilities will offer a voluntary incentive to electrify homes whenever the pipe connecting a home to a gas main line is due for replacement. Under another, homeowners and even renters will be able to install plug-in solar panels that can generate small amounts of electricity on roofs or balconies.
As grows a market in the nation’s most populous state, so goes the country. The so-called balcony solar bill in particular is expected to supercharge the market, making cheap, personal solar panels more widely accessible. As my colleague Katie Brigham wrote last year, plug-in solar is popular in Europe, and could find a big market in the U.S. New York, for example, passed legislation this spring, though Hochul has yet to sign it.
Europe once boasted two cutting-edge green industrial manufacturers, both in Sweden, with shared investors and executives. Northvolt, an electric vehicle battery manufacturer, declared bankruptcy last year. That left only Stegra, the green steelmaker. Shortly after Northvolt went under, Stegra went looking for another financial lifeline to cover the mounting costs of commercializing its renewable electricity-based method for forging steel. It ultimately received one from a French hydrogen investor. Now Stegra says it needs more money to complete its flagship first project in northern Sweden. The company named former Saab aerospace executive Håkan Buskhe as its new chief executive, replacing Henrik Henriksson who served in the top role since 2021. The new leadership’s review of its books and plans revealed “that additional capital is required to complete the project, as estimated costs of completing it are significantly higher than assumed in June.” The high costs “are mainly the result of substantial ramp-up costs following the prolonged scaling back of work earlier this year, as well as inflation.”
The U.S., meanwhile, may be getting what Canary Media called a “lower carbon steel mill” in Iowa. Mesabi Metallics, which is already building America’s first new iron ore mine in 50 years, announced plans this week for a $15 billion steel plant in southeast Iowa that would rely on what’s called direct reduced iron, a cleaner method of making iron than a traditional coal-fired blast furnace. As my colleague Emily Pontecorvo wrote last year, the Trump administration may have violated the law when it diverted Energy Department funding from a green steel project in Ohio to instead reboot a blast furnace. Hyundai is also building a gas-powered DRI steel mill in Louisiana, which the automaker plans to eventually run on low-carbon hydrogen, as I previously reported.

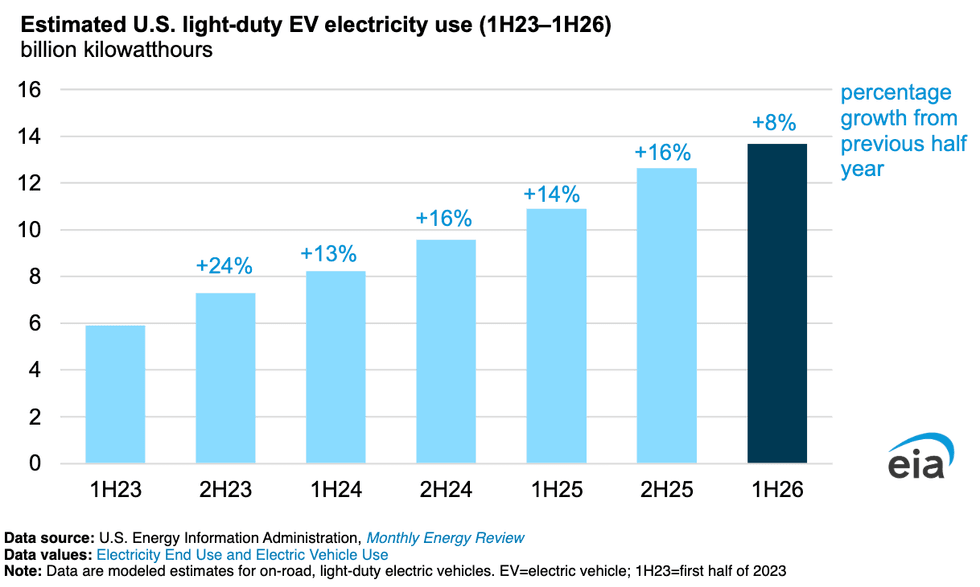
Before the artificial intelligence boom (and its less sexy older brother, the cryptomining boom), electricity demand growth was a problem many proponents of decarbonization actually wanted, because it would mean electrification was taking off. Last year, record EV sales translated into record 16% growth in electricity demand for charging the light-duty battery electric vehicles. But this year the growth fell by half to just 8%, according to the latest analysis by the U.S. Energy Information Administration.