You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
In practice, direct lithium extraction doesn’t quite make sense, but 2026 could be its critical year.

Lithium isn’t like most minerals.
Unlike other battery metals such as nickel, cobalt, and manganese, which are mined from hard-rock ores using drills and explosives, the majority of the world’s lithium resources are found in underground reservoirs of extremely salty water, known as brine. And while hard-rock mining does play a major role in lithium extraction — the majority of the world’s actual production still comes from rocks — brine mining is usually significantly cheaper, and is thus highly attractive wherever it’s geographically feasible.
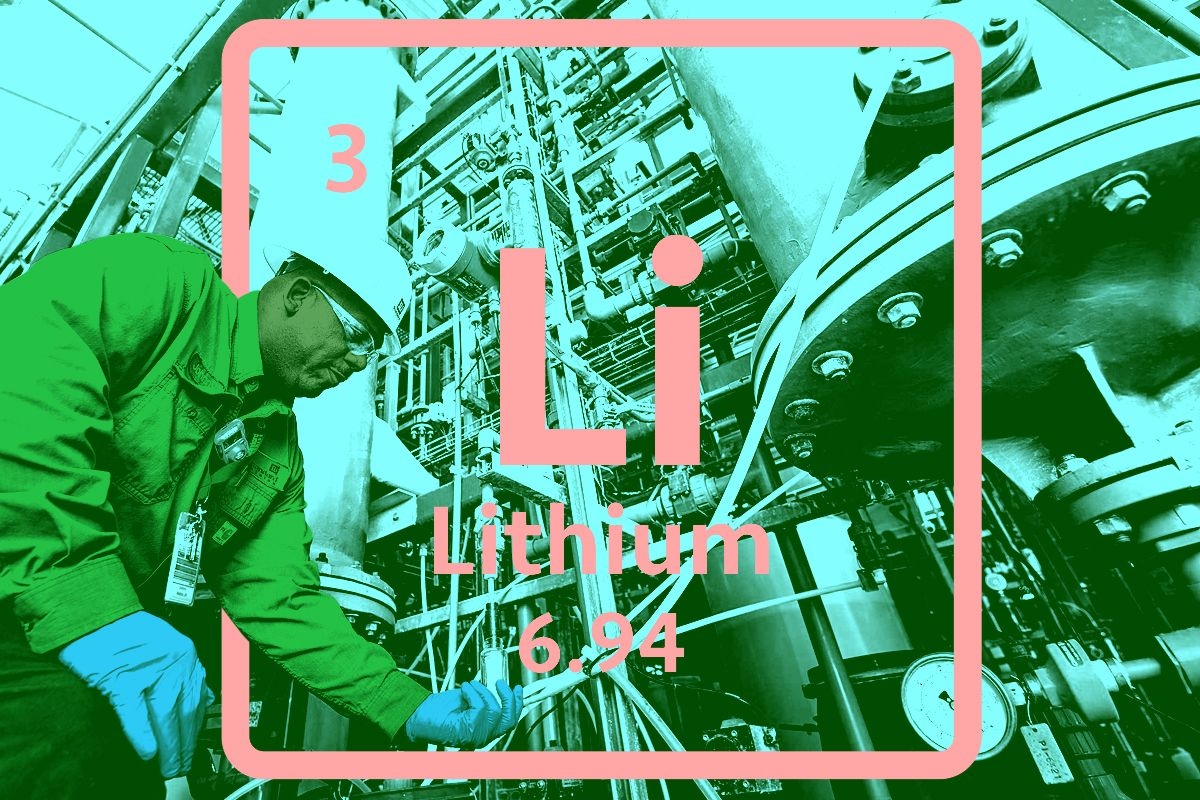
Reaching that brine and extracting that lithium — so integral to grid-scale energy storage and electric vehicles alike — is typically slow, inefficient, and environmentally taxing. This year, however, could represent a critical juncture for a novel process known as Direct Lithium Extraction, or DLE, which promises to be faster, cleaner, and capable of unlocking lithium across a wider range of geographies.
The traditional method of separating lithium from brine is straightforward but time-consuming. Essentially, the liquid is pumped through a series of vast, vividly colored solar evaporation ponds that gradually concentrate the mineral over the course of more than a year.
It works, but by the time the lithium is extracted, refined, and ready for market, both the demand and the price may have shifted significantly, as evidenced by the dramatic rise and collapse of lithium prices over the past five years. And while evaporation ponds are well-suited to the arid deserts of Chile and Argentina where they’re most common, the geology, brine chemistry, and climate of the U.S. regions with the best reserves are generally not amenable to this approach. Not to mention the ponds require a humongous land footprint, raising questions about land use and ecological degradation.
DLE forgoes these expansive pools, instead pulling lithium-rich brine into a processing unit, where some combination of chemicals, sorbents, or membranes isolate and extricate the lithium before the remaining brine gets injected back underground. This process can produce battery-grade lithium in a matter of hours or days, without the need to transport concentrated brine to separate processing facilities.
This tech has been studied for decades, but aside from a few Chinese producers using it in combination with evaporation ponds, it’s largely remained stuck in the research and development stage. Now, several DLE companies are looking to build their first commercial plants in 2026, aiming to prove that their methods can work at scale, no evaporation ponds needed.
“I do think this is the year where DLE starts getting more and more relevant,” Federico Gay, a principal lithium analyst at Benchmark Mineral Intelligence, told me.
Standard Lithium, in partnership with oil and gas major Equinor, aims to break ground this year on its first commercial facility in Arkansas’s lithium-rich Smackover Formation, while the startup Lilac Solution also plans to commence construction on a commercial plant at Utah’s Great Salt Lake. Mining giant Rio Tinto is progressing with plans to build a commercial DLE facility in Argentina, which is already home to one commercial DLE plant — the first outside of China. That facility is run by the French mining company Eramet, which plans to ramp production to full capacity this year.
If “prices are positive” for lithium, Gay said, he expects that the industry will also start to see mergers and acquisitions this year among technology providers and larger corporations such as mining giants or oil and gas majors, as “some of the big players will try locking in or buying technology to potentially produce from the resources they own.” Indeed, ExxonMobil and Occidental Petroleum are already developing DLE projects, while major automakers have invested, too.
But that looming question of lithium prices — and what it means for DLE’s viability — is no small thing. When EV and battery storage demand boomed at the start of the decade, lithium prices climbed roughly 10-fold through 2022 before plunging as producers aggressively ramped output, flooding the market just as EV demand cooled. And while prices have lately started to tick upward again, there’s no telling whether the trend will continue.
“Everyone seems to have settled on a consensus view that $20,000 a tonne is where the market’s really going to be unleashed,” Joe Arencibia, president of the DLE startup Summit Nanotech, told me, referring to the lithium extraction market in all of its forms — hard rock mining, traditional brine, and DLE. “As far as we’re concerned, a market with $14,000, $15,000 a tonne is fine and dandy for us.”
Lilac Solutions, the most prominent startup in the DLE space, expects that its initial Utah project — which will produce a relatively humble 5,000 tonnes of lithium per year — will be profitable even if lithium prices hit last year’s low of $8,300 per tonne. That’s according to the company’s CEO Raef Sully, who also told me that because Utah’s reserves are much lower grade than South America’s, Lilac could produce lithium for a mere $3,000 to $3,500 in Chile if it scaled production to 15,000 or 20,000 tonnes per year.
What sets Lilac apart from other DLE projects is its approach to separating lithium from brine. Most companies are pursuing adsorption-based processes, in which lithium ions bind to an aluminum-based sorbent, which removes them from surrounding impurities. But stripping the lithium from the sorbent generally requires a good deal of freshwater, which is not ideal given that many lithium-rich regions are parched deserts.
Lilac’s tech relies on an ion-exchange process in which small ceramic beads selectively capture lithium ions from the brine in their crystalline structure, swapping them for hydrogen ions. “The crystal structure seems to have a really strong attraction to lithium and nothing else,” Sully told me. Acid then releases the concentrated lithium. When compared with adsorption-based tech, he explained, this method demands far fewer materials and is “much more selective for lithium ions versus other ions,” making the result purer and thus cheaper to process into a battery-grade material.
Because adsorption-based DLE is already operating commercially and ion-exchange isn’t, Lilac has much to prove with its first commercial facility, which is expected to finalize funding and begin construction by the middle of this year.
Sully estimates that Lilac will need to raise around $250 million to build its first commercial facility, which has already been delayed due to the price slump. The company’s former CEO and current CTO Dave Snydacker told me in 2023 that he expected to commence commercial operations by the end of 2024, whereas now the company plans to bring its Utah plant online at the end of 2027 or early 2028.
“Two years ago, with where the market was, nobody was going to look at that investment,” Sully explained, referring to its commercial plant. Investors, he said, were waiting to see what remained after the market bottomed out, which it now seems to have done. Lilac is still standing, and while there haven’t yet been any public announcements regarding project funding, Sully told me he’s confident that the money will come together in time to break ground in mid-2026.
It also doesn’t hurt that lithium prices have been on the rise for a few months, currently hovering around $20,000 per tonne. Gay thinks prices are likely to stabilize somewhere in this range, as stakeholders who have weathered the volatility now have a better understanding of the market.
At that price, hard rock mining would be a feasible option, though still more expensive than traditional evaporation ponds and far above what DLE producers are forecasting. And while some mines operated at a loss or mothballed their operations during the past few years, Gay thinks that even if prices stabilize, hard-rock mines will continue to be the dominant source of lithium for the foreseeable future due to sustained global investment across Africa, Brazil, Australia, and parts of Asia. The price may be steeper, but the infrastructure is also well-established and the economics are well-understood.
“I’m optimistic and bullish about DLE, but probably it won’t have the impact that it was thought about two or three years ago,” Gay told me, as the hype has died down and prices have cooled from their record high of around $80,000 per tonne. By 2040, Benchmark forecasts that DLE will make up 15% to 20% of the lithium market, with evaporation ponds continuing to be a larger contributor for the next decade or so, primarily due to the high upfront costs of DLE projects and the time required for them to reach economies of scale.
On average, Benchmark predicts that this tech will wind up in “the high end of the second quartile” of the cost curve, making DLE projects a lower mid-cost option. “So it’s good — not great, good. But we’ll have some DLE projects in the first quartile as well, so competing with very good evaporation assets,” Gay told me.
Unsurprisingly, the technology companies themselves are more bullish on their approach. Even though Arencibia predicts that evaporation ponds will continue to be about 25% cheaper, he thinks that “the majority of future brine projects will be DLE,” and that DLE will represent 25% or more of the future lithium market.
That forecast comes in large part because Chile — the world’s largest producer of lithium from brine — has stated in its National Lithium Strategy that all new projects should have an “obligatory requirement” to use novel, less ecologically disruptive production methods. Other nations with significant but yet-to-be exploited lithium brine resources, such as Bolivia, could follow suit.
Sully is even more optimistic, predicting that as lithium demand grows from about 1.5 million tonnes per year to around 3.5 million tonnes by 2035, the majority of that growth will come from DLE. “I honestly believe that there will be no more hard rock mines built in Australia or the U.S.,” he said, telling me that in ten years time, half of our lithium supply could “easily” come from DLE.
As a number of major projects break ground this year and the big players start consolidating, we’ll begin to get a sense of whose projections are most realistic. But it won’t be until some of these projects ramp up commercial production in the 2028 to 2030 timeframe that DLE’s market potential will really crystalize.
“If you’re not a very large player at the moment, I think it’s very difficult for you to proceed,” Sully told me, reflecting on how lithium’s price shocks have rocked the industry. Even with lithium prices ticking precariously upwards now, the industry is preparing for at least some level of continued volatility and uncertainty.
“Long term, who knows what [prices are] going to be,” Sully said. “I’ve given up trying to predict.”
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Spoiler: They’re mostly winners.
There’s seemingly plenty to celebrate in the Senate’s new 400-plus-page permitting reform bill, the Bipartisan American Affordability and Jobs Act, or BAAJA. The headline benefit — and the one drawing the most praise from energy hawks — is that expediting the buildout of energy infrastructure and transmission lines ought to bring tons more zero-carbon energy online. No doubt it will speed up fossil fuel projects as well, but modeling shows that renewables like wind and solar are disproportionately held back by the notoriously contentious and slow planning and permitting processes the bill seeks to overhaul.
Old-school renewables aren’t the only technologies that stand to benefit from BAAJA, however.
Here are four more climate tech sectors — and the startups working in them — that are probably pretty happy to see that, after four years of debate and countless failed negotiations, a permitting bill finally appears poised to become law.
No surprises here: It’s well known at this point that geothermal is a beloved bipartisan technology, and BAAJA affirms the government’s commitment to bringing more of this clean, firm energy source online as soon as possible.
The bill would categorically exclude drilling exploratory geothermal test wells from review under the National Environmental Policy Act, and exempt lower-impact activities such as mapping and surface surveying from NEPA entirely. It would also require the Interior Department to hold annual geothermal lease sales, and drop the federal drilling permit requirement for geothermal exploration on non-federal land, so long as the government owns less than half of the underground resource.
Next-generation geothermal companies such as Fervo Energy, Sage Geosystems, Mazama Energy, and Quaise Energy stand to benefit, of course, as finding viable sites to trial their tech and build early commercial projects requires plenty of mapping and exploratory drilling. This cohort aims to expand geothermal beyond the relatively small number of geographies with the ideal combination of high heat at shallow depths, naturally occurring subsurface water or steam, and permeable rock that conventional geothermal power plants rely on. But a company like Zanskar, which uses AI to identify overlooked conventional geothermal resources, stands to benefit, too — its approach also depends on scouting and drilling across many sites.
BAAJA is intent on advancing tech that can squeeze more capacity out of the transmission lines we already have. The bill requires utilities to conduct recurring evaluations on technologies that could increase the capacity of existing transmission infrastructure, such as higher-capacity replacement wires or monitoring systems that determine when the lines can safely carry more power. Investor-owned utilities have historically had little incentive to adopt any of this, since they earn money by building new infrastructure, not by making existing infrastructure more efficient. Now, that math could change. If the evaluations find this tech will provide net benefits, utilities are required to deploy it within a certain timeframe, lest the Federal Energy Regulatory Commission impose penalties.
That’s welcome news for dynamic line rating startups such as LineVision and Heimdall Power, which use sensors to monitor power lines in real time to determine when they’re capable of carrying more electricity than their fixed ratings allow. Companies building higher-capacity lines are also likely to see more business. This includes TS Conductor, which makes a carbon-fiber core wire that it says can double or even triple a line’s capacity, and VEIR, which originally aimed to build “high-temperature superconducting transmission lines,” though it recently pivoted to data center power solutions. Startups like NewGrid, whose software finds ways to avoid congested lines and route more electricity through the existing grid, could benefit, too.
The bill also opens doors for virtual power plants, networks of distributed energy resources such as rooftop solar panels, batteries, smart thermostats, and electric vehicle chargers that operate like a single power plant, responding to spikes in energy demand or shifting load to off-peak hours. Like grid-enhancing technologies, VPPs can reduce the need for new poles, wires, and power plants by making better use of the energy resources already installed in homes and businesses. And they also include an added perk: They pay these customers for adjusting their energy use when the grid needs it.
While FERC ordered grid operators to open their markets to these aggregators in 2020, implementation has dragged. BAAJA would speed things up by requiring operators to allow VPPs into their markets within 18 months of the bill’s passage and setting a low, 100-kilowatt threshold for device networks to be considered VPP-eligible. It would also require utilities to connect VPPs quickly and allow them to export power, while barring utilities from requiring aggregators to install the utilities’ own equipment like separate submeters and switches, which adds delays and added costs for hardware and installation. Separately, the bill directs the Department of Energy to fund efforts to streamline local government permitting and inspections for distributed energy resources like rooftop solar and batteries.
This is a boon for aggregators including Voltus, Renew Home, and David Energy, which sell grid services like demand response, capacity, and frequency regulation into utility programs and wholesale markets. Under this bill, they could do so more easily thanks to guaranteed market access and lower entry thresholds.
VPP software platforms like Leap could benefit, too. Leap helps manufacturers of devices such as smart thermostats and EV chargers enroll customers in VPP programs, so fewer utility equipment requirements and what will presumably be a much bigger addressable market would help. Home battery companies such as Lunar Energy and Base Power, which aggregate their residential batteries into VPPs, and smart panel-maker Span, which coordinates home appliances to respond to grid needs, could see similar benefits.
Hard rock mining is also among the bill’s clear winners. It clarifies that miners can use as much federal land as is “reasonably necessary” to store waste rock and tailings, and opens additional federal land for hard-rock mining leases. It also requires lawsuits challenging mining approvals to be filed within 150 days. Broader changes to NEPA, the National Historic Preservation Act, and the Clean Water Act will also accelerate the mining approval process.
This will undoubtedly be controversial for many climate advocates; while the energy transition demands more critical minerals, mining itself is a dirty endeavor. Yet there are a number of climate tech-adjacent companies focused on extracting, refining, and processing materials like lithium, nickel, cobalt and copper that stand to benefit.
One of the buzziest startups trying to develop new critical minerals mines, AI-driven exploration and development company KoBold Metals, is mainly working abroad right now. But a more favorable domestic environment could prove an enticement to invest more at home. Mariana Minerals, a software-driven developer working to bring mines online faster and cheaper, definitely stands to benefit given its current domestic focus. So could startups like Jetti and Endolith, which are developing technology to extract more copper from low-grade ores. Both work with existing mines, so could stand to profit from a domestic mining boom.
Of course not everyone will win here. For the horde of climate-tech adjacent startups trying to jump on the data center bandwagon — perhaps those working on chip cooling or capturing and recycling the waste heat from data center servers — maybe the added costs this bill imposes on data centers will reduce demand for their services just a bit. But I wouldn’t count on that. The bill certainly won’t stop the buildout so much as change who pays for some of the infrastructure required to serve it, shifting the cost of new power lines and grid upgrades from ratepayers onto the tech giants and developers themselves.
Then there are the myriad software startups such as Nira Energy, Paces, and Piq Energy that help energy developers navigate the grid interconnection process. Since the bill requires regional grids to streamline their queues, this could reduce demand for their services. But developers will still need to know where the grid has room and where projects pencil out, and utilities and grid operators will have to rebuild their interconnection processes, a transition that could generate demand for software of this sort.
There’s also just an array of climate industries that go largely unaddressed. While the Inflation Reduction Act offered incentives for practically every decarbonization technology under the sun, this bill is far more targeted, leaving sectors such as EV manufacturing, industrial decarbonization products like clean cement and steel, agricultural technologies, and methane abatement relatively untouched.
Carbon capture and removal projects, EV charging, and hydrogen get only minor nods: protection from administrative delays for carbon management projects and DOE funding to help local governments expedite permitting for EV chargers and hydrogen refueling stations. All of these industries could still benefit when building manufacturing plants or other facilities that need federal sign offs. But they could also lose ground if speedier approvals for fossil fuel infrastructure make cleaner alternatives less competitive.
On Korean reactors, California plug-in solar, and Europe’s green steel champion
Current conditions: Floodwaters from the remnants of Hurricane Polo breached a 20-foot dam in southern New Mexico, forcing evacuations • The Pacific’s active hurricane season continues as Hurricane Rachel threatens dangerous rip tides off Baja California • Further north in the Pacific, Tropical Storm Choi-wan is headed toward the Northern Mariana Islands.
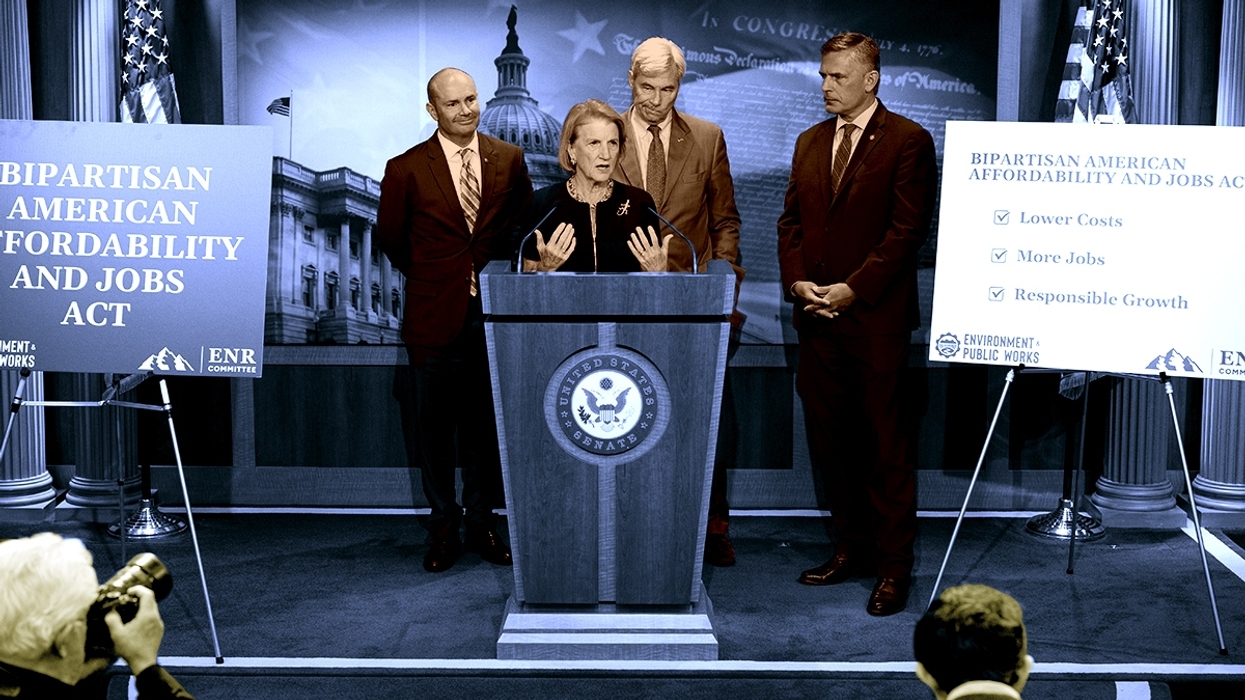
It’s 417 pages — or, for those of you who think in such terms, roughly two-and-a-three-quarters the length of a standard environmental impact statement. And it the landed yesterday with much fanfare. The Senate’s grand compromise on permitting reform, dubbed the Bipartisan American Affordability and Jobs Act, or BAAJA, is packed with sweeping changes that promise to upend how data centers are built, whether transmission lines get constructed at all, and speed up deployments of all kinds of energy infrastructure. My colleagues — there are five bylines on this sucker, if you have any doubt about how seriously Heatmap is taking this — have a dense and comprehensive explainer here.
Whether the bill becomes law is another question. Already, House Democrats are casting doubt over whether they will vote for the legislation during the lame-duck session after Republicans likely lose control of at least the lower chamber of Congress in November’s midterm elections. “Most Democrats will want to see how things go on Nov. 3 and then do a reality check,” Representative Jared Huffman, a California Democrat, told Bloomberg reporter Ari Natter. “If we’re on our way to a majority in one or both Houses, it makes no sense to fold our hand when we could wait a few months and have a much better deal early next year.” Any hope of brokering a deal to vote on the bill before the election seems unlikely. A GOP source told me “there is no way” House Speaker Mike Johnson, the Louisiana Republican, “will call back people from the campaign trail to vote on this in the House.” So it may be too soon to turn the acronym into a name. But my humble suggestion is to pronounce BAAJA as BAH-zhuh, which sounds like Basha, my late grandmother’s name. I can only assume the rest of you are equally moved by that association.
South Korea is the only country in the democratic world with a strong, recent track record of building nuclear reactors competently and on time. Seoul’s state nuclear giant is also bound by a settlement with America’s flagship nuclear company, Westinghouse, which accused Korea Hydro & Nuclear Power of ripping off the design of the U.S. reactor, the AP1000. As a result, the Koreans can’t build their own reactors in North America or Europe. But in a bid to stave off President Donald Trump’s tariffs, South Korea has agreed to spend $200 billion on U.S. energy projects. That includes an investment into Alaska LNG, a major liquified natural gas terminal, a gas-fired station in Texas, and eight nuclear reactors, according to Bloomberg and Politico. The deal is the culmination of talks ongoing since the spring, as I previously reported, and comes amid swirling rumors in the South Korean press over whether Seoul could secure a stake in Westinghouse if the American company makes a debut on the stock market. In a statement, the Canadian uranium giant Cameco, which owns 49% of Westinghouse, said the eight reactors in the Korean deal “contemplates” the construction of as many as six new AP1000s and up to two Korean APR1400 reactors. Still, the company emphasized that it was focused on the Department of Energy’s condition loan commitment to finance AP1000 components for any joint venture between Westinghouse and a utility building one of its reactors. But it said that, if both the American and Korean reactors can be built successfully, “both technologies are expected to be deployed on federal sites designated” by the U.S. government, “beginning with the deployment of two AP1000 reactors.”
It’s unclear when the South Korean money will flow into actual projects on the ground. But New York is putting up dollars. On Tuesday, New York Governor Kathy Hochul awarded another $10 million to the New York Power Authority to support workforce development programs in a bid to train more people to staff the nuclear power stations her administration has tasked the state utility with financing. “Advanced nuclear is a cornerstone of my all-of-the-above strategy to keep the lights on and costs down for New Yorkers,” Hochul said in a statement. “The $10 million in funding approved today by the NYPA board will help ensure New York’s advanced nuclear future will be built by and for New Yorkers and also re-energize an industry that will create thousands of high-quality jobs while complementing our nation-leading efforts on wind and solar.” Canada, meanwhile, is upping its ambition. Saskatchewan’s provincial government announced plans this week to build at least two large-scale reactors by the early 2040s, NucNet reported.
When Secretary of Energy Chris Wright sat down with my colleague Robinson Meyer last week, he said he doubted the Trump administration would impose a temporary ban on exporting diesel amid record-high prices. But the Financial Times reported Wednesday that the White House was holding “crisis talks” to determine whether the move was merited. Experts have cautioned that it could lower diesel prices in the U.S. slightly, but would send prices soaring in Europe.
Russia, meanwhile, just renewed its ban on diesel exports, blunting both the effects of the global market chaos and the profits the Kremlin could be yielding given its rising crude exports, Bloomberg reported.
Sign up to receive Heatmap AM in your inbox every morning:
California Governor Gavin Newsom signed a series of bills Wednesday that clear the way for more homeowners in the state to slash their electricity costs and personal carbon footprints. Under one new law, utilities will offer a voluntary incentive to electrify homes whenever the pipe connecting a home to a gas main line is due for replacement. Under another, homeowners and even renters will be able to install plug-in solar panels that can generate small amounts of electricity on roofs or balconies.
As grows a market in the nation’s most populous state, so goes the country. The so-called balcony solar bill in particular is expected to supercharge the market, making cheap, personal solar panels more widely accessible. As my colleague Katie Brigham wrote last year, plug-in solar is popular in Europe, and could find a big market in the U.S. New York, for example, passed legislation this spring, though Hochul has yet to sign it.
Europe once boasted two cutting-edge green industrial manufacturers, both in Sweden, with shared investors and executives. Northvolt, an electric vehicle battery manufacturer, declared bankruptcy last year. That left only Stegra, the green steelmaker. Shortly after Northvolt went under, Stegra went looking for another financial lifeline to cover the mounting costs of commercializing its renewable electricity-based method for forging steel. It ultimately received one from a French hydrogen investor. Now Stegra says it needs more money to complete its flagship first project in northern Sweden. The company named former Saab aerospace executive Håkan Buskhe as its new chief executive, replacing Henrik Henriksson who served in the top role since 2021. The new leadership’s review of its books and plans revealed “that additional capital is required to complete the project, as estimated costs of completing it are significantly higher than assumed in June.” The high costs “are mainly the result of substantial ramp-up costs following the prolonged scaling back of work earlier this year, as well as inflation.”
The U.S., meanwhile, may be getting what Canary Media called a “lower carbon steel mill” in Iowa. Mesabi Metallics, which is already building America’s first new iron ore mine in 50 years, announced plans this week for a $15 billion steel plant in southeast Iowa that would rely on what’s called direct reduced iron, a cleaner method of making iron than a traditional coal-fired blast furnace. As my colleague Emily Pontecorvo wrote last year, the Trump administration may have violated the law when it diverted Energy Department funding from a green steel project in Ohio to instead reboot a blast furnace. Hyundai is also building a gas-powered DRI steel mill in Louisiana, which the automaker plans to eventually run on low-carbon hydrogen, as I previously reported.

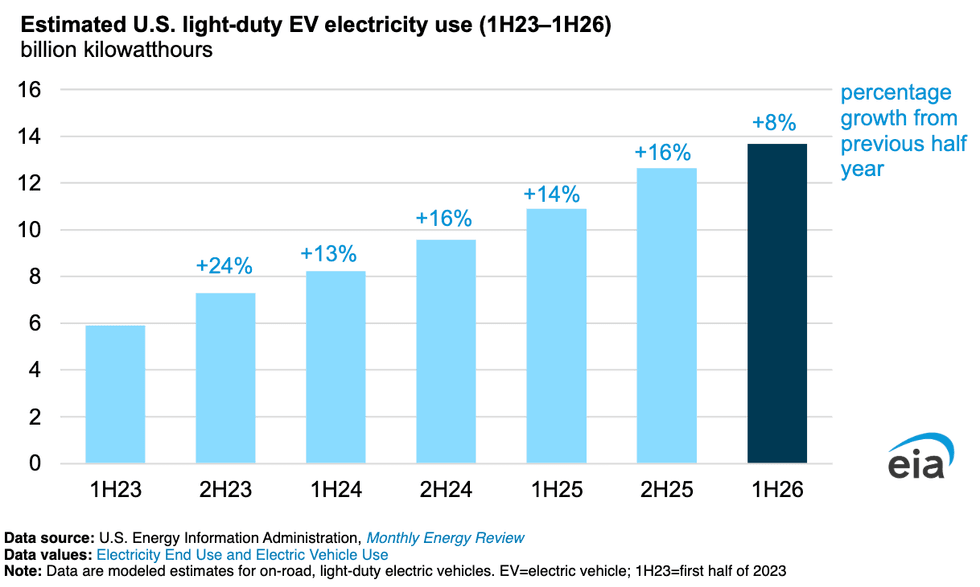
Before the artificial intelligence boom (and its less sexy older brother, the cryptomining boom), electricity demand growth was a problem many proponents of decarbonization actually wanted, because it would mean electrification was taking off. Last year, record EV sales translated into record 16% growth in electricity demand for charging the light-duty battery electric vehicles. But this year the growth fell by half to just 8%, according to the latest analysis by the U.S. Energy Information Administration.
Controlled Thermal Resources has completed key financial steps ahead of its planned Nasdaq debut.
California’s inland Salton Sea is a potential clean energy double dip, with vast and largely untapped geothermal hotspots for generating heat and electricity and rich deposits of lithium, manganese, and other critical minerals needed to fuel the battery revolution.
Now one of the companies looking to commercialize both resources is taking a big step toward debuting on the stock market.
On Thursday, Controlled Thermal Resources is set to announce that it’s converting $205 million of debt into equity ahead of a planned initial public offering on the Nasdaq later this year, Heatmap can exclusively report. Among the big investors swapping debt for a stake in the Imperial, California-headquartered startup is the automaker Stellantis, according to a source with direct knowledge of the deal.
“Like a lot of our colleagues in this industry, we need to raise a lot of capital to build out a multi-stage project,” Rod Colwell, CTR’s chief executive, told me this week. An IPO, he said, “is a mechanism that enables us to keep going back to the market as we build out our 650-plus megawatts and supporting infrastructure that follows.”
He declined to comment on what interest Stellantis, which owns brands such as Chrysler, Jeep, and Maserati, has in the deal. The Dutch auto giant did not respond to multiple requests for comment.
“Automakers who successfully build out a resilient EV supply chain, including mining and mineral processing, will be in a good position to compete as the U.S. auto market continues to evolve in the years ahead,” Corey Cantor, the research director at the trade group Zero Emission Transportation Association, told me via email. With electric vehicles sales also booming globally, “having a more resilient supply chain up and running soon is more important than ever.”
CTR isn’t pursuing a traditional IPO. Instead, the startup is planning to go public via a merger with a special purpose acquisition company, a so-called blank-check firm that’s already trading, allowing the actual primary entity to swiftly issue stock to retail investors. While plenty of SPAC deals have proven volatile in recent years, particularly in cutting-edge clean energy, geothermal stocks are particularly — forgive me — hot.
Fervo Energy, the country’s frontrunner in developing next-generation geothermal power plants, is racing to complete its first major facility, known as Cape Station. Shares in the Houston-based firm skyrocketed after its IPO in May, though the price has sunk in the intervening months.
With demand for electricity soaring, CTR shifted its strategy to focus on building its debut 50-megawatt geothermal power station. Power and heat from that facility will, in turn, be used to extract and process lithium and other minerals from the briny inland lake.
CTR said it aims to move forward with its plant next June, with the facility expected to come online in 2028.
“Shortly thereafter, we’ll be building out the critical minerals component,” Colwell said. “That’ll be commissioned in 2030.”
Editor’s note: This story has been updated to correct the generation capacity of CTR’s debut power station.