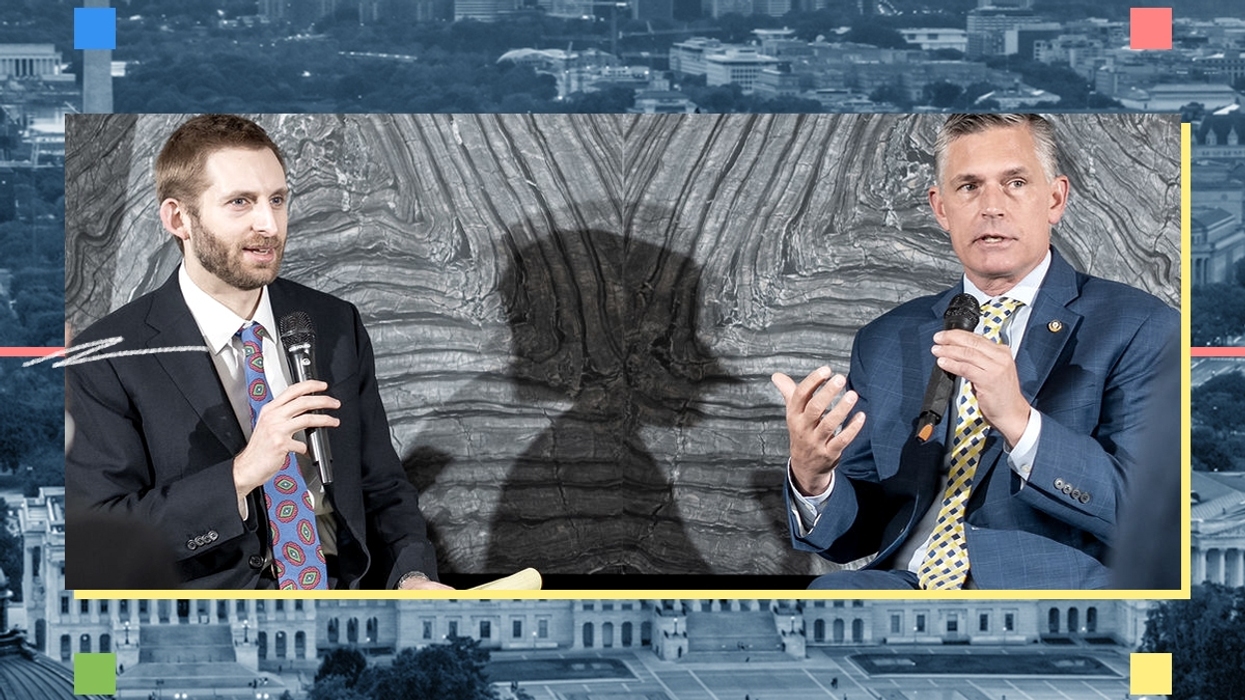
Heinrich and I have spoken about permitting and power lines repeatedly over the past year, but what were once niche issues in the space — such as when and whether a president can revoke an energy project’s permits — have turned into major disagreements within and between environmental groups, the clean energy industry, and liberal lawmakers.
At the same time, Heinrich is on the verge of a major climate policy victory with the bill, which would finally create a one-stop shop for large-scale power line approvals in the federal government. The bill would put transmission lines, which can carry zero-carbon electricity, on a more equal footing with natural gas pipelines, which already enjoy fast-track federal approval.
“My goal here is to take the politics out of permitting,” Heinrich told me at the event. “If you’ve done everything right — and you get your final permit to actually construct — you should be able to take that to the bank.”
We discussed the bill path to passage and his replies to some of critics’ biggest arguments against the bill, including whether it will push data centers to build more behind-the-meter natural gas power plants. We also discussed whether Congress should restore the wind and solar tax credits, how this bill was informed by the Biden administration’s struggles, and why Heinrich believes lawmakers should take this deal, now, even though some of his colleagues have urged waiting until the new Congress starts in January.
This conversation has been edited for readability and concision.
How are you feeling? And how are you feeling about the number last night?
Seventy-three is a great number. It suggests we’re on track to get this done. And I think we just need to be patient and let the process play out.
We were talking in the green room a little bit. I think one of the things that worries me about today’s politics is that we’re having this really substantive discussion here, and with members, with the House and Senate back and forth, which is super healthy, and that hasn’t really happened often enough in recent years. And then there’s the algorithmic, online, like, light-everyone’s-hair-on-fire [conversation]. Those two things are completely divergent streams, and they make me worry about democracy as a whole.
Not to mention the fact that we need to be able to build big things in this country, and that’s what this legislation represents. How do you actually deliver on the affordability question that was central to the election we just had? How do we make sure that our country competes in the world? All of those things. But the gap between those two conversations is something that we have to solve for in the politics of today. And there were people who should have been with us [last night] who weren’t, and I think it’s indicative of that gap.
As someone who’s been reporting on the bill, and knows the policy, and knows, for instance, where the fault lines in the policy are, it has been striking how much the social media discussion of the bill has been focused on creating sufficiently plausible lies that go just viral enough to poison the politics. And make it so you can’t even talk about the bill, because, why would you ever even consider such a horrible thing?
It’s been interesting — I’ve got a 23-year-old who’s in graduate school in New Mexico, and he has a really good sense of who I am and what I care about. For him to see protests on his campus, or protests on the overpass in Albuquerque — and how divergent that is from the goals of this legislation — those conversations have been really interesting. I think if I wasn’t so comfortable in what I actually care about, and what I want to get done in my time in Washington, D.C. — which like, this is not my identity, it’s a path to making a change. I think it would be really hard to do this if I weren’t so comfortable in what we need to do on this issue.
In the run-up to last night’s vote, there were a number of endorsements of the bill or the motion to proceed. What was the biggest whip victory for you or Senator Whitehouse?
When you hit above 70, your caucus is taking your work very seriously, and given the attempts to poison the well early on, I was just very encouraged by the fact that in our caucus — we had a caucus meeting over the weekend on this, and then we obviously had the vote last night — there’s a certain implicit trust in a number over 70.
People want to get to yes. They understand that at the end of the day, the American people really do want us to make life cheaper. Like, this election is not a mandate, it’s a job interview, right? And if we can’t deliver on it, and we can’t do the things that make people’s lives better, we’re gonna — it’s going to be very fleeting.
The outside assessments of the bill report numbers anywhere from power grid cost savings in the hundreds of billions to single-digit percentage reductions of power bills in a decade or so. Do you feel like those estimates capture the benefits of the bill, or are the benefits largely unquantifiable?
No, I think they’re quantifiable. I think the emissions reductions are quantifiable.
I think if all we did in this bill was the data center provision, that says you can’t keep exporting your costs onto customers, you actually have to pay your own freight — and that’s not something that the data center developers are all aghast at, I blame some of the utilities for passing those costs along to customers. That’s outrageous. Just because you can ratebase things doesn’t mean you should ratebase things, and the public is fucking pissed off, and they should be — but if all we did is transfer that $35 billion from data center developers into the pockets of consumers, I would be enthusiastic about this bill.
But we do a whole lot more than that, right? There’s almost no conversation right now about the value of virtual power plants and distributed energy resources, and all the changes in leasing for geothermal. There are things that I’ve been working on my entire career that we couldn’t get — well, we still, I guess, haven’t gotten — the public to focus on. But if we can get them done, it really opens up a future for the power grid that looks so different from the power grid I grew up with. I grew up around the kitchen table with an IBEW dad, and we would talk about the power grid all the time. And it was a one-way deal. You had a dam or a coal-fired power plant, and then [electricity] would go out across the big wires, and then it would get into the little wires, and then people in homes and businesses would consume that power. We’re now talking about a two-way power grid that is so much more complicated and efficient than that, and that’s what’s getting lost in this conversation. But it’s also what I’m really excited about.
Let’s talk about the criticism of the bill. You mentioned the data center ratepayer protection policies, which we’ve covered at Heatmap. They are quite substantive. I have begun to hear a concern that they are so substantive that they’ll push data centers even further away from using the grid — that they’ll push data center developers to be like, Oh, this is raising the cost of power, I’m going to build more offsite gas than I would.
I don’t know a single hyperscaler who’s saying that, and we’ve had all these conversations about off-grid behind-the-meter generation. It is so much more expensive. It is so much more difficult to operate and maintain. It’s insane to build a data center that is not connected to the grid. Like, these people now talking about repurposing airplane engines to run data centers — that’s nuts. If you want to put the cost of maintaining that kind of operation, go for it, because it’s going to fail.
It makes sense to have stuff connected to the grid because you don’t have to pay the full freight of the worst day of the entire year, and spread that over the rest of the year. That’s why we have a grid. I just don’t see that as a viable business plan for anyone.
This bill makes it easier to build federal infrastructure projects. I’ve seen people say, ‘Look, if we do this now, then the president gets two years to build whatever he wants, and that includes ICE detention centers.’
No. We have walked through the legal cases in places like New Jersey to make sure that we’re not facilitating that.
I don’t think this bill will measurably change what this president can accomplish because it’s going to take multiple years … Like right now, it takes two decades to build a really important interregional transmission line. It’s still going to take five years after this bill. This is not some magic wand. It’s way better. It makes us much more competitive against China and our near-peer competitors around the globe. But you’re still going to take multiple years to do an [Environmental Impact Statement]. So this is not going to impact this president measurably one way or the other.
But it is going to measurably impact the next president. And I can tell you, as someone who was around for the Biden administration, we passed incredible legislation. The Bipartisan Infrastructure Law and the [Inflation Reduction Act] were huge lifts in terms of legislation. But the president of the United States could not deliver on those promises because the permitting regime was a 10-year-plus regime. So even though he had all the funding you could imagine, and you had [the Department of Energy] and the Department of Interior all lined up, President Biden could not deliver on those promises in a time frame that the American people could appreciate.
Is that because of procedure or because of staffing? Because some people have responded to this bill by saying, ‘Well, we know we have to staff up these agencies, and this bill doesn’t do that.’ If Biden had been able to staff those agencies, would they have been able to move a lot faster?
They would have been able to move measurably faster, yeah, but it would not be sufficient. I’m all for restaffing those agencies. We authorize a lot more funding for things like Tribal and state historic preservation officers in this legislation, but it wouldn’t have been sufficient. It just wouldn’t have.
And you look at — I mean, the fact on SunZia, which, you’re as educated on that transmission line as anybody I’ve met in the press. It took, what, 17 years [to permit]? That’s one of the best projects that I’ve ever interacted with. It was 3.6 gigawatts of clean power. They did a great job of doing mitigation. They bought property that had enormous environmental value in my state. They engaged with stakeholders as well as any developer I’ve ever seen, like 17 to 18 years [to permit it]? That’s nuts. We can’t iterate on that kind of a timescale. I mean, John Podesta came back into the White House under the Biden administration and was like, ‘Didn’t we do this? I thought we already did this.’ It took two records of decision. That’s just not a recipe for success.
You mentioned [Biden’s former climate adviser] John Podesta. We reported on comments he made saying this bill would not allow a president to reverse a permit that had been granted illegally.
No, that’s not true. If you don’t follow the law, the permit can be overturned. So first and foremost, you have to have fidelity to the actual underlying statute. So if you violate the Mineral Leasing Act, or you violate some other statute that determines how you get that permit, you’re done. That’s real jeopardy.
Second, you can overturn anything up to the final permit. So if there’s a lease along the way, the next administration can overturn that.
But if you’ve done everything right — and you get your final permit to actually construct — you should be able to take that to the bank. In what world can you do everything right and then you get a legal right to proceed, and anybody, for politics, can pull that out? I know that some in the environmental space think that it should be that way, and we should be able to ping-pong back and forth between Trump and Biden. My goal here is to take the politics out of permitting. So if you do everything right — by the book and by the law — at the end of the day, if you get your permit, you can actually take that to the bank.
One of the big arguments for this bill was this permitting certainty provision. Ending the back-and-forth, and making it so a future president couldn’t do what Trump has done to wind energy. It’s been interesting watching the politics of this bill develop, though, because what’s become clear is — as you just hinted — not everyone actually wants permitting certainty.
No, and it cuts both ways. That is both a positive, depending on your perspective … and if your business model is litigating projects, it’s going to be harder. You can still litigate, but you can’t wait six years to do it.
I have heard folks say, ‘Look, it’s a big bill. It’s 400-something pages. It makes changes to NEPA and the National Historic Preservation Act. It makes changes to the Clean Water Act. The Supreme Court is controlled by conservatives at the moment, and they have been willing to improvise with big new doctrines such as the major questions doctrine. How can we be sure — and how can you be sure — that you’re not writing traps into these laws that courts will come along and use in the future?’ Republican judges may not agree with your aims, but they’ll be able to say, ‘Look at this recent and specific law, it lets presidents do X.’
We need to be able to legislate. I think the more we actually assert our political potential and mandate in legislation, the more we take power from the Supreme Court and from the judiciary in general. I think we need to be very careful and specific about our language. But the more you can’t get things done in Congress, the more power just sort of shifts over to the judiciary and to the administration. We need to claw that back, and we need to show that America can do stuff, that we can build big things again.
And to the extent that we’re not willing to do that, that power is going to shift to other places, and I’m not comfortable with that. I don’t think that’s good for democracy. I don’t think it’s good for our country. I don’t think it’s good for building things. We need to get [a project] to yes, or if it’s going to fail, if it’s a bad project, fail fast. Move on and to the right. This is not about greenlighting bad projects. It’s honestly about getting the projects into the right places.
What’s something you’re excited about in the bill that you feel like hasn’t been discovered yet?
Virtual power plants. I mean, I hate the term “virtual power plants” because they’re not virtual; they’re real. If you’ve got a gigawatt that you can you can contract with someone to say, ‘Hey, when I need this power, it’s there,’ and they can produce on that based on whether they like turn off half the lights in in a Walmart, or tap into the batteries in a bunch of electric vehicles, that is real power, and it has enormous value to the grid.
I know how conservative utility culture is, because I grew up in utility culture. I saw it every day in those conversations with my dad around the dinner table — but that is real demonstrable technology that we all know works at this point, and yet most of the utilities in the country have not embraced it. So if we get this done, we’ll be able to respond to the wholesale markets and [they] can’t be blocked, that’s a huge change.
One of the interesting things about this midterm is that almost all the incoming Democrats, I think certainly in the Senate, have pledged to restore the solar and wind tax credits. Have you done any work on what this bill would mean if those tax credits were back on the books?
I think we need to have a really robust discussion around that. I say that from the point of view that, we don’t have the [tax credits] right now, and yet we have tons of viable projects in wind and solar. So what that says to me is, maybe that money is more valuable someplace else.
We’re doing a really good job in this country of decarbonizing the electric generation sector with wind, solar, and batteries. I think we’ve won that battle, and if we have a level playing field, which is what this bill is all about, we’re going to decarbonize the power sector. We have not decarbonized the transportation sector. We have not decarbonized the industrial sector, which is dependent on, in many cases, chemical processes.
The question for me is not, do I want the wind sector, or the solar sector to move faster? I think if we get out of the way, they’ll move faster. The question is, would those dollars be more valuable in another sector of the economy?
Because when I look around back home, we are in the new normal. We’re in the part of climate change that I didn’t think would happen in my lifetime. In New Mexico, we’ve been the driest we’ve ever been in 1,200 years. And then once El Niño kicks in, we’ve had two of the word floods in recorded history in the last month. That’s where we are today. That’s what our grandkids are going to know for their entire lives. We’ve got to solve for that, and limit the worst cases of that, and we’re not going to do it by doing the least effective, least efficient thing. We have to invest in the places that make the biggest differences.
Senator Merkley voted no yesterday, as you know, and in his statement he said that the bill is very interesting, we should pick it up next year in the new Congress.
How many times has that worked?
I think one argument has been —
I’ve seen that over and over again. I’ve been here since 2008. How many years is that? Almost 20 years. When is that a real thing?
We should do a lot more in the next Congress. Let’s do that. Let’s get this as the floor, and then let’s raise the floor everywhere we possibly can.
And you don’t think passing this now will exhaust the president’s willingness to work on permitting reform?
I will take a win with the president wherever I can get one because it is fleeting, and he is what he is. He did not help last night. My phone blew up. The White House was like, you know, ‘Sorry, he just says stuff.’
[laughter in the room]
We have an alignment right now — the House, the Senate, and the White House — that has real value to making energy cheaper and putting more clean energy online. We should just take that because it also creates uncertainty for other folks. When we have that opportunity, don’t kick it to the curb. It is what it is.
Do you think the president needs to approve these projects for the bill to make sense?
No, because I think the greatest value is for the next president. But we are seeing real progress on real projects right now. We have seen dozens of projects approved that were stalled out. We’re having constructive conversations about many additional projects. That has its own value, but the value of this bill, in my view, is for the next president of the United States — whoever they are — and I will do everything in my power to make sure that that’s a Democrat — but if it’s not, they still need to be able to govern and compete with the rest of the world, and so the value is really for the country and the next president.
Give us a sense of what the amendment process will look like.
I don’t know what the amendment process is going to look like because that typically gets negotiated between the majority and the minority leaders. My view is that amendments are helpful. I think we’ve gotten away from amendment processes in the Senate, and that has not served legislation well. So I’m perfectly comfortable. I’ve told a number of members who want amendments that I’m supportive of them getting those amendments, because I think it lets people make their case about what they care about, and that creates buy-in for eventual legislation. And whether we win over those members or not, I think it has value.
The downside is we let things hang out there at a time when much of the conversation is still governed by these social media algorithms. But I still think it’s the right thing to do.
What does the path in the House look like, as you’re thinking about it today?
In the House, it’s the coalition of, one, the White House actually wants this, and they’re communicating with Republicans in the House, many of which won’t be there next year. So, like, go out on a win. Then on the Democratic side, you have the New Dems and the Problem Solvers Caucus and the Blue Dogs, and like, We’re not going to get all of the Democrats, but we’re going to get enough of the Democrats who believe in governing and who want the lessons of this election cycle to actually be manifest in law. I think we very much have a viable path in the House of Representatives.


 The 1983 construction of the existing CANDUs at Darlington. Photo: David Cooper/Toronto Star via Getty Images