You’re out of free articles.
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
Dozens of people are reporting problems claiming the subsidy — and it’s not even Trump’s fault.

Eric Walker, of Zanesville, Ohio, bought a Ford F-150 Lightning in March of last year. Ironically, Walker designs and manufactures bearings for internal combustion engines for a living. But he drives 70 miles to and from his job, and he was thrilled not to have to pay for gas anymore. “I love it so much. I honestly don’t think I could ever go back to a non-EV,” he told me. “It’s just more fun, more punchy.”
But although he’s saving on gas, Walker recently learned he’d made a major, expensive mistake at the dealership when he bought the truck. The F-150 Lightning qualified for a federal tax credit of $7,500 in 2024. Walker was income-eligible and planned to claim it when he filed his taxes. But his dealership never reported the sale to the Internal Revenue Service, and at the time, Walker had no idea this was required. When he went to submit his tax return recently, it was rejected. Now, it may be too late.
Walker is not alone. Dozens of users on Reddit have been sharing near-identical stories as tax season has gotten underway — and it’s only early February. It is unclear exactly how many EV buyers are affected. What we do know is that it will be up to the Trump administration’s Treasury Department to decide whether any of them will get the refund they were counting on — the same administration that wants to kill the tax credit altogether.
The problem dates back to a change in the process for claiming the tax credit. For the 2023 tax year, dealers had until January 15, 2024 to report eligible EV sales to the IRS. For 2024, however, the IRS introduced a new, digital reporting system and new deadlines. Starting in January 2024, if a customer bought an eligible vehicle and wanted to claim the tax credit, dealerships were required to file a report within three days of the time of sale to the IRS through a web portal called Energy Credits Online.
This change coincided with another: Buyers now had the option to transfer the credit to their dealership instead of claiming it themselves. The dealer could then take the value of the credit off the price of the car and get reimbursed by the IRS. This was voluntary on the dealerships’ part, and many opted in. By October, more than 300,000 EV sales had used this transfer option, according to the Treasury Department. But apparently there were also many dealers who didn’t want to bother with it. And at least some of them never bothered to learn about the online portal at all.
Get the best of Heatmap in your inbox daily.
Charlie Gerk, an engineer living in the suburbs of Minneapolis, bought a Chrysler Pacifica plug-in electric hybrid in February after his wife had twins. Unlike Walker, Gerk knew all about the workings of the tax credit, and he wanted to get his discount up front. But the dealership he was working with — a smaller, family-run business — had not gotten set up to do it. “He’s like, ‘We sell six EVs a year, we’re not going to take the time to sign up for that program,’” Gerk recalled the salesman saying. Gerk decided to claim the tax credit himself, and the dealership even gave him a few hundred bucks off the car since he’d have to wait a year to see the refund. He then emailed the dealership instructions from the IRS for reporting the sale through the online portal, and the dealership assured him it would submit the information. It sent Gerk a copy of form 15400, an IRS “Clean Vehicle Seller Report,” for him to keep for his records — except that the form was dated 2023. When Gerk inquired about it, the finance manager told him it was just because it was still so early in the year, and that they would make sure it got filed appropriately online.
Fast forward to one year later, and Gerk came across a post in the Pacifica Reddit forum from someone whose claim was rejected by the IRS because their dealer failed to report the sale. “I logged into my online dashboard for the IRS, and sure enough, the vehicle’s not there,” Gerk told me. “If it was filed appropriately, it would have shown on my online dashboard that I had an EV clean vehicle credit for 2024, and it’s not there.”
Gerk spoke to his dealership, which said it would look into the situation. He forwarded me an email exchange between the IRS and his dealership in which a representative from the IRS’ Clean Vehicle Team said it was probably too late to fix. “The open period for any unsubmitted time of sale reports is closed,” the staffer wrote. “We are expecting some Energy Credit Online (ECO) updates so contact us via secure messaging in the Spring for additional information.”
Some users on Reddit who, like Gerk, were aware of the reporting requirements when they bought their EVs, have shared stories about visiting more than a dozen dealerships before finding one that was registered with ECO and willing to file the paperwork. Others who didn't know about the rules have recalled inquiring about the tax credit at their dealership and being told they could simply claim it on their taxes. They only found out when they tried to submit their tax paperwork on TurboTax or another e-filing system and received an error message informing them that their vehicle is not registered in the IRS database.
Some blame the dealerships for misleading them and are wondering if they have grounds to sue. Others blame the IRS for not adequately informing customers or dealers about the rules.
“My frustration lies with the fact the IRS would even allow this to be an option,” Gerk told me. “If you’re going to allow the credit to be taken by me, I have to be dependent on my dealer doing the right thing?” (Gerk asked that we not share the name of his dealership.)
I spoke with a former Treasury staffer who worked on the program, who told me that the agency went to great lengths to educate dealerships about the new online portal and filing requirements, including hosting webinars that reached more than 10,000 dealerships and a presentation at the National Automobile Dealership Association’s annual convention in Las Vegas. The agency put up pages of fact sheets, checklists, and other materials for dealers and consumers on the IRS website, they said. But the IRS doesn’t have a marketing budget, and also relied heavily on NADA, the Dealership Association, for help getting the word out.
NADA did not respond to multiple emails and phone calls asking for comment. I also contacted several of the dealerships who sold EVs to buyers who are now having their tax credit claims rejected, none of which got back to me.
Many of the affected buyers are trying to get their dealerships to contact the IRS and see if they can retroactively report the sales, as Gerk did. Some are having more luck than others. When Walker contacted his dealership in Cleveland, Ohio, to see if there was anything it could do to help him, it still seemed to have no idea what he was talking about. Walker forwarded me a response from his dealership asking him if he had spoken to his accountant. “My sales desk is pretty insistent on that this is something your accountant would handle,” it said. (Walker did not want to disclose the name of his dealership as he is still trying to work with them on a solution.)
I reached out to the Treasury Department with a list of questions, including whether this issue was on its radar and what consumers who find themselves in this situation should do. The agency confirmed receipt of the request, but had not gotten back to me by press time. We will update this story if they do. There are reports on Reddit of EV buyers having a similar issue claiming the tax credit in 2024 for purchases made in 2023. Some filed their taxes without the EV credit and then submitted appeals to the IRS after the fact, with seemingly some success.
Buyers stuck in this situation have few other places to turn. Some Reddit users have posted about reaching out to their representatives, who offered to contact the IRS on their behalf. One challenge, as noted by the former Treasury staffer I spoke with, is that unlike the dealers, who have NADA, there is no consumer advocacy group for electric vehicle buyers who can engage with lawmakers and the Treasury and request a solution.
“I don’t necessarily need the money,” Walker told me. “It was just gonna go towards some more student loans — I’m just trying to pay down all of my debt as soon as possible. So I didn’t need it. But it would have been certainly something nice to have.”

This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
The “35x35” electrification pledge and an AI pledge are on the table.
World leaders are flocking to the Mediterranean resort town of Antalya, Turkey, this weekend for the 31st United Nations Climate Change Conference, also known as COP31. The U.S., of course, will once again not attend, as President Trump not only withdrew the country from the Paris Agreement but also from the United Nations Framework Convention on Climate Change, the umbrella group that organizes the annual conferences. Still, 194 other governments will be there, putting their heads together on how to move another few inches toward a safer future.
This year, as with the last several convenings, the meeting arrives against a backdrop of geopolitical instability, worsening climate impacts, and growing concern about energy security and affordability. While conflicts like the Iran war in some ways bolster the case for the energy transition by surfacing the risks of fossil fuel dependence, prioritizing energy security can manifest as countries turning inward and showing less willingness to work for the global good.
Perhaps the biggest item on this year’s agenda is the “35x35” pledge, Turkey’s proposal to electrify 35% of the world’s final energy use by 2035, up from about 23% today. That would mean switching from gas-powered cars to electric vehicles and from burning fuels for heat to electric heat pumps. It would not necessarily mean generating all of the electricity to power those devices from clean sources, although countries have committed to triple renewable energy capacity during previous COPs. Turkey itself does not have a plan to phase out fossil fuels, and its use of coal and natural gas-fired power plants has been growing alongside renewables.
It’s not yet clear whether Turkey will encourage countries to sign onto the pledge outside of the main negotiations or try to get it into the final decision text of the conference. In a twist, the conference has two countries sharing the presidency this year, with Turkey playing host and overseeing the “action agenda” — the announcements, commitments, and dealmaking that happen outside the official negotiations — and its co-chair, Australia, mediating the formal talks.
In addition to the electrification goal, Turkey is also inviting countries to sign an artificial intelligence pledge declaring a “shared ambition to make AI part of the climate solution — sustainably powered, efficiently designed, transparently measured and available to all.” The pledge has no teeth, however, as it explicitly states that it creates “no new obligations” and notes that it should be implemented according to national priorities and circumstances.
Although there will be no big agreement like there was in Paris in 2015, the two weeks of talks will end, per usual, with a consensus document that summarizes the outcomes of the negotiations. The final text from last year’s conference in Belém, Brazil, set a new goal to triple finance for climate adaptation by 2035. Countries also agreed to create a “Just Transition Mechanism,” a program to help fossil fuel-based economies navigate the socioeconomic consequences of shifting to clean energy. But the final text at COP30 did not ultimately mention the creation of a roadmap to transition away from fossil fuels, despite more than 80 countries supporting the idea, and didn’t, in fact, mention “fossil fuels” at all.
Much of the work this year will be about building on those outcomes. The climate adaptation finance goal, for example, is still fuzzy, as the parties did not agree on a baseline year from which to triple the funding, or define what types of finance count toward the goal, meaning it’s unclear what the actual target amount for 2035 is. The Just Transition Mechanism is similarly skeletal — negotiators will need to hammer out how to operationalize it into something useful. Countries are also supposed to make progress on the Global Goal on Adaptation, an as-yet ill-defined goal first established in the Paris Agreement that negotiators are still working out how to implement.
Then there’s the overarching theme of finance. As I’ve written in the past, every annual climate conference is ultimately a fight over money — specifically how much developed countries are sending to developing countries to help them fight climate change and respond to its effects.
To date, countries have agreed to mobilize $1.3 trillion annually in climate finance from all sources for developing countries by 2035, with $300 specifically coming from developed countries. Climate finance reached record levels in 2024, the most recent year with comprehensive data, with total global flows hitting $2 trillion and funding from developed to developing countries reaching $136.7 billion.
But progress is uneven. Only 2% of global investment in renewable energy over the past two decades went to Africa, said Brian Mukhaya, a senior manager on the Clean Air Task Force’s Africa team, during a recent media briefing. Finance challenges may also collide with the conference’s electrification goal. More than 550 million people in sub-Saharan Africa lack access to electricity, Mukhaya said, and the continent will need seven to eight times current investment levels to achieve universal electricity access by 2030. Also, while the rising cost of capital is becoming an impediment to building clean energy projects everywhere in the world, the problem is acute in Africa, where the average cost of capital for power-sector investments is three to five times higher than in Europe and North America.
At COP31, negotiators will try to make progress on questions such as what form climate finance should take (grants, concessional loans, private finance, etc), how it can be more effectively distributed, and what it should be used for.
Another question hanging over this year’s conference is whether the final text will acknowledge the likelihood of surpassing 1.5 degrees Celsius of warming above pre-industrial levels, the more ambitious target laid out in the Paris Agreement. Last year’s decision text contained a tacit admission, with countries resolving to limit “the magnitude and duration of any temperature overshoot.” Doing so requires a more serious discussion of carbon removal strategies than delegates have engaged in to date.
With the world seemingly careening past the 1.5 degrees target, the annual climate talks have lost some of their luster. Critics increasingly call for a new approach. Ani Dasgupta, the president and CEO of the World Resources Institute, for example, wants the COPs to center more on accountability and holding countries to their commitments. He also recommends developing a new decision-making process that does not allow a handful of countries to block decisions. Since the substance of the negotiations is becoming more and more about how to finance the transition, he argues the conference should also broaden its tent to bring in finance ministers and central banks.
“Where we are today is different from 1992 when COPs were set up,” he said during a recent press call. “The world is different. The broader needs are different. We are at a different place in the transition. And we actually haven't reformed the system.”
Progressive candidate Jane Kim declared victory in the race for California Insurance Commissioner.
Few political wonks outside of California were likely paying much attention to the Golden State on Tuesday night, as Democrats’ anticipated blue wave crested. But the state did have one close, consequential race on the ballot: insurance commissioner. On Friday, Bernie Sanders-endorsed progressive Jane Kim won the race to lead the California Department of Insurance, which oversees the state’s $452 billion insurance market.
Kim declared victory over the more moderate State Senator Ben Allen, who was backed by the California Democratic Party, after reaching a nearly six-point lead on Friday. In a brief speech before supporters, Kim said Allen called to congratulate her that morning. (A spokesman for the Allen campaign confirmed the call to The Orange County Register.) Kim ran on a proposal for a state-run, single-payer insurance program that would cover homeowners against wildfire damage — though the plan would ultimately need approval from both the California legislature and Governor-elect Xavier Becerra.
The idea is that homeowners would automatically receive public coverage for wildfire-related losses, with payouts capped at roughly what it costs to rebuild a typical California home. Policyholders would keep their regular private insurance for other risks such as theft, burst pipes, or an ordinary kitchen fire. Kim says Californians wouldn’t pay more overall, since the money for the program would come from the share of premiums that already goes toward wildfire coverage, though each household’s bill would partly depend on its own wildfire risk.
“It would be nonprofit, and so any excess capital would stay in the state of California and would be used to drive down risk,” Kim told my colleague Matthew Zeitlin a few weeks ago. “That’s the most important piece about this actually, is that it would create another revenue stream for mitigation.”
The insurance commissioner job has taken on an increasing sense of urgency as wildfires — intensified by climate change — continue ripping through communities in California. Mounting losses from hotter, drier conditions combined with decades of new construction in the wildland-urban interface have squeezed insurers’ profits, leading many to drop policyholders in high-risk areas or simply stop writing new policies in the state altogether.
California’s homeowners insurance premiums climbed 84% between December 2020 and March of this year, according to Stanford researchers. Meanwhile, a growing number of residents have been pushed onto the state’s FAIR Plan, which my colleague Matthew described as “the barebones insurer of last resort.” The share of California’s single-family homes covered by the plan has nearly tripled over that same period, from under 2% to about 5%, as homeowners in even low- and moderate-risk wildfire areas increasingly find themselves with few alternatives.
The insurance crunch has become yet another front in California’s broader affordability crisis, alongside persistently high housing, electricity, and gasoline costs. Kim’s victory suggests frustrated voters are increasingly willing to support more radical solutions that once seemed politically out of reach. And while Kim doesn’t have a background in the insurance industry, she’s no stranger to public office. The former civil rights attorney served on the San Francisco Board of Supervisors from 2011 to 2019 before becoming a regional director for Sanders’ 2020 presidential campaign.
But throughout her run for the Insurance office, critics have continually questioned how, exactly, her plan would work. No state has attempted a public disaster insurance program like this before; critics argue there’s no relevant model to work off of, no white paper laying out the details, and no price tag attached to the idea. Kim herself acknowledges that there’s plenty of uncertainty surrounding the plan. “This is a concept and a proposal, and could look quite different by the time it works its way through the process,” she told Matthew. In other words, the program that eventually emerges from negotiations with lawmakers — if one does — could end up looking considerably different from what Kim campaigned on.
Her opponent, Allen, who chairs the state senate’s Energy, Utilities and Communications Committee, argued that creating a public wildfire insurance program would impose a significant financial burden on the state. The California Earthquake Authority, an agency that sells earthquake insurance and administers the state’s Wildfire Fund, examined the potential costs of such a program this spring, estimating it would require roughly $25 billion upfront to have a 75% chance of staying solvent for 20 years. But Kim points out in her policy brief that buying reinsurance — essentially insurance for the insurer — could cut that to about $6 billion.
Allen, on the other hand, pitched a series of reforms to the existing market, including speeding up rate reviews, rewarding homeowners and communities for wildfire mitigation, expanding financing for home-hardening projects, and discouraging development in high-risk areas.
Voters opted instead for the insurance revolution. But Kim argues that her plan isn’t totally without precedent. On the campaign trail, she frequently pointed to New Zealand, where the government’s Natural Hazards Commission provides homeowners with public coverage for disasters including earthquakes, landslides, volcanic eruptions, and tsunamis — though notably not ordinary wildfires. And while France and Spain also operate state-backed disaster insurance programs, these don’t cover wildfires either, a far more common occurrence in California than the comparably rare disasters these programs were built around abroad.
Ultimately, Kim’s ambitious plan will require a champion in the legislature to go anywhere. But in the meantime, there are other issues she could get to work on. On the campaign trail, she said she wants to push insurers to fund a disaster mitigation program run by the Department of Insurance, require companies selling auto policies in a region to also offer homeowners coverage there, and impose minimum loss ratios compelling home insurers to pay at least 65% of premiums in claims and auto insurers at least 70%. It’s unclear, however, whether Kim can implement either of the latter two proposals without new legislation.
Kim will also immediately face the question of what to do with outgoing Insurance Commissioner Ricardo Lara’s Sustainable Insurance Strategy reform package. Designed to entice insurers back to California, these new rules allow companies to set premiums using forward-looking risk models rather than relying on historical losses, and to pass a portion of their rising reinsurance costs onto policyholders. In exchange, insurers are required to write more policies in wildfire-prone areas.
Kim has criticized this approach, arguing that insurers have exploited loopholes to raise premiums on lower-risk customers while continuing to underserve high-risk communities, all without doing enough to address the underlying factors driving wildfire risk.
That leaves Kim in a tricky situation. Until she is able to secure legislative backing for some version of her proposed public insurance program, she’ll have to decide whether to scrap or simply build on the existing reforms. She hasn’t yet laid out any plan for doing so. But whatever direction she takes could ultimately reshape California’s insurance market well before a new state insurer gets off the ground.
They only ticked up by 5% this week.
Beyond the repudiation of Donald Trump, if there was one message voters sent on election night, it was that they really don’t like data centers.
Democrats who ran against rampant data center development won at both the gubernatorial level (Amy Acton in Ohio, Gina Hinojosa in Texas) and the senatorial level (Abdul El-Sayed in Michigan, Annie Andrews in South Carolina). The Wall Street Journal counted 125 Democrats nationwide who “targeted their opponents over data centers.”
“Data centers are the midterms’ other big loser,” according to Politico. “The Results Are In: Voters Hate Data Centers,” from Wired.
Commentators didn’t just notice that many anti-data-center candidates won, but that a number of local data center moratoria passed as well. “In nearly every case, it’'s about 67-80% opposing data centers. True in California, Ohio, everywhere,” Brad Carson, head of the artificial intelligence policy group Americans for Responsible Innovation tweeted. Added Democratic strategist David Shor on X, “Voters sided against data centers in 40 of 41 ballot measures, with basically no correlation to how red a county was.”
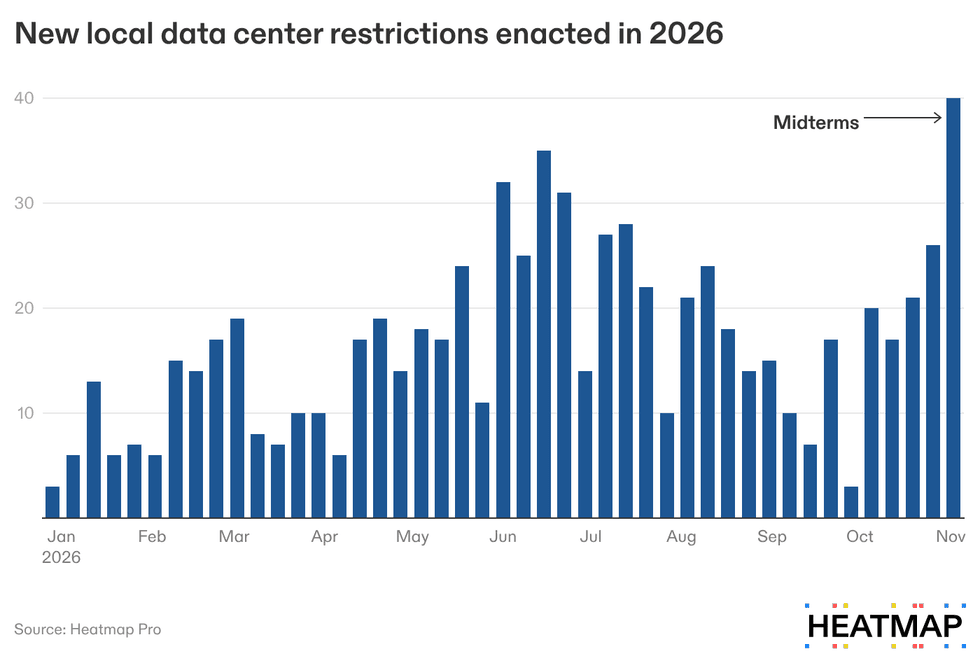
But as far as new legislation and ordinances go, November 3 was just another Tuesday in the long-running local campaign against data center development, Heatmap Pro data shows.
“Forty is a lot in one day,” Owen Curtin, a data analyst with our intelligence platform Heatmap Pro, admitted, but “in terms of the rate at which county governments are enacting legislation and the overwhelming public support for them, it’s not new.”
There have been over 830 restrictive measures passed this year, according to analysis from Heatmap Pro, which breaks down to just over 80 per month. The numbers picked up substantially in the summer and fall.

June 15 to 21 was the busiest week of the year for passing data center laws, at 35, and June the month with the most laws passed overall, with 133. Another95 restrictive laws were passed in July, followed by 86 in October.
Of the 40 ballot measures passed this week, only one applied at the county level (Morgan County, Illinois), where a great deal of data center permitting occurs. “While many municipalities permit data centers, a significant portion are permitted by county governments. Not all counties have the legal authority to pursue ballot measures, which is why most November 2 measures were at the municipal level,” Curtin explained.
“While the overwhelming support for local data center ballot measures is indicative of public sentiment (largely anti-data center), it doesn’t necessarily correlate with the regulatory landscape,” he went on. And here’s a fun fact: “There are over 19,000 municipalities in the U.S., so 40 bans are only 0.2% of all municipalities,” Curtain added. “If 40 municipalities banned data centers every day, it would take 475 days to ban data centers across the entire U.S.”