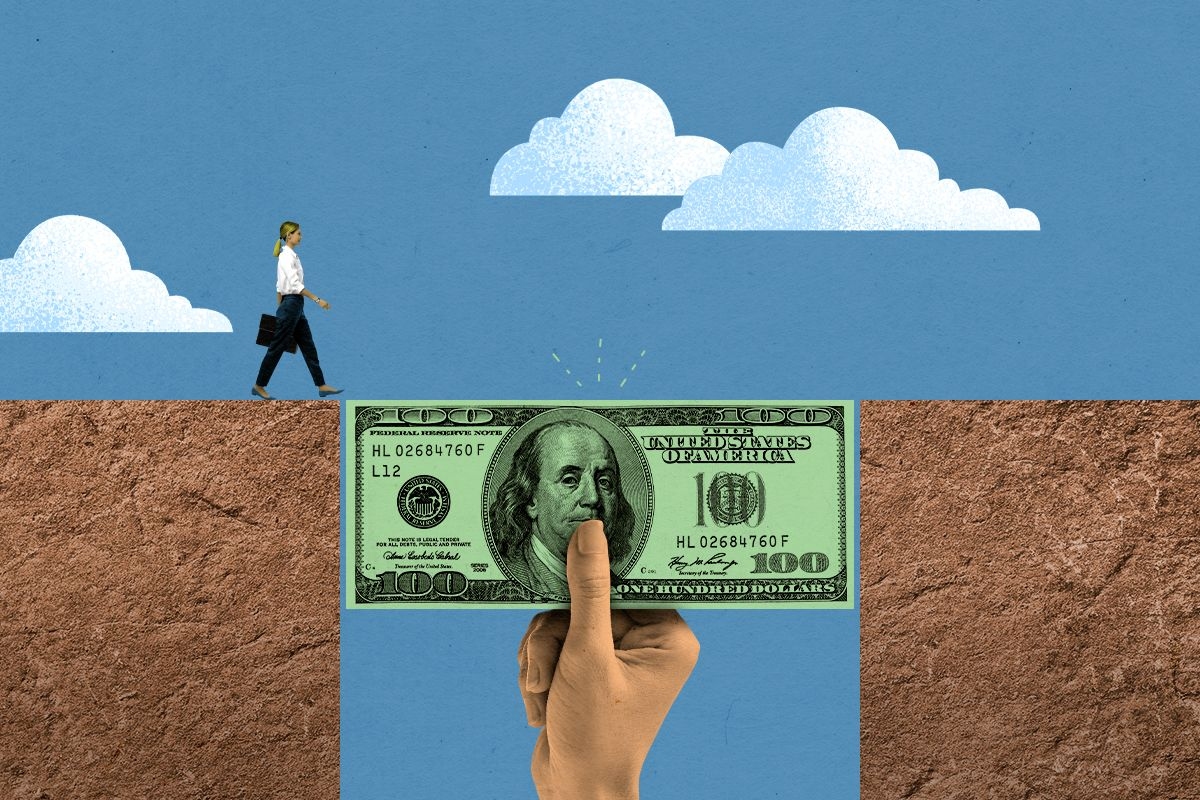
Sometimes it’s called the “missing middle,” sometimes, more ominously, the “valley of death.” Whatever the terminology, it’s undeniable that a chasm lies between a climate company’s early funding rounds and its eventual commercial scale-up, one that’s getting harder and harder to bridge. From the first half of last year to the first half of this one, total Series B funding declined by nearly a quarter; beyond Series C rounds — what the market intelligence platform CTVC calls “growth funding” — it declined by a third.
“The capital needs of these businesses have just outgrown their early stage backers,” Frank O’Sullivan, a managing director for S2G Ventures’ energy investments, told me. “But the infrastructure investors have absolutely no appetite whatsoever for taking on an unproven technology and scaling.” S2G makes both early stage and growth stage investments, and O’Sullivan co-authored a white paper last year on the problem of the “missing middle.” The paper found that of the $270 billion in private capital for clean energy raised between 2017 and 2022, just 20% was allocated to late-stage and growth-focused investments, while 43% went to earlier rounds and 37% toward deploying established tech.
Of course, some of climate tech’s funding gap can be attributed to broader trends in the venture market and economic landscape. Covid-related disruptions and low interest rates led investors to throw money at promising startups, only to see their valuations drop as inflation (with rising interest rates to match) and geopolitical uncertainty cooled down the overheated market. Other companies went directly onto the public market via special purpose acquisition companies, only to underperform expectations. “There is capital to be deployed,” O’Sullivan told me. “But a lot of the companies that need that capital are struggling, really, to swallow hard and take significant restructuring of their previous valuations.”
With clean tech in particular, there’s also frequently a mismatch between the abilities of venture firms, which often make their biggest returns on software startups, and the demands of climate tech. The latter tends to require huge investments in physical infrastructure and support for first-of-a-kind projects, and generally has a longer timeline to profitability than, say, an app. “Venture funding, in some sense, was built for scaling software companies,” Lara Pierpoint, managing director of the new catalytic capital program Trellis Climate, told me. “You’re talking about a capital light business that generally is creating something that enters a white space, and for which there’s huge amounts of market potential.”
It’s much more difficult to build expensive infrastructure that aims to displace fossil fuel facilities and the entire economy that relies on the cheap, reliable power they provide. So while VCs may be enthusiastic about taking a relatively small financial bet on a high-potential early-stage company, that may be all they’re able to do.
Trellis, on the other hand, is a part of the climate nonprofit Prime Coalition and funds first-of-a-kind climate projects with philanthropic capital. The nonprofit structure and philanthropy-focused funding model mean that Trellis can take a different tack on missing middle financing than traditional venture or equity investors. For example, Pierpoint told me it can choose whether to invest in a company or just a specific project. Trellis can also help de-risk projects by providing an “insurance backstop” — basically backup capital in case primary project funding falls short. “We’re looking at expanding the kinds of resources and dollars we can bring to the table in general for the ecosystem, because we think that venture can’t do this alone,” Pierpoint told me.
As with all nonprofits, generating big returns isn’t the focus for Trellis. But for traditional investors, that’s the primary goal. And while growth investments in more technically mature solutions are likely to generate consistent returns, O’Sullivan told me they don’t often provide the rarer but more alluring 10x returns that make early-stage venture capital particularly enticing. “So it’s a more balanced portfolio, typically, in that growth equity category. It’s just that you don’t see the high highs,” he said, explaining that a two to 3x return on investments is more realistic.
Brook Porter, a partner and co-founder at the growth-stage firm G2 Venture Partners, told me that focusing on the missing middle can be extremely profitable, though, and that the key to making real money is correctly identifying a company’s “inflection point” — that is, when it’s poised for significant growth and impact. That is, of course, every investor’s dream. But G2’s whole strategy revolves around identifying exactly when this critical juncture will be, tracking more than 2,000 companies per year to identify the ones best poised for breakout scale-up.
The firm spun off in 2016 from Kleiner Perkins’ Green Growth Fund, where Porter and his three co-founders previously worked as senior partners. This is where they honed their theory of inflection point investing, funding companies such as Uber, drone-maker DJI, and Enphase Energy. Porter told me that helping startups move from proof-of-concept to building “that machine of a business” requires a lot of hand-holding, and that “there aren’t as many investors with that skill set,” so it could take a while for this approach to scale.
On the other end of the funding spectrum, large institutional investors like banks, hedge funds, and asset management firms certainly have the money to help bridge the missing middle, but O’Sullivan and Pierpoint told me they’re generally more interested in fulfilling their internal climate mandates by building out more wind and solar, which generates near-guaranteed returns. These investment giants then look at their remaining cash and think, “Well, we should do something more avant garde. Let’s put money into early-stage venture,” O’Sullivan explained. That’s how many seed and Series A-focused funds raise money.
As O’Sullivan sees it, what’s happening now is “a flaw of the structure of capital allocation at the very highest level.” He thinks we could start by reorienting incentives such that large investors such as banks, asset managers, and pension funds get paid in part for helping bring new climate solutions to market, as opposed to just funding the same old, same old. That would allow them to write “right-sized checks” on the order of $50 million to $100 million to ready-to-scale companies — larger than what a VC firm would write, but smaller than what the big infrastructure investors are used to.
How would those alternate funding models actually work? Well, that’s the real question. Pierpoint said she’s often asked whether a new kind of investor or asset class will be necessary to fill the gap, and while she doesn’t have an answer, what she does know is that the group of climate tech companies that’s ready to commercialize “can’t wait 15 years until we have the exact right form of capital.”
“There needs to be urgency on the part of philanthropists, on the part of infrastructure equity investors, on the part of venture capitalists, to really start showing that we can do this,” Pierpoint told me, “and that we can bring together the right capital stacks to make this happen.”


 Збогом! Pedja Milosavljevic / AFP via Getty Images