You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
Two U.S.-based companies are betting on lithium-sulfur to compete with China.

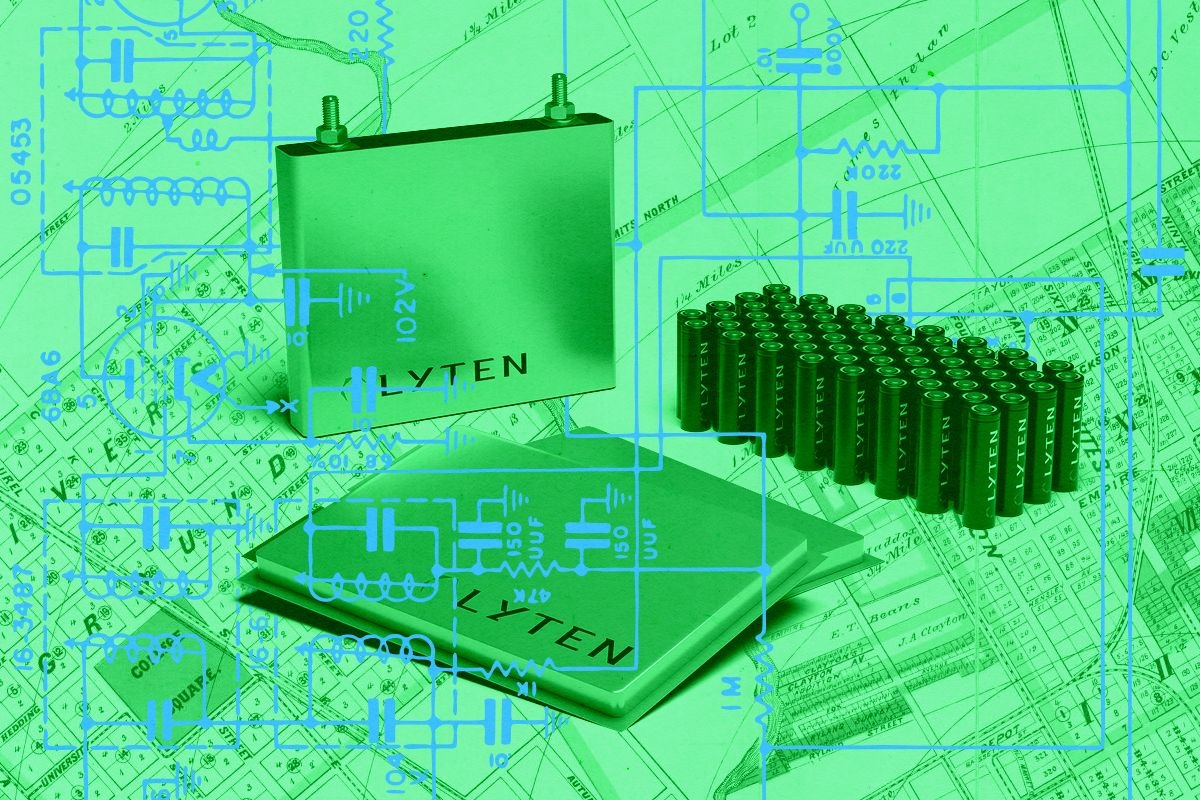
By the time the Swedish battery giant Northvolt declared bankruptcy last month, a well-funded U.S. startup, Lyten, had already swooped in to snatch up the company’s previously shuttered Bay Area factory. With China flooding the market with its cheap lithium-ion tech, Lyten is betting that creating a fully domestic battery supply chain will require alternate chemistries — like, say, lithium-sulfur, Lyten’s recipe of choice.
Lithium-sulfur has long been a promising contender, as in theory, these batteries can have a much higher energy density — the amount of energy that can be stored in a given space — than traditional lithium-ion. They also rely primarily on cheap, abundant, and easy to access materials. “We don’t use nickel, we don’t use manganese, we don’t use cobalt, we don’t use graphite,” Keith Norman, Lyten’s chief sustainability officer, told me — all markets where China plays a leading role. Scaling up standard lithium-ion battery production to meet forecasted global demand would require opening nearly 400 new mines by 2035, according to Benchmark Mineral Intelligence. “We believe if you could snap your fingers and change that to lithium-sulfur, that mining requirement will be reduced somewhere between 80% and 90%,” Norman said.
Lyten’s customers, Norman said, want these batteries as soon as possible, and acquiring Northvolt’s old 200-megawatt plant will allow the company to begin commercial production there next year. Lyten also recently announced plans for a Reno-based gigafactory, which is scheduled to come online in 2027. Zeta Energy, a Houston-based lithium-sulfur startup, also aims to commercialize in 2025, and is set to announce the opening of its 100-megawatt plant in the coming weeks.
While both companies have dreams of enabling more efficient, lightweight, and cost-effective electric vehicles and energy storage systems, there are reasons why lithium-sulfur has yet to be commercialized.
For one, sulfur is generally a poor conductor of lithium ions, and therefore requires extra conductive material to compensate, increasing the battery’s weight. Lithium-sulfur batteries also have notoriously short cycle lives due to the “polysulfide shuttle effect,” which causes the sulfur in the cathode to dissolve in the liquid electrolyte, damaging the anode and — you guessed it — decreasing the battery’s capacity and cycle life.
“It could be solved,” Arumugam Manthiram, an engineering professor and battery researcher at the University of Texas at Austin, told me. After being involved in the initial lithium-ion battery breakthroughs of the 1980s, Manthiram said he’s seen traditional battery tech continue to improve year after year. He thinks lithium-sulfur will follow the same trajectory, only quicker. “Can it be solved in five years, 10 years? I’m optimistic.” he told me. He’s currently working with Lyten on a Department of Energy-funded grant to accelerate the commercialization of lithium-sulfur batteries for use in EVs.
Zeta thinks it’s already found the ticket, though. It claims to offer three times the energy density of traditional lithium-ion at less than half the price. While Melissa Schilling, Zeta’s head of strategic marketing and innovation, couldn’t reveal much about Zeta’s proprietary cathode, she did tell me that it’s made of a sulfur-carbon polymer that eliminates the dreaded polysulfide shuttle effect (a claim that’s been externally verified) and allows for greater electrical conductivity. The company’s lithium-metal anode is made of carbon nanotubes, a.k.a. tiny cylinders composed of carbon atoms. The nanotubes help improve the anode’s stability, thus increasing energy density compared with traditional graphite anodes while also preventing the formation of dendrites, tiny projections on the anode that can cause the battery to break down.
Zeta’s batteries can go through about eight times more charge/discharge cycles than traditional lithium-sulfur batteries, according to the company’s figures and Manthiram’s estimation of a typical life cycle. Optimizing these batteries for EVs, though, will likely mean a much shorter cycle life, which may not be on par with what lithium-ion can do. Even so, Schilling told me, “what we’re going to beat lithium-ion on is density and cost.” The company has raised $30 million to date, and is in the midst of raising its Series B round. While Schilling couldn’t reveal the names of Zeta’s initial customers, she told me that the company is collaborating with a large automaker and heavy equipment manufacturer. Zeta has also received the same commercialization grant from the DOE as Lyten.
For its part, Lyten currently provides 25% greater energy density than top-of-the-line lithium-ion batteries, Norman told me. The company expects that soon, it will be able to offer twice the energy density at half the material cost. Lyten’s tech relies upon a so-called supermaterial, three-dimensional graphene, which it’s developing in-house. This gets combined with sulfur in the cathode to form a more conductive and stable composite material.
Norman said you can think of 3D graphene like a sponge with pore sizes “perfectly designed to hold sulfur atoms.” The graphene “gives [the sulfur] conductivity and gives it a rigid structure that doesn’t allow it to break down as easily,” he told me, meaning the battery is less likely to succumb to the polysulfide shuttle effect. Lyten’s anode is also made of energy dense lithium-metal.
Lyten hasn’t publicly revealed its battery’s cycle life, however, and in a follow-up email, Norman told me that when it comes to EV batteries, Lyten is “not yet at the cycle life we need,” though the company is “seeing 20-30% improvement in lithium-sulfur battery performance each year.” For customers using lithium-sulfur for earlier-stage applications such as drones, satellites, and two- and three-wheelers, Norman wrote that Lyten’s current cycle life “meets or very nearly meets their requirements.”
The company seems to have the money to work towards these improvements. Lyten achieved “unicorn” status last year, recording a valuation over $1 billion after closing a $200 million Series B round. It counts Stellantis and FedEx among its backers, and the Department of Defense is even funding a demonstration of Lyten’s battery tech aboard the International Space Station, where lithium-sulfur cells will be tested for use in everything from satellites to space suits.
Norman told me the company’s recent purchase of Northvolt’s old Bay Area facility represents an important step in Lyten’s path to scale. The California plant was originally designed to produce lithium-metal batteries for Cuberg, a startup Northvolt acquired in 2021 and closed down this summer. Like Lyten’s and Zeta’s, Cuberg’s batteries used a pure lithium-metal anode, while its cathode was the same old nickel-manganese-cobalt chemistry that conventional lithium-ion batteries use. With this kind of chemistry, Norman told me, it would be “very difficult to ever compete on costs.”
One of the main ways that Northvolt ultimately went wrong, Norman and Schilling agreed, is that it tried to scale standard lithium-ion tech too quickly in a price-sensitive environment. “They kind of went right to these 10, 20, 30 gigawatt-hour facilities,” Norman told me. “As they tried to scale those, they ran into a lot of manufacturing challenges and just the cost and time of trying to learn that on these huge facilities kind of bit them.” Schilling told me she thinks QuantumScape, a manufacturer of solid-state batteries for EVs, is running the same risk.
To compete with the low-cost Chinese batteries flooding the market, Norman told me domestic tech has to be demonstrably better — incremental improvements in efficiency, cost, or sustainability will not be enough. “Fundamentally, you’ve got to have a differentiated battery that customers are really dying to get their hands on,” Norman told me. But he knows that if Lyten successfully commercializes lithium-sulfur, other companies and countries will quickly get into the game.
After all, major battery giants such as LG, Samsung, SK, and Panasonic are well aware of what’s going on in the lithium-sulfur space, Manthiram told me, even if they’ve yet to make any noise about it. “They are quietly doing some work, R&D. They don’t hype it because they have a product already made,” Manthiram said, referring to the company’s widely available lithium-ion batteries. “They are also watching what academic labs are doing, what Lyten is doing, what others are doing.”
These behemoths are sure to pounce when and if the timing is right. Yet Lyten and Zeta still have the opportunity to pioneer a novel battery technology that can be fully made in America — something thus far unheard of in the battery universe.

Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Ben Allen wants to reform the existing market. Jane Kim wants a revolution.
From Crescent City to Coronado, California voters are facing decisions on a down-ballot strewn with over a dozen propositions and a series of statewide Democrat-versus-Republican races with mostly foregone conclusions.
And then there’s the insurance commissioner.
In the race to oversee California’s insurance market, a $452 billion-in-premium-volume monster imperiled by insurer defections and disaster risks, Democratic State Senator Ben Allen, whose district includes Pacific Palisades, is facing off against Jane Kim, a progressive former San Francisco supervisor.
Kim has the support of Vermont Senator Bernie Sanders — it’s the first thing you see about her when you Google her campaign. She previously served as his California political director during the 2020 presidential race, and she appeared earlier this month at an event with the senator in support of the state’s proposed billionaire wealth tax.
Allen, by contrast, won the endorsement of the state’s Democratic Party and its two incumbent senators.
There has been little public polling of the race, but one September survey showed Kim leading Allen 25% to 18%, with more than half the electorate undecided.
“My opponent and I are not even running for the same office,” Kim told me. “He’s running for what this office used to be, and I’m running for what this office could be.”
Allen wasn’t worried about Kim’s characterization in my interview with him, telling me, “I want to fix the market that we have and make it work. My opponent wants to build a new state insurer that nobody has priced.”
Nowhere are the stakes of insurance regulation higher than in California. On its own, the state’s insurance market would be the third largest in the world, according to the National Association of Insurance Commissioners. Homeowner insurance premiums have risen 84% from the end of 2020 to March 2026, according to research from Stanford’s Climate and Energy Policy Program. Several large insurers have either left the market entirely or stopped writing new policies.
California’s creaky and complex regulatory environment for insurers has combined with its famously flammable environment (all beset by a warming climate) to put regular policyholders at risk of losing their policies or bailing out those who can’t get covered. “Climate risks grow, and our mechanisms for dealing with it lag behind,” Matt Weiner, the chief executive of the wildfire policy group Megafire Action, told me. (Weiner said he was supporting Allen in his personal capacity).
Rates for homes insured by the FAIR Plan, the barebones insurer of last resort, have more than doubled from about 2% to 5% over that same period, with FAIR Plan coverage spreading from just high-risk areas to even areas with low and moderate wildfire risk. The plan required a $1 billion assessment from the state’s insurers in 2025 following major Southern California fires. “This trend is a symptom of many homeowners’ inability to secure insurance in the conventional market,” according to the Stanford researchers.
Allen seeks to make the insurance market work better, building on reforms implemented by current Insurance Commissioner Ricardo Lara. Allen described the reforms, which encourage insurers to write policies in high-risk areas and allow them to use forward-looking projections, as a “bit of a band-aid” that doesn’t “actually get to the core of the problem, which is making these communities less risky.”
Allen’s plan for the California insurance market involves both reviewing rate proposals more quickly, incorporating more data into those rates (which may push rates up, but also keep insurers in the market), and mobilizing the whole of government to invest in home hardening and resilience to lower risk and bring premiums down. Allen wants to, well, insure “that risk reduction is actually incentivized and rewarded by the insurance market,” he told me.
This would mean that “there will continue to be certain properties that are going to be so high risk that they really will and ought to be paying significantly more than everybody else,” he added.
When I asked him to elaborate on his vision for California’s insurance future, he told me, “My hope is that when a family and a neighborhood commit to hardening defensible space and community-scale mitigation, that should show up on the bill.”
Jane Kim, on the other hand, is interested in an insurance revolution, which would require — as her most famous supporter might put it — a political revolution as well. Her centerpiece proposal will be familiar from anyone who has followed Sanders’ career: a single-payer disaster insurer.
The plan, which she told me was a “concept and a proposal,” would be funded by a levy placed on insurers, and then a public insurer would invest in the market, buy reinsurance, and pay out claims. (Her opponents have criticized her for not being forthcoming enough with details). She says her plan would not be able to cover a Palisades- or Altadena-level fire in its first year, “but no insurance company can cover a catastrophe of that level.”
The nonprofit nature of the program, she adds, would let the state fund mitigation work directly. While such a program would require legislative action, “the great thing about campaigns is that this is trying to debate big ideas with voters,” Kim said.
In response, Allen cited a report from the California Earthquake Authority, which modeled a state disaster insurer (albeit not Kim’s plan specifically) could require $25 billion in capitalization. A more thinly capitalized insurer could mean $2,000 assessments on every policyholder in the state to cover an extreme wildfire disaster, the report said. “That’s the honest price of what she’s proposing,” Allen said.
“I also have a plan that’s actually grounded in reality and fixing the problems right now. It's not based on some pie-in-the-sky set of ideas that have no precedent, that have no real meat on the bones,” Allen told me.
One of Allen and Kim’s former opponents, Patrick Wolff, who fell short in the top-two primary election in June, told me that “the charitable interpretation of Kim’s platform is she does not think the current system can be made to work, and so she essentially wants to redesign and reimagine the entire system.” (Wolff has endorsed Allen). But, he added, “she’s coming at it from a set of solutions that were baked-in before she started, and then she's fitting [those] into her campaign.”
Moira Birss, a senior fellow at the Climate and Community Institute who said she had “provided input” to Kim’s campaign, but wasn’t speaking on its behalf, told me she “really recognizes that we are yet again in a situation where the private insurance market is not responding to a need that we as communities and as society have for this financial safety net of disaster insurance, and that we need a public approach.” She said the plan would build on lessons learned from New Zealand, which has public natural disaster insurance funded through a levy on fire insurance, and from the National Flood Insurance Program and the FAIR Plan.
Kim is happy to embrace the more ideologically charged vision of her campaign, telling me, “I am talking about transforming this office to be a place where we are leading on, and taking on, economic inequity, a wealth gap, and the climate crisis.
“I don’t even view my opponent as Ben Allen — I’m not running against Ben Allen,” she went on. “I’m running against the status quo.”
On Hungary’s Russian nuclear conundrum, why geothermal isn’t solar, and a funny use of gallium
Current conditions: An ill-timed and dense fog blanketed Toledo yesterday amid an industrial chemical leak, with the low-lying cloud acting to trap the toxic glycidyl methacrylate in the air, forcing an evacuation • Super Typhoon Champi has become the most powerful storm of 2026 as it roars westward across the Pacific to Taiwan, leaving a damaged Guam in its wake • After Polo, Simon, Rachel, and Trudy, yet another tropical depression capable of striking western Mexico as a major hurricane has formed in the eastern Pacific.
That’s the money quote Politico nabbed Wednesday from Senator Sheldon Whitehouse, the Rhode Island Democrat who helped broker the Senate’s grand compromise to ease federal permitting on energy projects. The statement came a day after the Department of Justice filed a petition to reopen the permits on New England Wind, the 2.6-gigawatt offshore wind project from Avangrid. Just over a week ago, the Trump administration restarted a legal fight with Orsted over Revolution Wind, which is already generating electricity off the coast of Rhode Island. At the time, some White House observers saw the effort as President Donald Trump’s hard-nosed negotiating, designed to pressure skeptical Democrats into voting for the legislation lest the administration continue going after projects that the bill, if passed, would protect. But Ira Joseph, a fellow at Columbia University’s Center on Global Energy Policy, saw the latest move as evidence Trump can’t control his impulse toward vendetta. “An inevitable turn. It’s always personal and never about what policy would either benefit or hurt the public,” he wrote in a post on X. “Wind will always be associated with harming the family business. It’s always a King Claudius situation and he or she who whispers last, whispers loudest.”

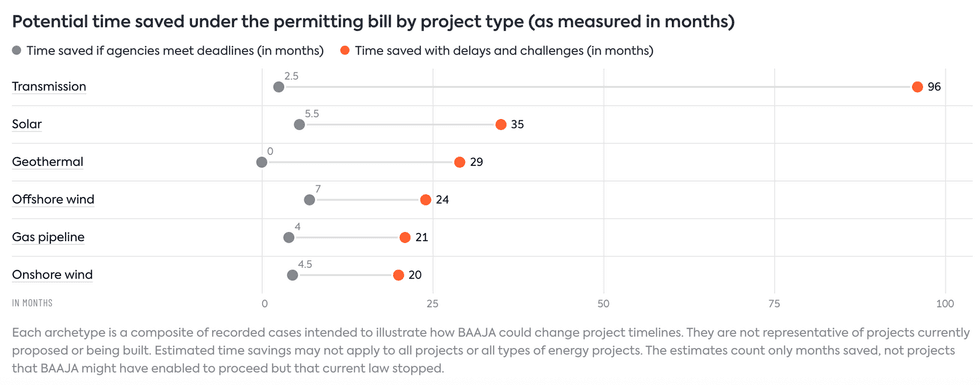
Joseph’s colleague at CGEP, Jack Andreasen Cavanaugh, is out with a new tool to estimate how much time the Bipartisan American Affordability and Jobs Act would save various kinds of clean energy projects. The results are pretty staggering. Transmission lines alone could save eight years by avoiding the delays and challenges opponents can currently lob against a project.
When the Department of Commerce enacted new trade restrictions on polysilicon in August, the agency gave the industry a 120-day head start to prepare for the policy to come into force. To prevent importers from stockpiling foreign solar panels and components, the Commerce Department promised to remain vigilant. The crackdown is underway. In a note to investors this week, Roth analyst Philip Shen said the agency has blocked roughly 60 importers over the past several weeks, including 10 just this past week. Prior to the Commerce Department’s Section 232 decision, the U.S. had roughly 200 approved importers bringing in solar panels.
The number of solar importers more than doubled over the past few months to more than 400 total. Roth’s memo highlighted speculation that the Commerce Department could dampen its 232 policy, giving utility-scale developers a carveout or delaying the implementation on December 3, when the 120-day waiting period ends. Shen said his sources “with direct access to the Commerce Department” say any such carveouts are “not being worked on” by the agency. A spokesperson for the Commerce Department did not respond to my email requesting comment last night.
In April, Hungarian opposition leader Péter Magyar defied the odds and ended nearly two decades of quasi-authoritarian rule by Prime Minister Viktor Orbán. Among the biggest differences between the two leaders is Magyar’s desire to realign Hungary, which had been Russia’s most reliable partner in the European Union, with Brussels. No one expects Budapest to wean off Russian gas any sooner than other addicted EU nations such as Austria and Italy. But the energy elephant in the room was the new Russian nuclear reactors Hungary was building. The Paks Nuclear Power Plant, Hungary’s only atomic station, generates roughly half the country’s electricity. Orbán had commissioned Rosatom, the Kremlin’s state-owned nuclear company, to expand the facility in 2014 without a competitive bidding process. On Wednesday, Reuters reported that Prime Minister Magyar is considering new vendors to replace Rosatom.
The U.S. could be a potential player in the mix. Over the past few years, Westinghouse, America’s nuclear champion, has started producing fuel assemblies for Russian-made VVER reactors in Bulgaria, Czechia, Finland, Slovakia, and Ukraine. Westinghouse is also making deals to build its AP1000 reactors across Eastern Europe, starting with Poland but ultimately expanding to at least Bulgaria and Ukraine. On Wednesday, the company announced a plan to invest $1 billion into expanding its fuel manufacturing into LEU+, a slightly more potent version of low-enriched uranium that Southern Company started experimenting with last year. “As we advance the next generation of fuel, we are positioned to create more value for our customers and unlock new nuclear generation to support the growing demand for baseload power,” Dan Sumner, Westinghouse’s chief executive, said in a statement.
Sign up to receive Heatmap AM in your inbox every morning:
In June, Google inked a deal with the virtual power plant provider Voltus to deliver 100 megawatts of flexible distributed power to PJM Interconnection, the electricity market covering the Mid-Atlantic and Midwest. On Thursday, the companies announced an expanded agreement to build a 1 gigawatt network of renewable and storage assets that can be tapped to balance out the nation’s second-largest and arguably most-stressed grid. The deal “represents one of the largest known distributed capacity portfolios deployed by a hyperscaler to date,” according to the companies’ press release. “Distributed energy resources are powerful tools for managing a modern, reliable grid while keeping energy affordable,” Ellen Zuckerman, Google’s head of energy market development for the Americas, said in a statement. “Expanding our initial commitment tenfold demonstrates our core effort to actively bring our own capacity to the grids that serve us.”
Meanwhile, General Motors led a $108 million Series B funding round for Peak Energy to help ramp up production of its sodium-ion batteries, Bloomberg reported Wednesday. That same day, Optivolt, a startup behind a device meant to make solar panels more efficient, raised $32 million in a Series A with backing from heavyweights in the solar industry, including former SunPower CEO Tom Werner and ex-Enphase CEO Paul Nahi.
Next-generation geothermal promises to generate 24/7 renewable power while tapping into the workforce and industrial knowhow the U.S. oil and gas industry built up during the fracking boom. But that won’t ever make geothermal wells as cheap as mass-manufactured solar panels — and the sector’s hypemen need to stop insinuating otherwise. That’s the take from Cindy Taff, the chief executive of the geothermal startup Sage Geosystems. In a Wednesday post on LinkedIn, the former Shell fracking executive, whose company is now a strong contender for the nation’s No. 2 next-generation startup behind fellow Houston-based Fervo Energy, accused rivals of telling “a compelling story” but not necessarily “an accurate one.” A solar panel made for Arizona “is fundamentally the same as those installed in Athens,” the Greek capital. But the unit in geothermal is a well, “and every well is drilled into rock with differing characteristics, temperature profiles, and operational challenges.” In other words: “We tell investors that geothermal will follow solar’s cost curve. I understand why the comparison is attractive. I’m not convinced it helps us. Solar got cheap by manufacturing millions of near-identical units, with improvements compounding across a global supply chain.” The industries, she went on, are on fundamentally different trajectories. “If we promise one curve and deliver another, we risk looking like we’ve underperformed even when we’re making real progress,” she wrote. “I’d rather we make the harder, more credible argument that geothermal costs come down through repetition in the field. And repetition requires a steady pipeline of projects and capital.”
The wake-up call came shortly after Fervo faced its first major short-seller report. When my colleague Emily Pontecorvo talked to experts on the bearish take on Fervo, she found few industry insiders who took the claims very seriously, but many who feared that, if the company stumbled, raising more money for next-generation geothermal could prove difficult.
The best art, in my humble and dilettantish opinion, can be interpreted multiple ways. The most obvious way to read the latest stunt from the climate activist group 350 Action should require little explanation for a Heatmap reader. The group hired an advertising agency to help construct and place a statue of Florida Governor Ron DeSantis, who has rejected the science behind the climate change so severely impacting his state, cast in gallium, a metal that melts at 85.6 degrees Fahrenheit. When temperatures in Tallahassee, the state capital, reached 90 degrees last Thursday, the statue’s face, which closely resembled the former Republican presidential contender, oozed away, revealing a skull. But here’s another way to look at it: The U.S. is facing a severe shortage of gallium, which is needed for power electronics, solar cells, and electric vehicles. As Noah Gordon, a policy fellow at the European Council on Foreign Relations, put it: “Hilarious way to use scarce US supplies of gallium.” Take from that what you will.
The additional clean capacity would represent nearly 3% of North America’s existing total.
North America has about 37.5 gigawatts of total virtual power plant capacity, according to energy consultancy Wood Mackenzie’s latest estimate, published last year. That capacity is spread across roughly 2,000 VPPs, which aggregate distributed energy resources like batteries, smart thermostats, and heat pumps to cut, shift, or supply electricity when the grid is under strain — effectively turning them into a single, coordinated power plant.
On Thursday, Google and VPP operator Voltus announced plans to add another 1 gigawatt of clean capacity over the next three or four years — or nearly 3% of North America’s existing total. Under Voltus’ “bring your own capacity” model, Google will fund the VPP to help meet its booming data center power needs, while Voltus will enroll businesses and households across the PJM Interconnection, the notoriously overstrained grid region spanning parts of the Midwest and Mid-Atlantic, compensating them for their participation either directly or through electricity bill credits.
The announcement expands on a three-year, 100-megawatt deal the two companies signed in June, extending their commitment through 2040. Voltus CEO Dana Guernsey told me that the smaller deal gave the companies a starting point for a much more ambitious partnership. “It’s a lot easier to explain to people how you’re going to 10x if you’ve already 1x, and so we had to start somewhere,” she said. “We always had our eyes set on bigger things.”
Earlier this month, Voltus closed an oversubscribed $225 million Series D round led by Generation Investment Management to scale its VPP portfolio to 20 gigawatts by 2030. The first phase of the Google partnership is also oversubscribed, Guernsey told me. While that flexible power won’t come online until next year, this means Voltus has already lined up over 100 megawatts of accredited capacity that PJM can count on to deliver when needed, much as it would a natural gas plant or solar-plus-storage installation.
In the meantime, the VPP operator says its broader PJM portfolio has already demonstrated what it can do. Last week, an unseasonably warm stretch of fall weather required PJM to activate its Emergency Load Response Program twice. With 46 gigawatts of generation offline for planned maintenance or construction and another 15 gigawatts unexpectedly unavailable, “distributed resources came through,” Guernsey posted on LinkedIn. “This is how a modern grid should work.” Based on preliminary data, she told me that Voltus delivered about 105% of its committed load reduction during the events.
And VPPs can do more than help avert emergencies. Grid operators are increasingly calling on distributed resources for routine grid management too, such as to ease daily price spikes, reduce emissions when the sun or wind isn’t available, or relieve congestion on a local line. “It’s nearly constant. I think soon we’ll be able to say it’s like every hour,” Guernsey told me.
So far this year, Voltus has reduced electricity demand in PJM by more than 200 gigawatt-hours. Now the company plans to lean more heavily on batteries, particularly at commercial and industrial sites, to accelerate its growth. Guernsey told me that with battery costs falling, electricity prices rising, and fixed payments to participants through 2040, the math now works to deploy batteries at scale, without exposure to unpredictable wholesale electricity prices.
She’s betting that other hyperscalers will see the value in large-scale battery deployments too. Most of the buzz today has revolved around hyperscalers bringing their own generation online — both to secure power faster and head off community opposition by paying their own way. Thus far, Google is the only hyperscaler committed to bringing its own distributed capacity through a VPP. But getting the big players to embrace these new “bring your own capacity” contracts, which Voltus launched last September, is central to its growth strategy.
Guernsey has likened these novel capacity contracts to the corporate renewable power purchase agreements that Google also helped pioneer in the early 2010s. Now she sees a similar opportunity for VPPs to move from a promising concept to a mainstream procurement tool.
“There’s been this notion that we’re coming up on an inflection point for a very long time,” she said of the VPP market. “And I want to be able to say we came up on the inflection point, we went past it, and now we are scaling. And this is an awesome proof point.”