You’re out of free articles.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
The uncertainty created by Trump’s erratic policymaking could not have come at a worse time for the industry.

This is the second story in a Heatmap series on the “green freeze” under Trump.
Climate tech investment rode to record highs during the Biden administration, supercharged by a surge in ESG investing and net-zero commitments, the passage of the Infrastructure Investment and Jobs Act and Inflation Reduction Act, and at least initially, low interest rates. Though the market had already dropped somewhat from its recent peak, climate tech investors told me that the Trump administration is now shepherding in a detrimental overcorrection. The president’s fossil fuel-friendly rhetoric, dubiously legal IIJA and IRA funding freezes, and aggressive tariffs, have left climate tech startups in the worst possible place: a state of deep uncertainty.
“Uncertainty is the enemy of economic progress,” Andrew Beebe, managing director at Obvious Ventures, told me.
The lack of clarity is understandably causing investors to throw on the brakes. “We’ve talked internally about, let’s be a little bit more cautious, let’s be a little more judicious with our dollars right now,” Gabriel Kra, co-founder at the climate tech firm Prelude Ventures, told me. “We’re not out in the market, but I would think this would be a really tough time to try and go out and raise a new fund.”
This reluctance comes at a particularly bad time for climate tech startups, many of which are now reaching a point where they are ready to scale up and build first-of-a-kind infrastructure projects and factories. That takes serious capital, the kind that wasn’t as necessary during Trump’s first term, or even much of Biden’s, when many of these companies were in a more nascent research and development or proof-of-concept stage.
I also heard from investors that the pace of Trump’s actions and the extent of the economic upheaval across every sector feels unique this time around. “We’re entering a pretty different economic construct,” Beebe told me, citing the swirling unknowns around how Trump’s policies will impact economic indicators such as inflation and interest rates. “We haven’t seen this kind of economic warfare in decades,” he said.
Even before Trump took office, it was notoriously difficult for climate companies to raise funding in the so-called “missing middle,” when startups are too mature for early-stage venture capital but not mature enough for traditional infrastructure investors to take a bet on them. This is exactly the point at which government support — say, a loan guarantee from the Department of Energy’s Loan Programs Office or a grant from the DOE’s Office of Clean Energy Demonstrations — could be most useful in helping a company prove its commercial viability.
But now that Trump has frozen funding — even some that’s been contractually obligated — companies are left with fewer options than ever to reach scale.
One investor who wished to remain anonymous in order to speak more openly told me that “a lot of the missing middle companies are living in a dicier world.” A 2023 white paper on “capital imbalances in the energy transition” from S2G Investments, a firm that supports both early-stage and growth-stage companies, found that from 2017 to 2022, only 20% of climate capital flowed toward companies at this critical inflection point, while 43% went to early-stage companies and 37% towards established technologies. For companies at this precarious growth stage, a funding delay on the order of months could be the difference between life and death, the investor added. Many of these companies may also be reliant on debt financing, they explained. “Unless they’ve been extremely disciplined, they could run into a situation where they’re just not able to service that debt.”
The months or even years that it could take for Trump’s rash funding rescission to wind through the courts will end up killing some companies, Beebe told me. “And unfortunately, that’s what people on the other side of this debate would like, is just to litigate and escalate. And even if they ultimately lose, they’ve won, because startups just don’t have the balance sheets that big companies would,” he explained.
Kra’s Prelude Ventures has a number of prominent companies in its portfolio that have benefitted from DOE grants. This includes Electric Hydrogen, which received a $43.3 million DOE grant to scale electrolyzer manufacturing; Form Energy, which received $150 million to help build a long-duration battery storage manufacturing plant; Boston Metal, which was awarded $50 million for a green steel facility; and Heirloom, which is a part of the $600 million Project Cypress Direct Air Capture hub. DOE funding is often doled out in tranches, with some usually provided upfront and further payments tied to specific project milestones. So even if a grant has officially been awarded, that doesn’t mean all of the funding has been disbursed, giving the Trump administration an opening to break government contracts and claw it back.
Kra told me that a few of his firm’s companies were on the verge of securing government funding before Trump took office, or have a project in the works that is now on hold. “We and the board are working closely with those companies to figure out what to do,” he told me. “If the mandates or supports aren’t there for that company, you’ve got to figure out how to make that cash last a bunch longer so you can still meet some commercially meaningful milestones.”
In this environment, Kra said his firm will be taking a closer look at companies that claim they will be able to attract federal funds. “Let’s make sure we understand what they can do without that non-dilutive capital, without those grants, without that project level support,” he told me, noting that “several” companies in his portfolio will also be impacted by Trump’s ever-changing tariffs on imports from Canada, Mexico, and China. Prelude Ventures is working with its portfolio companies to figure how to “smooth out the hit,” Kra told me later via email, but inevitably the tariffs “will affect the prices consumers pay in the short and long run.”
While investors can’t avoid the impacts of all government policies and impulses, the growth-stage firm G2 Venture Partners has long tried to inoculate itself against the vicissitudes of government financing. “None of our companies actually have any exposure to DOE loans,” Brook Porter, a partner and co-founder at G2, told me in an email, nor have they received government grants. If you add up the revenue from all of the companies in G2’s portfolio, which is made up mainly of sustainability-focused startups, only about 3% “has any exposure to the IRA,” Porter told me. So even if the law’s generous clean energy tax credits are slashed or the programs it supports are left to languish, G2’s companies will likely soldier on.
Then there are the venture capitalists themselves. Many of the investors I spoke with emphasized that not all firms will have the ability or will to weather this storm. “I definitely believe many generalist funds who dabbled in climate will pull back,” Beebe told me. Porter agreed. “The generalists are much more interested in AI, then I think in climate,” he said. It’s not as if there’s been a rash of generalist investors announcing pullbacks, though Kra told me he knows of “a couple of firms” that are rethinking their climate investment strategies, potentially opting to fold these investments under an umbrella category such as “hard tech” instead of highlighting a sectoral focus on energy or climate, specifically.
Last month, the investment firm Coatue, which has about $70 billion in assets under management, raised around $250 million for a climate-focused fund, showing it’s not all doom and gloom for the generalists’ climate ambitions. But Porter told me this is exactly the type of large firm he would expect to back out soon, citing Tiger Global Management and Softbank as others that started investing heavily during climate tech’s boom years from 2020 to 2022 that he could imagine winding down that line of business.
Strategic investors such as oil companies have also been quick to dial back their clean energy ambitions and refocus their sights on the fossil fuels championed by the Trump administration. “Corporate venture is very cyclical,” Beebe told me, explaining that large companies tend to make venture investments when they have excess budget or when a sector looks hot, but tighten the purse strings during periods of uncertainty.
But Cody Simms, a managing partner at the climate tech investment firm MCJ, told me that at the moment, he actually sees the corporate venture ecosystem as “quite strong and quite active.” The firm’s investments include the low-carbon cement company Sublime Systems, which last year got strategic backing from two of the world’s largest building materials companies, and the methane capture company Windfall Bio, which has received strategic funding from Amazon’s Climate Pledge Fund. Simms noted that this momentum could represent an overexuberance among corporations who just recently stood up their climate-focused venture arms, and “we’ll see if it continues into the next few years.”
Notably, Sublime and Windfall Bio both also have millions in DOE grants, and another of MCJ’s portfolio companies, bio-based chemicals maker Solugen, has a “conditional commitment” from the LPO for a loan guarantee of over $200 million. Since that money isn’t yet obligated, there’s a good chance it might never actually materialize, which could stall construction on the company’s in-progress biomanufacturing facility.
Simms told me that the main thing he’s encouraging MCJ’s portfolio companies to do at this stage is to contact their local representatives — not to advocate for climate action in general, but rather “to push on the very specific tax credit that they are planning to use and to talk about how it creates jobs locally in their districts.”
Getting startups to shift the narrative away from decarbonization and climate and toward their multitudinous co-benefits — from energy security to supply chain resilience — is of course a strategy many are already deploying to one degree or another. And investors were quick to remind me that the landscape may not be quite as bleak as it appears.
“We’ve made more investments, and we have a pipeline of more attractive investments now than we have in the last couple of years,” Porter told me. That’s because in spite of whatever havoc the Trump administration is wreaking, a lot of climate tech companies are reaching a critical juncture that could position the sector overall for “a record number of IPOs this year and next,” Porter said. The question is, “will these macro uncertainties — political, economic, financial uncertainty — hold companies back from going public?”
As with so many economic downturns and periods of instability, investors also see this as a moment for the true blue startups and venture capitalists to prove their worth and business acumen in an environment that’s working against them. “Now we have the hardcore founders, the people who really are driven by building economically viable, long-term, massively impactful companies, and the investors who understand the markets very well, coming together around clean business models that aren’t dependent on swinging from one subsidy vine to the next subsidy vine,” Beebe told me.
“There is no opportunity that’s an absolute no, even in this current situation, across the entire space,” the anonymous climate tech investor told me. “And so this might be one of the most important points — I won’t say a high point, necessarily — but it might be a moment of truth that the energy transition needs to embrace.”
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Current conditions: For the first time since 1914, the Atlantic hurricane season may pass without any major hurricanes, per an AccuWeather forecast • From Phoenix to Dallas, flood watches are in effect as the remnants of Hurricane Polo stretch inland from the Pacific through the Southwest • Surigae, now upgraded to a “severe” tropical storm, is set to slam into Japan’s Izu Islands, a partially populated archipelago in the same municipality as Tokyo.
The Department of Energy has ordered the release of 40 million barrels of oil from the Strategic Petroleum Reserve as diesel surpasses $6.50 per gallon and Texas proclaims a statewide “disaster” over soaring prices. The move, which Secretary of Energy Chris Wright said would “stabilize the market,” comes as the Trump administration weighs whether to temporarily ban exports of diesel, a radical step that might only slightly lower American prices while sending Europe’s fuel costs skyrocketing, as the chief executive of the continent’s No. 2 oil company cautioned in a Bloomberg interview this week. The oil is expected to be a loan from the stockpile that would, Wright said, ultimately save Americans more than $3 billion. The transaction follows the same approach the Trump administration has taken since agreeing to distribute 172 million barrels from the Strategic Petroleum Reserve back in March, when the war with Iran began. Had the administration instead sold the barrels through an emergency drawdown instead of a trade, as it did previously, and simultaneously structured the deal to allow it to buy back oil at the lower prices the futures market is trading at presently, the Energy Department could have significantly increased its profits. That’s the finding of a policy memo from the think tank Employ America that I told you about a few weeks ago. The profit could, in turn, be used to invest in America’s fuel stockpile, clearing some of the $230 million backlog of physical repairs needed on the infrastructure that stores the crude. “The choice to deliver more barrels is fraught, but with that decision made, the administration missed an opportunity to set up the SPR for long-term success,” Arnab Datta, Employ America’s managing director of policy implementation, told me in a text message last night. “I hope they consider creative options to do so moving forward.”
Meanwhile, oil is actually flowing through the Strait of Hormuz again. “Iran’s regime has lost control of the Strait of Hormuz,” energy investor Alexander Stahel wrote in a lengthy post on X. The U.S. military’s naval escorts and the United Arab Emirates’ commitment to circumventing Iran’s blockade are returning the critical waterway to “normal,” as my colleague Robinson Meyer wrote. Over text message last night, I asked an energy trader if this meant we were winning. “I’d say we’re losing less than we had been,” they said. “If Iran hadn’t gotten the Houthis to attack Saudi Arabia and seize the Red Sea, we’d definitely be.” Big if!
British Prime Minister Andy Burnham emerged triumphant from the Labour Party’s recent political implosions after he established himself as a pragmatic left-wing populist during his time as mayor of Manchester — drawing frequent comparisons to New York City Mayor Zohran Mamdani. Now Burnham is demonstrating what his brand of “business-friend socialism” means in energy. On Tuesday, Downing Street announced the launch of Great British Grid, a new subsidiary of the state-owned Great British Energy, designed to compete with private companies for investments in the power grid. “We have a cost crisis. We all know it,” Burnham said in a speech, according to The Guardian, which broke news of GB Grid. “The price of energy is crippling for businesses, and British bill payers pay some of the highest energy costs in Europe. We have an energy system where prices are dictated in markets miles away, while families and businesses here shoulder the costs. Once again, the British public has lost control.” His answer? Reverse what he called “40 years of neoliberalism.” Over here on this side of the pond, we are waiting to see what’s in the deal the Senate has brokered to ease federal permitting, one of many hurdles to building new transmission lines in America. The text of the agreement is due out later today.
Down in the South Atlantic, things are heating up in the Falkland Islands, even as temperatures outside remain low. The archipelago has never had a native population — as far as anyone can tell, the longest-lasting settled population has been the mostly British herders and fishers who have voted repeatedly to stay under the British crown. That didn’t stop Argentina, which has claimed what it calls Las Malvinas for centuries, from launching an invasion in 1983, in which the British military won a decisive victory. Now that the sleepy Falklands are preparing to drill oil wells in the offshore economic zone surrounding the islands, Buenos Aires is waging what one Falklander described to the Financial Times as “economic warfare.” Instead of Union Jacked Sea Harriers and Argentinian light cruisers doing the combat, this time Argentina is limiting trade, isolating the Falklands. “We’re just a few thousand people trying not to get blown off a rock,” local radio host Ronnie MacLennan Baird told the newspaper. “We just want to get on with our lives.”

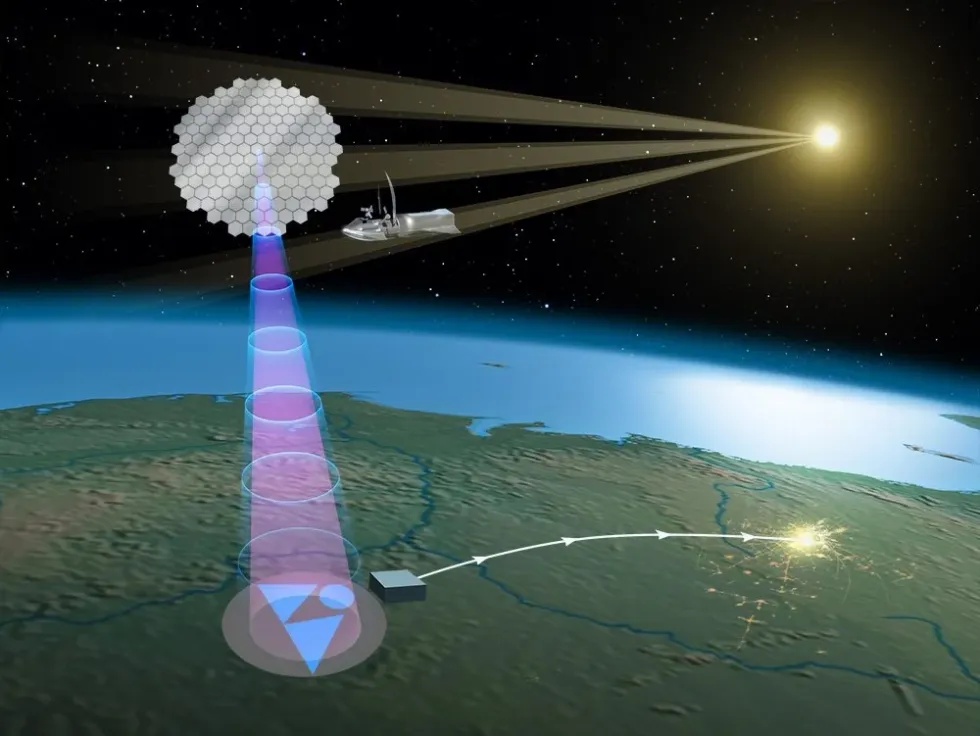
Lots of solar developers are promising to compete with nuclear, geothermal, and hydro plants in generating the type of electricity that matches today’s favored buzzwords of “24/7,” “clean,” and “baseload” by pairing panels with batteries. Few companies, for obvious reasons, actually mean generating solar energy all day and night. Virtus Solis Technology, on the other hand, is promising to pioneer a method for delivering solar power generated from panels affixed to satellites in space, capable of angling at every hour to meet the sun’s rays and beaming wireless power back down to Earth. It’s hardly the only developer reaching for solar in space. But the Troy, Michigan-based startup is the first to get someone to agree to buy that electricity. On Wednesday, the company inked its first power purchase agreement to sell electricity from its debut, 100-megawatt solar satellite to the Chicago-based data center developer Brae Systems over the next 20 years. Virtus Solar called it the “first in a series of commercial offtake agreements” expected in the next several months. As part of the deal, Virtus Solar will build a “dedicated terrestrial receiving station to be constructed in Illinois.” The contract includes an option to increase capacity to 250 megawatts within three years of commercial operations. “Securing a direct 20-year supply of firm, clean power from Virtus Solis ensures our GPU infrastructure operates with predictable power costs and zero carbon emissions, completely insulated from terrestrial grid curtailment,” Brae Systems CEO Vishnu Indukuri said in a statement.
Other frontier energy sources have evolved quickly from plans to deals. Commonwealth Fusion Systems, the current frontrunner in America’s fusion startup race, signed its inaugural power purchase agreement with Google last year. Now the spinout from the Massachusetts Institute of Technology is attracting institutional investors, as my colleague Katie Brigham has written, and inching closer to building out its supply chain. On Wednesday morning, the company announced what it called a “landmark supply agreement” with the Japanese industrial giant Fujikura to buy more than 6,200 miles of high-temperature superconducting tape to help build CFS’ doughnut-shaped ARC fusion reactors.
Sign up to receive Heatmap AM in your inbox every morning:
As of now, the European Union is set to start forcing foreign oil and gas companies to monitor and submit data on their methane emissions or face financial penalties. But Brussels is now considering delaying the methane reporting rules by as much as a year as tight fuel supplies send prices ever higher amid the twin energy shocks from the wars in Iran and Ukraine. On Tuesday, Reuters and OilPrice.com reported that EU Energy Commissioner Dan Jorgensen had confirmed that officials are examining whether to postpone the provisions. The statement came days after Jorgensen made a similar remark to Bloomberg.
Meanwhile, Jorgensen’s native Denmark is heeding the former U.S. Energy Secretary Ernie Moniz’s call to invest more in clean fuels. On Tuesday, Hydrogen Insight reported that the country planned to increase its budget for building a network of dedicated hydrogen pipelines by $850 million.
One of the more memorable moments of the 2024 vice presidential debate came when JD Vance lashed his Democratic rival, Minnesota Governor Tim Walz, for failing to prioritize manufacturing of solar panels in the U.S. The Democrat shot back that such factories were open in his very state. Among them was Heliene, a producer of high-performance solar modules designed for boutique rooftop units. On Tuesday, the company rolled out a new all-American module at a moment when solar buyers are increasingly seeking technology that won’t be subject to President Donald Trump’s tariffs. “The new module brings together American-made polysilicon, ingots, wafers, and solar cells, reconnecting critical stages of the solar supply chain with U.S. manufacturing after more than a decade,” the company said, calling the module “an important step in reshoring U.S. solar manufacturing, bringing more of the upstream silicon supply chain back to America.”
As my colleague Emily Pontecorvo and I reported last month, the Department of Commerce just threw solar manufacturers a lifeline by slapping new import levies and restrictions on foreign polysilicon, the main ingredient in solar panels. But the agency halted enforcement until early December, giving importers the opportunity to stockpile in advance of the new rules taking effect. Last week, the Commerce Department moved to ban stockpiling. “Protecting against stockpiling is critical to ensure a functionally viable remedy from the Section 232 rules,” Matt Card, president of the U.S. cell manufacturer Suniva, told PV Tech.
A quick letter of recommendation to close out this morning’s newsletter. Back in 2018, I received a galley copy of a forthcoming book by a niche left-wing sociologist with a growing focus on climate change. The title — After Geoengineering: Climate Tragedy, Repair, and Restoration — struck me. Geoengineering and its associated technological ideas to adapt to a hotter world, such as carbon dioxide removal, were at that point very taboo in climate policy circles. The technology, assuming it even worked, posed what many saw as a moral hazard, a Pandora’s box that, if opened, would sap humanity’s collective will to do the hard work of mitigating fossil fuel emissions. At least, that was the dominant mode of thinking at the time. So, you can imagine, I found that book title provocative. Over the course of 288 pages, the author, Holly Jean Buck, bounced between dense but readable chapters of nonfiction explanations of the latest science behind various cutting-edge climate technologies and sections of fictional sci-fi vignettes. The stories painted a picture of life in the not-so-distant future. One that has stuck with me over the years is a vision of an Oklahoma rancher earning passive income by letting a state carbon disposal program pump captured CO2 into the geological formations beneath his property. I offer my sincere congratulations to Holly, who yesterday was named among the 20 recipients of this year’s MacArthur Foundation’s prestigious “genius grant.”
Novele is aiming to smooth out power consumption for commercial buildings, saving tenants money and easing grid strain.
Electricity is more expensive in times of peak demand — that’s simply a universal truth. But for many commercial building owners and tenants, their most energy-intensive minutes of the month can have an especially outsized impact on their electricity bill. That’s because of the “demand charge,” a fee based on a building’s single highest burst of power consumption, which can make up over 50% of a customer’s monthly bill. Likewise, shrinking those bursts would not only ease strain on the grid, but could also dramatically lower commercial users’ costs.
Or at least that’s Novele’s pitch. The startup, which makes 2-inch-thick, fire-safe lithium-ion batteries that mount on the interior walls of commercial spaces such as offices, hospitals, and big box retailers, announced Wednesday that it raised an oversubscribed $17 million Series A led by impact-focused investor Boisei Labs. The funding will help the company scale its AI-powered battery system, which networks batteries placed throughout a building and uses software to predict impending spikes in power demand. Just before the peak hits, the system can automatically switch the building from grid power to battery power, helping the customer avoid those costly demand charges.
“We learn how the building consumes power, but we’re also taking into account other considerations, like what day of the week it is, how the building is occupied, when it’s being used, what’s happening with the weather conditions,” Novele’s co-founder and CEO Charles Conwell told me.
Of course, battery storage for commercial customers is nothing new. Tesla, for one, has long sold large batteries like its Megapack, along with software designed to help businesses manage and reduce peak demand. But unlike these larger outdoor systems, Novele designed its thin panels for installation inside occupied spaces like hospital hallways and offices, distributing the batteries throughout a building while operating them as a single, coordinated system.
The systems are custom designed, so Novele told me it couldn’t provide an overall cost estimate. But Conwell told me the batteries typically have a 20- to 40-month payback period, the timeframe in which a customer’s electricity bill savings should eclipse the system’s upfront cost. (The company also offers financing options that allow customers to spread out that cost over time.) And while customers may sign up for the cost savings, there are major decarbonization benefits, too. So-called peak-shaving can reduce the need for peaker plants — natural gas facilities that only fire up when demand is highest. These plants are typically among the grid’s most carbon-intensive assets, as they’re designed to ramp up quickly rather than operate efficiently for long periods.
These automated batteries could also enable commercial buildings to participate in virtual power plant programs, which ease strain on the grid by cutting energy use during periods of high demand or by tapping assets like batteries to send power back to the grid. Using stored energy when needed, Conwell explained, is better than typical demand response initiatives, which often require tenants to change their routines — e.g. when they run the dishwasher or charge an EV — to accommodate the grid. That approach, he said, is either “ineffective or doesn’t make the tenants very happy.”
As the company scales, it also envisions building a portfolio of properties that, if they have “a dense enough footprint,” could work in concert to form their own virtual power plant of sorts, Conwell said.
In the near term, however, Novele plans to use its Series A to expand its team, install more systems, and further develop its software. It’s particularly focused on markets where electricity costs are already high or climbing fast, such as California, New York, New England, and parts of the PJM power market. In PJM in particular, record-high capacity prices — largely driven by data center demand — are pushing electricity bills to new heights.
The company says it has already installed batteries for several Fortune 50 customers, though it’s keeping the identities of these early adopters under wraps. Conwell told me that there’s also “a bunch of installations that are in progress,” and that in the coming year, the company will be working toward making the process of purchasing, installing, and operating Novele’s system as seamless as possible.
Once that foundation is in place, Conwell sees an opportunity to help usher in a more responsive, intelligent future for the built environment. “If you get the infrastructure right, if you bring in the controls — the mechanical controls, the machine learning controls, and the artificial intelligence-driven controls — you start to be able to set the stage for a dynamic, autonomous building of the future.”
The former vice president of the United States joined us at Heatmap House for New York Climate Week.
Former Vice President Al Gore needs no introduction. He is, in a way, the original climate influencer. His film An Inconvenient Truth gave rise to a new wave of climate activism in the 2000s. It was one of the highest-grossing documentaries of all time upon its release, and it won an Oscar, a Grammy, and — for Vice President Gore — a Nobel Peace Prize.
He’s remained active in climate policy since then and leads the Climate Reality Project. He is also an investor and was a longtime director at Apple.
For this episode of Shift Key, Vice President Gore joined Rob for a live conversation at our Heatmap House event, part of New York Climate Week. He reflected on the 20th anniversary of An Inconvenient Truth, the existential risk of artificial intelligence, and what has surprised him most about the evolution of climate politics.
Shift Key is hosted by Robinson Meyer, the founding executive editor of Heatmap News.
Subscribe to “Shift Key” and find this episode on Apple Podcasts, Spotify, Amazon, YouTube, or wherever you get your podcasts.
You can also add the show’s RSS feed to your podcast app to follow us directly.
Here is an excerpt from their conversation:
Robinson Meyer: Let’s start by talking about 20 years ago, because 20 years ago, An Inconvenient Truth came out. I recently had cause to revisit the film, and I actually have to confess something. I was very excited when the movie came out, but I don’t think I’ve ever admitted this, and maybe this is the wrong audience to do it to: I was too stressed about climate change to actually watch it. Not that it was a daily anxiety, but I was like, “I can’t. There’s so many other things.” And so I actually watched it for the first time only recently.
I had the book, let’s be clear. I had the book.
Al Gore: A limited confession.
Meyer: Yeah, yeah. It was so fascinating watching it 20 years on, because there are some sections of it that I think you could give today. Not that little has changed — the science hasn’t, of course — but the way people think about it, the way people move from denial to doom, hasn’t changed in some ways. I wondered what surprised you most about the intervening 20 years since the film came out. It received a response that, I don’t know what you were anticipating, but it was certainly on a scale beyond what was expected at the time. And then there’s where we are today.
Gore: Well, when Laurie David first made the suggestion, here in this city, I gave an early version of my slideshow when we were promoting that movie. What was it, The Day After —
Meyer: The Day After Tomorrow?
Gore: The Day After Tomorrow. Was that it? Yeah. And they said, “Well, that’s fiction, isn’t it?” And I said, “Well, it’s not as fictional as the then-current administration was about climate.” But when she said, “This needs to be made into a movie,” I said, “You’re crazy.” As one of the early reviewers said, “Al Gore giving a slideshow — what part of that doesn’t scream hit?” So I was a skeptic about the enterprise, and I was surprised at the reception it got.
Really, the credit belongs to the scientists I was just channeling. The fact that everything they predicted has proven to be basically spot on is a credit to them. For the rest of us, the fact that they were so right then should cause us to pay more attention to what they’re warning us about now.
As for what has surprised me, it’s the ferocity and durability and massive continued financing of climate denial by the fossil fuel industry. There was a time during these last 20 years when they said they were going to be part of the solution, and a couple of them made some good-faith efforts in that direction. But then, like Steve Martin on the old SNL, they went, “Nah.” They decided just to give up the ghost and go full speed ahead on more and more fossil fuels. I think they’re losing as we are winning, but they’re hanging in there.
You can find a full transcript of the episode here.
Mentioned:
Previously on Shift Key: Energy Secretary Chris Wright on Trump’s Pro-Nuclear, Pro-Fossil Fuel Agenda
This episode of Shift Key is sponsored by ...
RE+ 26 is the largest clean energy event in North America, happening November 16th through 19th at the Las Vegas Convention Center. Register at re-plus.com and use code SHIFTKEY20 to save 20% off a Full Conference pass.
Music for Shift Key is by Adam Kromelow.