To say that concrete poses a decarbonization challenge would be an understatement. Cement production alone is responsible for somewhere between 5 and 10% of global CO2 emissions [0], roughly two to four times more than aviation, a fact that even the construction industry is finally coming to grips with.
And yet the real problem with decarbonizing concrete isn’t the scale of its emissions, it’s the scale of concrete itself. There is simply a preposterous amount of the stuff. Contemplating concrete is like contemplating the universe — awesome, in the old God-fearing definition of the word.
How concrete is made
Before we get into the jaw-dropping amount of concrete we produce every year, it’s worth briefly discussing how the stuff is made, and thus where its emissions come from.
Concrete is formed by mixing together cement (mostly calcium silicates), aggregates (such as sand and gravel), and water into a liquid slurry. The cement reacts with the water, forming a paste that binds the mixture into a single solid mass. Beyond concrete’s high strength and low cost, it’s these liquid beginnings that make concrete so useful. It can easily be formed into any shape and leveled with the help of gravity so you can walk on it or park a car 10 stories up on it. Essentially all modern concrete is also reinforced with steel bars, which provide tensile strength and arrest cracks.
So what about the emissions? Roughly 70-90% of the embodied carbon in concrete comes from manufacturing just the cement [1]. Partly this is because making cement is an energy-intensive process — limestone and clay are put into a kiln and heated around 2500 degrees Fahrenheit. But it’s also because the chemical reaction that turns the limestone into cement (known as calcination) releases CO₂ as a byproduct. Roughly 50-60% of cement’s carbon emissions are due to calcination [2], and thus wouldn’t be addressed by moving to less carbon-intensive electricity sources, like green hydrogen.
The scale of concrete production
Now for the good stuff. Again, the most important thing to understand about concrete is the scale of its production. The world produces somewhere around 4.25 billion metric tons of cement annually (though estimates vary) [3], which works out to about 30 billion tons of concrete produced each year [4].
How much are 30 billion tons?
One way of looking at it is we produce around 4 metric tons, or just under 60 cubic feet (roughly a cube 4 feet on a side), of concrete for each person on the planet each year.
Another way of looking at it is to consider the total amount of mass, full stop, that civilization ingests each year. Estimates here vary quite a bit, but it seems to be in the neighborhood of 100 billion tons [5]. So of the total volume of material that gets extracted and used each year — including all mining, all oil drilling, all agriculture and tree harvesting — around 30% of it by mass goes toward making concrete. The amount of concrete produced each year exceeds the weight of all the biomass we use annually, and all the fossil fuels we use annually.
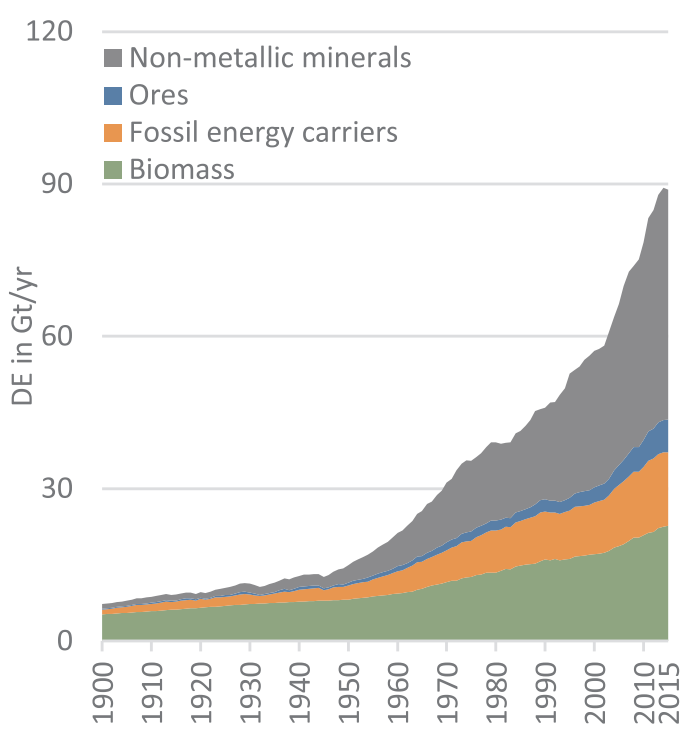
Total civilization annual material extraction, via Krausmann et al 2018. This is up to 2015, and has now exceeded over 90 Gt/year, with another ~8 Gt/year of recycled material.
Another way of looking at it is that the total mass of all plants on Earth is around 900 billion metric tons. So at current rates of production, it would take about 30 years to produce enough concrete to exceed all the Earth’s plant (dry) biomass.
Because humans have been producing concrete for a while, and because concrete tends to last a long time, we seem to be on the cusp of this happening. Elhacham et al 2020 estimate that total human-created mass (roughly half of which is concrete) reached the total weight of all Earth’s biomass sometime in 2020. Eyeballing their graph, concrete alone will exceed the total weight of all biomass sometime around 2040.
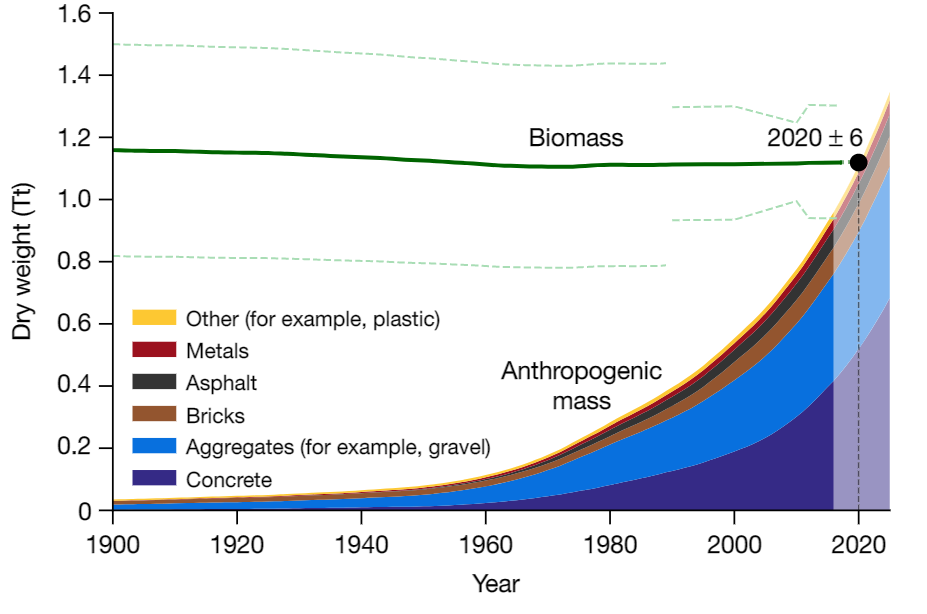 Anthropogenic mass vs biomass during the 20th century, via Elhacham et al 2020
In a pure mass-flow sense, human civilization is basically a machine for producing concrete and gravel (and to a lesser extent bricks and asphalt).
Where concrete goes
So civilization uses a lot of concrete. Where is it all going?
China, mostly. In recent history, China has been responsible for roughly half the world’s cement production, and by implication, concrete use [6]. The U.S., by comparison, only uses 2%, with Europe using another 5%.
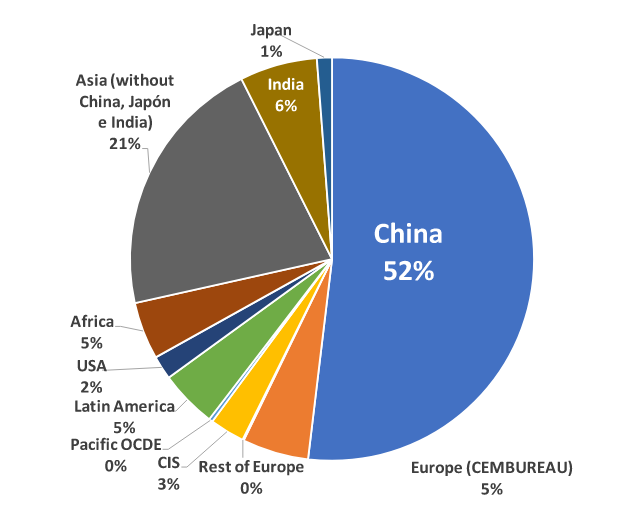
Cement production by region, via Sanjuan et al 2020. Since cement production roughly tracks consumption (see here and here), we can also use this as a rough guide toward where concrete is used. Note that this gives yet another value for total global cement production of 4.65 Gt
Here’s another view from around 2010, showing what this has looked like over time (data after 2010 is a projection).
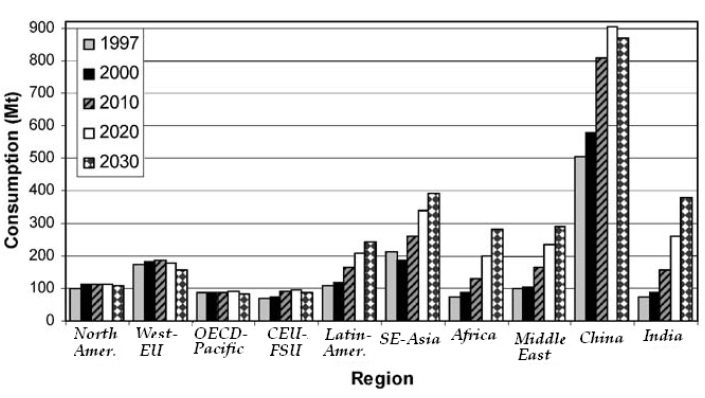
Cement consumption by region, via Altwair 2010
This gets summarized in the oft-repeated statistic that China used more cement in three years than the U.S. did in the entire 20th century.
But since China has a much larger population than the U.S., we can get a more intuitive understanding of this by looking at cement consumption per capita. Here’s per capita consumption sometime around 2015:
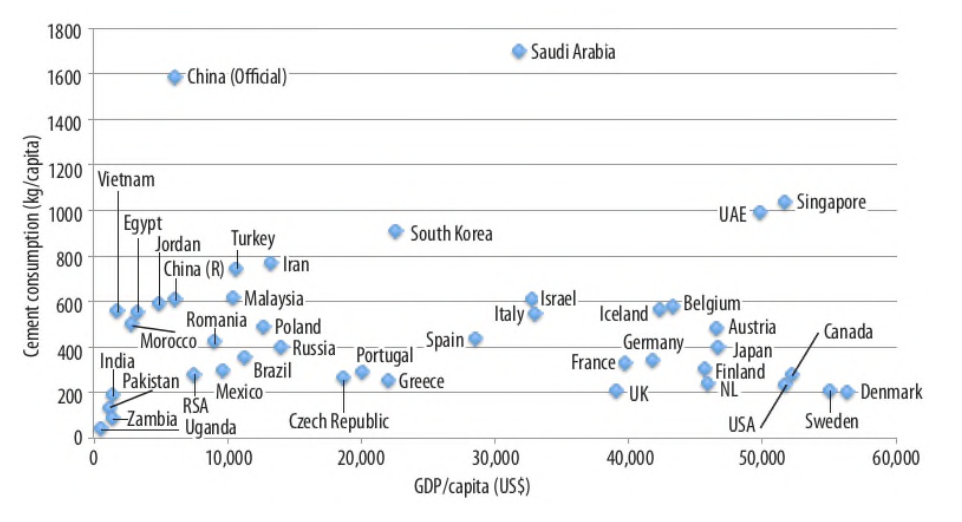
Per capita cement consumption by country, via Globbulk
We see that the official numbers from China make it a huge outlier in cement consumption, using around eight times as much per capita as the U.S. However, in per capita terms, some Middle Eastern countries exceed it. Saudi Arabia is higher, and Qatar, which is somewhere over 2,000 kg/capita, is so high it doesn’t even show up on the graph. It’s the combination of China’s huge population and its huge per-capita consumption that make it such an outlier in concrete production.
The official Chinese numbers are so huge, in fact, that some analysts suspect that they’re inflated, either by manipulating the data or by producing construction projects that don’t have actual demand (or both). The graph above also includes a more “realistic” estimate (which is still 3x as high as U.S. per-capita use).
What does all this concrete construction mean in practical terms? Well, China has somewhere around 50-60% of the floor space per capita as the U.S. does, or roughly as much living space per capita as most European countries [7]. This is the result of a massive trend toward urbanization over the last quarter century. Urbanization rates went from around 25% in 1990 to 60% in 2017, a period in which China’s population also increased by 250 million. In other words, in less than 30 years over 550 million moved into Chinese cities, and they all needed somewhere to live. By building enormous numbers of concrete high rises, in under 20 years China quintupled its urban residential floor space and doubled its residential floor space overall.
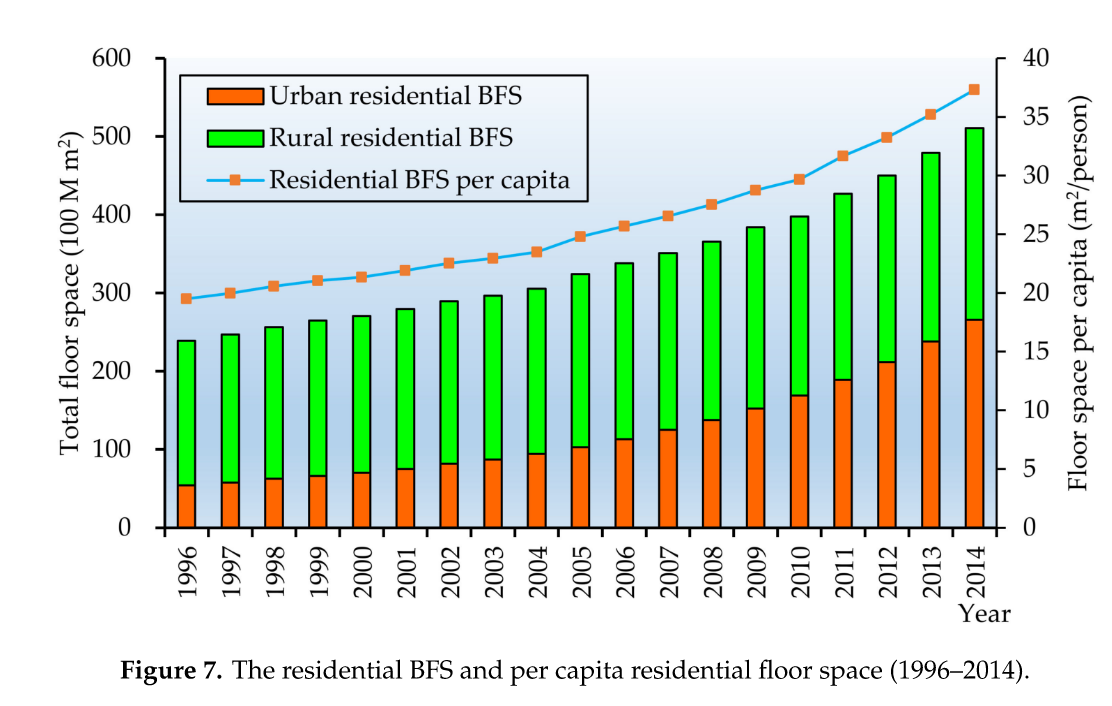
Residential floor space in China over time, via Pan 2020
Beyond China, we see high per capita rates of cement use in the rest of Southeast Asia, as well as the Middle East [8].
One reason you see this volume of concrete use in lower-income, urbanizing countries is that concrete construction is comparatively labor-intensive to produce. The materials for concrete are extremely cheap, and much of its cost in high-cost labor countries (such as the U.S.) is from the labor to produce it — building and setting up the formwork, laying out the reinforcing, placing the embeds, etc. If you’re a country with a lot of low-cost labor, this is a pretty good trade-off.
In addition to the current largest users of concrete, one trend to keep an eye on long-term is India’s concrete use. If India ever proceeds on a path of mass urbanization similar to China (as some folks speculate it will), we could see a massive uptick in global concrete output — India’s urbanization rate of 34% is around where China was in the late 1990s. A shift in India toward a per capita cement consumption more consistent with the rest of Southeast Asia (say around 600 kg/capita) would increase worldwide cement consumption by about 13%, and it does seem as if India’s cement use is trending upward.
By contrast, one thing clear from this data is that the U.S. actually uses an unusually low amount of concrete. Per capita, it uses as little as any other Western country, and far, far less than some — like, surprisingly, Belgium.
Concrete use by application
So we’ve seen where it gets used in the world. Can we go deeper and look at specifically what concrete is being used for?
This will vary significantly depending on the region and the local construction tradition. In the U.S., we have roughly the following breakdown (via the Portland Cement Association):
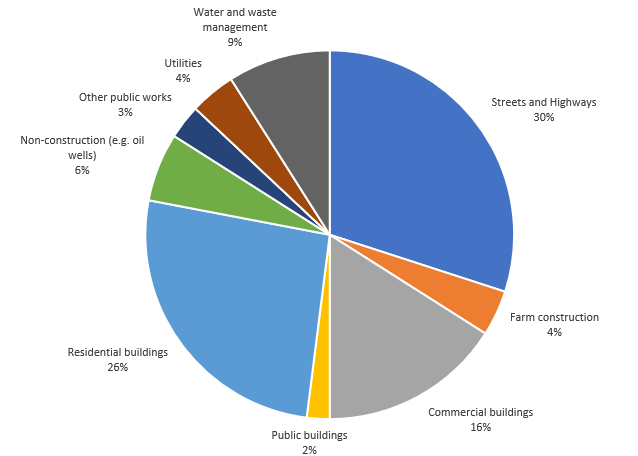
Courtesy of the PCA
Overall, roughly half of our concrete gets used in buildings — about 26% goes into residential buildings, 2% in public buildings, and 16% into commercial buildings. The other half gets used for infrastructure — streets and highways, water conveyance and treatment tanks, etc. Because most construction in the U.S. is just one- or two-story buildings (mostly wood for residential buildings and steel for commercial ones), concrete in buildings is probably mostly going into foundations, slabs on grade, and concrete over metal deck, though there’s probably a substantial amount going into concrete masonry units as well.
But the U.S. has a somewhat unusual construction tradition, where the vast majority of our residential construction, both single-family homes and multifamily apartments, is built from light-framed wood. In other places, it's much more common to use concrete. For instance, the U.K. uses closer to 80% of its concrete for buildings, with most of that going toward the superstructure, the concrete frame that holds the building up. China, which has urbanized on the back of huge numbers of concrete residential high rises, probably devotes an even larger share of its concrete to residential construction.
A world with less concrete
Understanding how much concrete the world uses, and where it’s being used, is important if you want to use less of it.
The scale of the industry is particularly important to keep in mind. For instance, you often see enthusiasm for the idea of replacing concrete buildings with mass timber ones. But assuming you could substitute all the world’s concrete for an equal volume of wood [9], you’d need to more than triple the total annual volume of global wood harvested [10], which puts a somewhat different spin on the issue.
Most other materials would have emissions as bad or worse than concrete if they were used on the same scale.
Consider, for instance, railway ties. In the U.S., these are still largely made out of wood, but in many places they have been replaced with concrete ties. And some places are considering changing from concrete ties to plastic composite rail ties instead. It’s hard to know the exact embodied emissions without a lot of specific details about the materials and supply chains used, but can we ballpark how much a plastic tie uses compared to a concrete one?
Per the Inventory of Carbon and Energy database, concrete varies between 150 and 400 kg of embodied CO2 per cubic meter, depending on the properties of the mix, with an “average” value of about 250. Plastics mostly have embodied emissions of about 3-4 kg of CO2 per kg of plastic, or about 3,500 kg per cubic meter (assuming a density of about 1,000 kg per cubic meter). So per unit volume, plastic has somewhere around 10 times the embodied emissions of concrete.
We can also do a more direct comparison. Consider a beam spanning around 20 feet and supporting a vertical load of 21,000 pounds per linear foot. The lightest U.S. standard steel section that will span this distance is a W16x26, which weighs about 236 kg and will have embodied carbon emissions of around 354 kg.
A concrete beam of the same depth, supporting the same load and spanning the same distance, will be 10.5 inches wide by 16 inches deep, with three #10 steel bars running along the bottom. This beam will have about 190 kg of embodied emissions from the concrete, and about another 230 kg of embodied emissions from the steel rebar. This is about 20% more than the steel beam, but in the same ballpark — and over half the “concrete” emissions are actually due to the embedded reinforcing steel.
This is arguably a nonrepresentative example (most concrete, such as in columns or slabs, will have a much lower ratio of steel), but the basic logic holds: Concrete is unusual in its total volume of use, not how emissions-heavy it is as a material. Most material substitutes that aren’t wood, recycled materials, or industrial byproducts that can be had for “free” won’t necessarily be much better when used at the same scale. In some ways, it’s surprising that the carbon emissions from concrete are as low as they are.
Lower carbon cement
Of course, this calculus is likely to change over time — as electricity sources change over to lower carbon ones, you’re likely to see the embodied emissions of materials drop along with it. And since cement releases CO2 as part of the chemical process of producing it, concrete will look increasingly worse compared to other materials over time.
One potential option is to find ways of changing the cement production process to be less carbon-intensive. The easiest option is to just replace manufactured Portland Cement with some other cementitious material. Industrial byproducts such as blast furnace slag, silica fume, and fly ash, often have cementitious properties and don’t have a “carbon penalty” (since they’d be produced regardless.) Materials like these can potentially eliminate large volumes of cement in a concrete mix, and they’re a key part of current low-carbon concrete strategies — even “normal” concrete mixes tend to utilize these to some degree. But the total volume of these materials is limited by the extent of various industrial processes. And for things like fly ash (which is a byproduct from coal plants) and slag (which is a byproduct from CO2-emitting blast furnaces), we can expect production to decline over time.
Another option is to take advantage of the fact that concrete will naturally absorb CO2 over time, a process known as carbonation. Even normal concrete will absorb roughly 30% of the CO2 emitted during the production process over the course of its life. Companies like Carbicrete, Carboncure, Carbonbuilt, and Solida all offer methods of concrete production that allow the concrete to absorb CO₂ during the production process, substantially reducing embodied emissions. Interestingly, these producers mostly claim that their concrete is actually cheaper than conventional concretes, which would obviously be a massive tailwind for the technology’s adoption.
It’s not obvious what the best path forward is for addressing concrete carbon emissions (like with most things, I suspect it’ll end up being a mix of different solutions), but understanding the parameters of the problem is necessary for solving it.
Note: A version of this article originally appeared in the author’s newsletter, Construction Physics, and has been repurposed for Heatmap.
Footnotes
[0] - This figure varies depending on the source. Chatham House provides a frequently cited estimate of 8%. We can also ballpark it — roughly 0.93 pounds of CO₂ gets emitted for each pound of cement produced, around 4.25 billion tons of cement are produced annually, which gets ~3.95 billion tons of CO₂, and total annual CO₂ emissions are in the neighborhood of 46 billion tons, getting us a bit less than 9%.
[1] - Per Circular Ecology, ~70-90% of emissions are from the cement production process, depending on the type of concrete and what the rest of the supply chain looks like.
[2] - This seems to vary depending on where the cement is being made — in Myanmar, for instance, it’s around 46%.
[3] - Another number where the sources often don’t agree with each other, see here, here, and here for estimates on annual cement production.
[4] - Concrete is roughly 10-15% cement by weight, depending on the strength of the mix, what other cementitious materials are being used, etc. An average value of 12.5% yields 34 billion tons, which we’ll knock down to account for other uses of cement (masonry mortar, grout, gypsum overlay, etc.) This roughly tracks with estimates from PCA (“4 tons of concrete produced each year for every person on Earth”), and from the now-defunct Cement Sustainability Initiative, which estimated 25 billion tons of concrete against 3.125 billion tons of cement in 2015.
[5] - See here, here, and here for an estimate of total civilization mass flow. This doesn’t (I believe) include waste byproducts, which can be substantial — for instance, it doesn’t include the ~46 billion tons of CO₂ emitted each year, or the 16 billion tons of mine tailings, or the 140 billion tons of agriculture byproducts (though this last number is difficult to verify and seems high).
[6] - We see something similar with cement as we do with other bulky, low-value materials, in that it's made in lots of distributed manufacturing facilities relatively close to where it’s used. See here for a map of cement plants in the U.S. around 2001, for instance.
[7] - For China’s total floor space, see here (most sources seem to agree with these numbers). For U.S. floor space, see my Every Building In America article. For per-capita living space in Europe, see here.
[8] - The often high rates of cement use by middle-income countries have led some folks to develop a U-shaped cement consumption theory of industrial development — that countries start out using a small amount of cement, use more as they get richer and build up their physical infrastructure, and then eventually transition to using lower volumes of cement again. The Globbulk paper spends considerable time debunking this.
[9] - It’s not actually obvious to me what the substitution ratio would be. In strength-governed cases, you’d need proportionally more timber than concrete, but in other cases (such as replacing concrete walls with light-framed stud walls), you’d probably use less. Obviously, you can’t substitute all concrete for wood, but you can probably switch out more than you think — there’s no reason you couldn’t use wood foundations instead of concrete ones in many cases, for instance.
[10] - 30 billion tons of concrete is roughly 12.5 billion cubic meters, and total annual wood products produced is currently around 5.5 billion cubic meters.