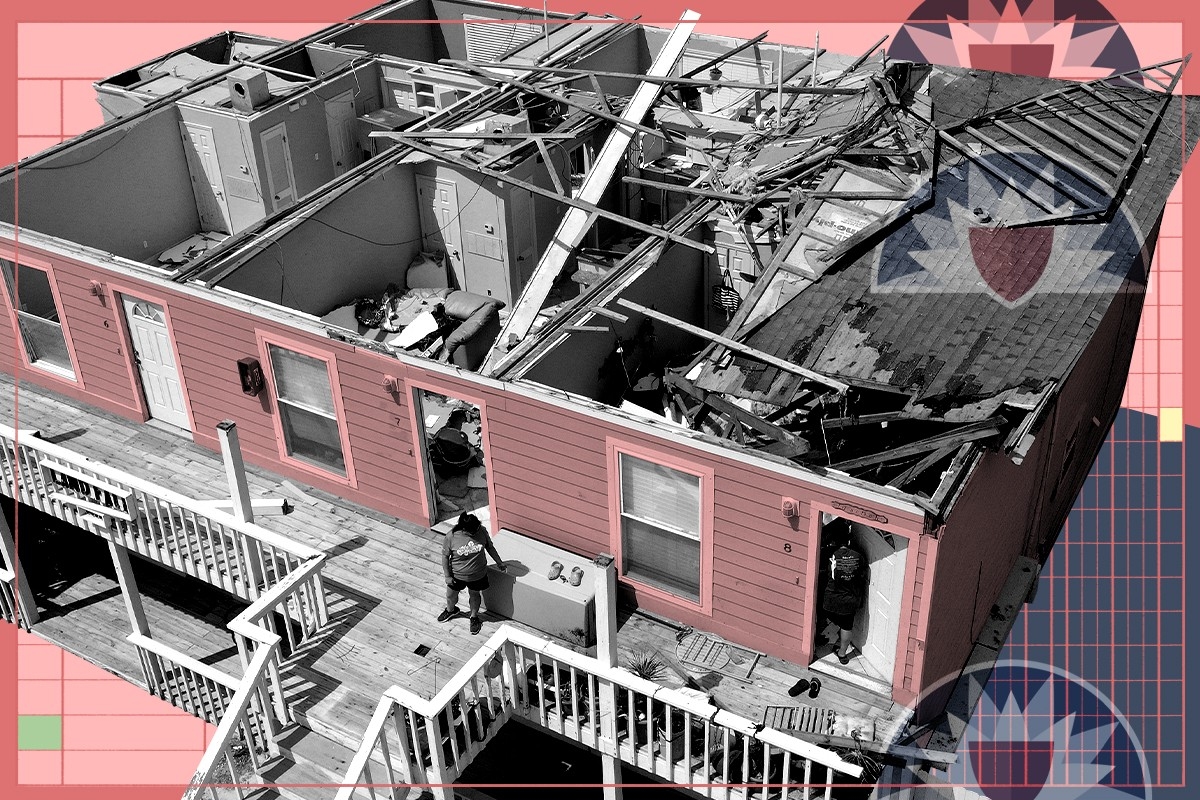
The Florida insurance market took another hit this week when Farmers announced it would pull out of the state, leaving around 100,000 customers unable to renew their policies.
While the news garnered headlines, it was exceptional not so much for Farmers pulling out, but for how long the insurance giant had stayed in the Florida market. Other national carriers had long since left and remaining Florida-specific carriers have been suffering under the weight of the state’s dangerous weather and uniquely lawsuit friendly legal environment.
At the same time that Farmers announced its departure, records were being set for ocean temperature in Florida, crossing 90 degrees in the waters off the southern part of the state. And the state may be in for nasty storms later this year. Forecasters at Colorado State University last week projected an “above-average” Atlantic hurricane season .
Farmers’ departure from Florida is also just the latest example of a major national carrier leaving a large, disaster-prone state. Allstate and State Farm said earlier this year they were leaving the California property market.
Farmers “looked at their book and determined they needed to reduce their catastrophe exposure. Most national carriers made that decision a long time ago,” RJ Lehmann, editor-in-chief and senior fellow at the International Center for Law and Economics, told me.
Customers with Farmers-branded home, auto, or umbrella insurance will not be able to renew their policy as their terms expires. The changes will not begin to take effect for 90 days.
“This business decision was necessary to effectively manage risk exposure,” Farmers spokesperson Trevor Chapman said in a statement. The company will continue to offer insurance through other brands it owns, Bristol West and Foremost.
The future of Florida’s insurance industry could be a harbinger for the rest of the country as it deals with extreme weather exacerbated by rising temperatures. Florida is a tough insurance market for the obvious reasons — property damage caused by wind, rain, and flooding from tropical storms (not to mention wildfires and tornadoes) — as well as its unique (although changing) legal environment.
While more and more of Florida’s insurance business is being taken on by the state-run Citizens Property Insurance Corporation, some followers of the state's economy are cautiously optimistic that insurers could eventually return to the state. But that return would likely be conditioned on a market and legal environment far more friendly to insurance companies, one with high premium and reduced rights for policyholders. After all, Florida’s high insurance rates have hardly stopped people from moving in, but the combination of extreme weather and high homeowner insurance rates could put the Florida dream of home ownership in America’s tropical climate out of reach for many.
The legal environment is changing thanks to reforms of Florida’s uniquely insurance company-unfriendly litigation system that have been signed by Governor Ron DeSantis over the past few years. This included eliminating Florida’s distinctive “one-way” attorney fees set-up, whereby if a policyholder won any amount of money from an insurer, the insurance company would pay attorneys fees for both sides. This system was obviously disliked by insurance companies, who argued that it led to the flowering of a Florida-specific cottage industry for trial attorneys; while those attorneys argued it gave policyholders a shot in prevailing against well-funded insurance companies.
Another bill banned the practice of letting policyholders “assign” the right to pursue a claim — and sue insurers — to contractors, another practice blamed by the industry for increased litigation.
Florida had over 75 percent of homeowners’ lawsuits in the country as a whole, despite only having 7 percent of the homeowners’ insurance claims, according to data from the Florida Office of Insurance Regulation.
Jeff Brandes, a former Republican state legislator who has long advocated to litigation reforms, predicted that the legislation, which was passed in April, will take somewhere between 18 and 24 months to have an effect on the market.
“I fully expect three-five companies to pull out and rates to go up 10 to 15 percent next year,” Brandes said, although he noted that he expected rates to stabilize in 2025.
In February, the St. Petersburg-based United Property & Casualty Insurance Company was deemed insolvent by state regulators. Some 15 insurers became insolvent between 2020 and the end of 2022.
Since 2016, Florida property insurance companies have been losing money on their underwriting — premiums collected minus claims paid — and only in the first quarter of this year did the industry as a whole turn a net profit, and that was thanks to investment earnings; underwriting profit was still negative.
Even if insurers return to the state, that doesn’t mean that said insurance will necessarily be attractive to homeowners: Part of why a less litigation-friendly market may be tempting to insurers is the very high rates that Florida policyholders pay for home insurance.
Average premiums in the state range from $1,651 in Sumter County in Central Florida to as high as $5,665 in Miami-Dade or $5,710 in Palm Beach, according to the Florida Office of Insurance Regulation. The nationwide average is around $1,900.
“We’re getting to a place where the availability problem will get better,” Lehmann said. “The affordability problem? We live on a low-lying peninsula with some of the most hurricane prone waters in the world.”


 The Smith Mountain Project, a 600-megawatt pumped storage facility in Virginia. Education Images/Universal Images Group via Getty Images