You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
A conversation with a long-time watcher of the PJM on its new proposals

America’s largest electricity market, the 13-state PJM Interconnection, is being forced to rapidly redesign how it works in order to meet its own reliability goals while trying to meet new demand from data centers and electrification.
The market has been in a multiyear rolling crisis as its auctions for capacity — the commitment generators can make to being available in times of high demand — hit a legal cap, resulting in billions of dollars of payouts from customers, leading to higher electricity prices in states like New Jersey.
Much of these payments are due to current and future demand from data centers, some $29.4 billion in the last four capacity auctions, according to the market’s independent monitor.
At the same time, the system isn’t able to procure enough capacity to meet its reliability goals, leading to tongue lashings and even threats of intervention from the Federal Energy Regulatory Commission, whose chair, Laura Swett, now regularly criticizes PJM in her public appearances.
On Monday, the market released a series of proposed reforms and initiatives to bring on new generation and attempt to make up for its reliability gap. This includes a supposedly one-off procurement of new capacity later this year that had been requested by the region’s governors and the White House, a new registry of large loads, and a kind of connect-and-manage system whereby new large loads that don’t have their own capacity will face curtailment during times of high demand.
In a letter to stakeholders, the PJM board said that new large energy users could be increasing demand by up to 70 gigawatts by 2038 (its all time record demand is around 170 gigawatts) while some 15 gigawatts of generation have been retired in the last few years. This combination has “placed increasing pressure on the region’s resource adequacy position” and “requires decisive action,” the board said.
I spoke to Jon Gordon, senior director at the clean energy trade group Advanced Energy United and a longtime PJM watcher about the proposals.
This interview has been condensed and edited for clarity.
Let’s start from the beginning: what was announced on Monday evening?
Just backing up a little bit, PJM has had two critical issue fast-path processes to try to determine how to protect ratepayers from data center related costs. The first one began in the fall and ended in December inconclusively. Then they started another one, which also ended somewhat inclusively. So that put the ball in the PJM board’s hands to review all the data, all the information that had been proposed, provided, and discussed, and come up with a plan of their own. And so they have officially done so. What we saw announced yesterday was PJM’s plan that they need to file at FERC very shortly in order to allow that September procurement.
And this is the backstop procurement that they agreed to with the White House and the governors?
Yes, in concept. The details needed to be ironed out. This is the board’s official proposal and it’s not going to happen until FERC approves it all, and FERC is under a lot of pressure to approve this.
In the letter to stakeholders, they presented three things: the registry, the procurement, and their version of connect and manage. How do these three ideas interact with each other? Why are they all proposed together?
The backstop procurement is the process whereby data centers can enter into contracts for their own power generation, and once they can demonstrate that they have a contract for power, they can then connect to the grid under this new proposal, connect and manage. And the registry is the tool by which to keep track of all this stuff: who are the data centers contracted that are eligible for this process?
Because you need all this detail to know how to curtail them. They’re going to be subject to involuntary curtailment up until the time that they are able to meet all their own needs with their own power generation. Meanwhile, they’re going to be curtailed by the local distribution companies — but the local distribution companies don’t have all the data they need to know which customers can be curtailed. So that’s where the registry comes in. They’re all part of the same overall package.
Let’s talk through the process here. Say, you’re building a new large load, maybe a 150-megawatt or 200-megawatt data center trying to get started in PJM. Under this process, what are the kinds of the things you have to check through to interconnect, and how will it be different than a few years ago?
Let’s talk about what’s going to happen now under these new rules. They’re going to have to enter into a bilateral contract with a supplier to demonstrate they’re making a good faith effort to secure the generation they need to meet all of their needs at some date in the future. Once they demonstrate that to PJM, they will then go to the registry for the connect-and-manage process. Which means that until their generation is 100% up and running, they will be subject to involuntary curtailment.
Before all this, a data center would connect like any other customer to the grid and start drawing power and any costs PJM would incur to connect them to the grid would be socialized across all PJM customers. That’s what’s been happening for many years. Ratepayers are paying for data centers that have come online previously.
How does this interact with PJM’s interconnection reforms? Would this allow data centers to interact more quickly while protecting customers from price increases? This is the dual goal of the White House and FERC.
Where the interconnection process comes into play is for the generator that wants to enter into a bilateral contract with the data center. They’re the ones that have to interconnect their generation.
So that generator hopefully is already in the queue. If not, it’s going to be a long while before they’re actually serving power to anyone. The queue is still super important here in terms of how long that data center is going to be subject to voluntary curtailment. The slower the interconnection queue is, and the slower that overall process of building this new generation is, the longer those data centers are going to be subject to involuntary curtailment. My understanding is that a lot of data centers are not very happy about that.
Is this set of proposals biased in any way towards a particular type of generation?
On its face, it really isn’t. The data centers are free to contract with whatever generation source they like.
We know that many of the hyperscalers committed to meeting their data center needs with carbon-free energy. I’m hopeful they’re going to make an effort to contract to the extent possible with solar and battery resources.
But I am concerned that just the sheer magnitude of the need means we can’t avoid building a lot of new natural gas to meet all that load. We really had to bring all of that wind and solar online.
Even though those sources are going to be faster and lower cost than gas, their intermittent nature and the sheer size of what’s required is going to make that challenging.
What are the next steps here?
Everything we’ve been discussing is completely unprecedented and is happening in a timeframe that’s unimaginable. Three years ago if PJM tried to take on what they’re taking on, it would be a three or four year stakeholder process and it’s taking months.
With all of that said, everything we’ve just discussed, according to PJM, is temporary. It’s meant to be a stopgap to get this market rolling with data centers that are anxious to connect and move forward.
PJM is calling this reliability backstop a one-time procurement.
A lot of folks have said — and I agree with them — there will probably be more than one of these.
The other thing that’s going on is that PJM has begun a process to redesign their entire market structure, what they’re calling a holistic market review. That’s in acknowledgment that the capacity market is broken and is not functioning as intended.
That’s another stakeholder process underway. That’s another heavy lift, which they hope to have in place in 2027. By the time this whole backup procurement process is over, they hope to have a new market in place. That’s an incredibly heavy lift.

Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Current conditions: A new nor’easter is washing the ocean over North Carolina’s Highway 12 right as crews complete reconstruction on the Outer Banks thoroughfare following last month’s storm • After whipping Mexico’s Pacific Coast with heavy rains, Hurricane Trudy has weakened to a Category 1 storm • Super Typhoon Champi knocked out power for more than half of Guam before barreling toward the Philippines as a potential Category 5 storm.
Last week was the worst week for the tech-heavy Nasdaq 100 Index since President Donald Trump’s tariffs roiled the market in April 2025. The reason? Hotter than expected federal data on inflation fueled fears of an interest rate hike that could prove devastating to the buildout of artificial intelligence infrastructure. Investors were already worrying the physical investments would cost more than giants such as ChatGPT-maker OpenAI or Claude-creator Anthropic are set to earn. But on Monday, semiconductor makers such as Oracle, Intel, and Micron Technology rallied as the AI rout came to an end. Yet CoreWeave, the cloud-computing heavyweight that led the selloff last week, closed slightly lower. The issue, investors told CNBC, is the company’s debt load. “The market tends to get worried about companies that have refinance risk when rates are higher, and CoreWeave was a little bit of the poster child,” John Lloyd, global head of multi-sector and corporate credit at Janus Henderson, whose firm owns CoreWeave bonds due in 2031, told the broadcaster. “They need the debt markets in order to grow, in some form or fashion.” That CoreWeave came close to bouncing back at all comes down at least in part to Ark Investment Management chief Cathie Wood opting to buy about $12 million of shares in the company amid the market plunge last week, a play for which The Street notes she’s known. Notably, Oracle, which was previously dubbed the “canary in the coal mine” for concern over AI debt, closed just 1% higher before plunging in after-market trading.
Microsoft, meanwhile, pulled out a major data center deal in the United Kingdom to anchor Nscale Global Holdings’ debut facility in the country, located in Loughton on the outskirts of London. But The Wall Street Journal reported that power supply issues ultimately caused Microsoft to back out of the 50-megawatt project, highlighting how hyperscalers can throw a major data center complex into disarray even at a later stage in the development. Nscale’s upcoming $35 billion stock market debut rests, as The Information noted, on its ability to build data centers.
Amazon is backing a deal for another power plant built with X-energy’s next-generation reactors. On Monday, the high temperature gas-cooled reactor startup, in which Amazon took an equity stake two years ago, signed a joint development agreement with American Electric Power to evaluate a potential 960-megawatt project at a former coal site in Sullivan County, Indiana. In a press release, AEP CEO Bill Fehrman said Amazon’s support provided “all necessary capital protections and financial safeguards that we have said are essential for any potential nuclear project to move forward.” That’s a notable departure from the line many utilities executives share in private, which is that — absent some kind of federal cost overrun insurance — building new reactors will prove too difficult a sell to shareholders. It’s part of a string of nuclear deals for Indiana, which currently has no operating atomic power reactors in its borders. On Monday evening, AtkinsRealis, the developer behind Canada’s signature CANDU reactor technology that can run on raw uranium, announced a memorandum of understanding to build up to 6 gigawatts of the pressurized heavy water reactors in Indiana. The state and the utility Hoosier Energy are the counterparties to the agreement.
In Arkansas, meanwhile, Google unveiled a new “enhanced partnership” with utility giant Entergy to power the tech giant’s West Memphis campus. As part of the agreement, Google pledged to support solar, battery, and transmission investments in Arkansas that the companies said would deliver “at least $500 million in new savings for all customers.”
Secretary of Energy Chris Wright called out New York Governor Kathy Hochul for holding up a natural gas pipeline he said would lower heating prices for residents in the Northeast as early as winter of 2028. During an appearance Monday on the Fox Business Network, Wright touted his agency’s decision last week to award Williams Companies $42 million through the wartime Defense Production Act to speed up construction of the Constitution Pipeline. “We wanted to get this in by winter of 2027 but delays and still opposition from energy-subtraction Democrats has unfortunately slowed the effort,” Wright said. “The delay right now is the governor here in New York State. We’ve been talking with her. We hope she’ll go along with this. Maybe after the election, I think she will.” The governors of all six New England states, he said, “are all on board with it.”
In a statement to me, Hochul spokesperson Ken Lovett called the announcement “nothing more than a political ploy to divert attention from Trump’s tariffs and his reckless war in Iran that have not only failed to bring down prices as the president promised, but have dramatically driven up home energy costs and gas prices at the pump.” He added that, “while the president continues to obsess over blocking renewable energy projects in order to focus on gas, oil, and even coal, Governor Hochul is focused on driving an all-of-the-above energy strategy designed to keep the lights on and costs down for New Yorkers.”
Sign up to receive Heatmap AM in your inbox every morning:

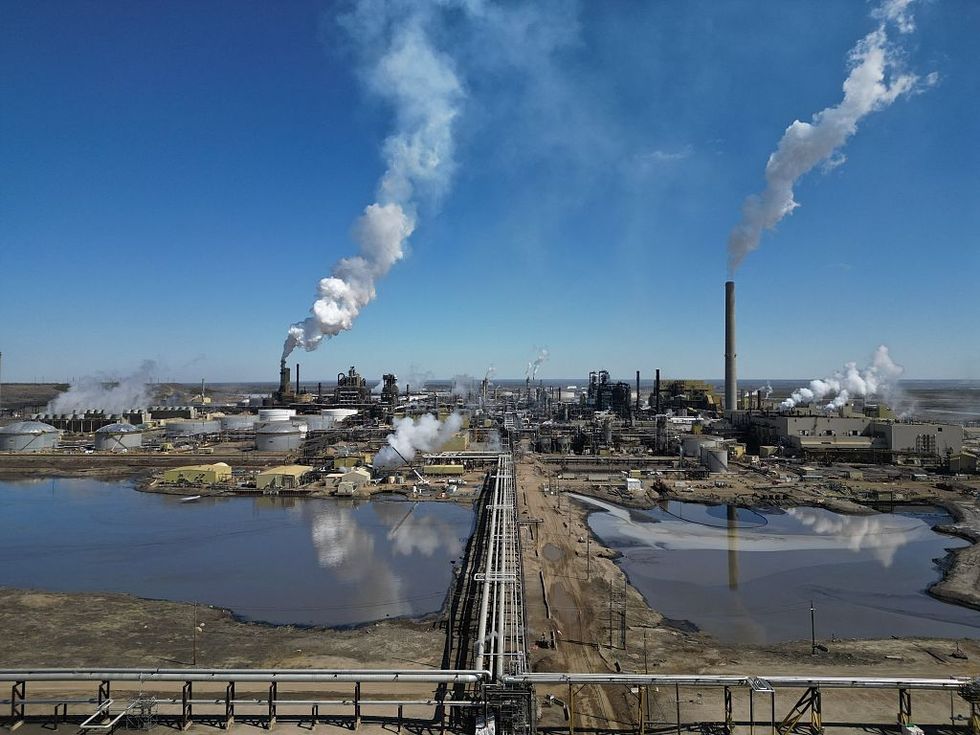
Albertans are the richest Canadians on average, thanks to the province’s oil and gas industry. They’re also — after the Quebecois, of course — among the Canadians with the strongest claim to a distinct identity from the national Anglo norm, often drawing comparisons to Texans within the U.S. Monday offered the biggest test yet of just how differently Alberta sees itself. Turns out whatever regional resentments Albertans may have against Ottawa after a decade of Liberal Party rule that frequently sought to restrict the oil and gas sector hasn’t been enough to merit secession. Voters overwhelmingly rejected a nonbinding referendum calling for a real vote on whether to split away from Canada and establish an independent Alberta. At least part of the reason may be that Prime Minister Mark Carney has put a new focus on beefing up Canada’s domestic energy industries in a bid to increase exports and make the country less reliant on an increasingly aggressive U.S. That includes building new pipelines. But a new analysis by Reuters warns that a successful infrastructure buildout won’t lead to another jobs boom in oil. Much of the growth in oil sands output, instead, “is likely to come from automation and efficiency gains rather than large-scale hiring,” the newswire reported, citing industry forecasts and nearly a dozen interviews with company officials, workers, politicians, and academics. Carney admitted as much when asked by the reporter during a visit to Alberta’s Fort McMurray this month: “I wouldn't use the term ‘boom.’ I would use ‘sustained growth.’”
Europe, meanwhile, is trying to keep its own populist blowback to rising prices contained. Right as violent protests over cost of living spread from France to Italy, the Italian government has struck a deal with the European Commission that Prime Minister Giorgia Meloni expects to slash household energy bills ahead of next year’s elections. Under the agreement, according to the Financial Times, Italy will be allowed to compensate gas-fired generators to keep wholesale electricity prices from rising above €59 per megawatt-hour, roughly $66. The European Union’s market rules require that the last and most expensive source of electricity tapped to meet demand serves as the wholesale price. But the EU’s executive chamber allowed for Italy to ease its rules after prices surged 45% higher than in nuclear-powered France and renewables-rich Spain last month.
China’s exports of solar panels fell 6.4% last month compared to the same period last year, according to Reuters. That marks the fifth straight year-on-year decline in 2026. It’s a sign that China is cracking down on its glut in solar manufacturing. But Beijing isn’t looking to lose its edge over the fastest growing electricity source in the world. Last week, Bloomberg reported that China had added 12 pieces of solar-related manufacturing equipment to its list of items restricted from export. That could make it much more difficult for U.S. manufacturers comply to stand up factories given the Trump administration’s 232 import restrictions on Chinese solar equipment, which take effect later this year. The results of the Department of Commerce’s Section 232 investigation into polysilicon, which my colleague Emily Pontecorvo and I covered here, are meant to be the Trump administration’s lifeline to solar manufacturers who lost a key incentive when federal tax credits expired, ending a bonus program for developers that use domestically-made panels.
One area where China has appeared to be gaining an edge — green hydrogen production — may still remain a competitive industry for Western manufacturers. Chinese electrolyzers, the machines needed to separate the H from H2O with electricity, cost less than half of those made outside the country, according to data from the International Energy Agency. But trade levies erase much of that advantage, ultimately reducing capital expenditures by only 8% for European projects using Chinese equipment, Hydrogen Insight reported.
Call it mine-to-battery manufacturing. As demand for batteries booked, Ivanhoe Electric had planned to differentiate itself by taking a fully integrated, farm-to-table approach, owning and operating its own copper mine, refining the metal, and ultimately turning that copper into cathodes for batteries all at its same site in Arizona. Now, however, there’s an even bigger sector demanding copper: Data centers. New data center projects are driving so much demand for copper that the company is considering selling its copper to buyers other than itself, Bloomberg reported.
The company simplifies the process of getting consistent, apples-to-apples bids.
With commercial electricity prices steadily climbing, many businesses and real estate owners are increasingly eager to generate and store their own power onsite, cutting their bills and making costs more predictable. But figuring out whether solar and storage can actually pencil out — and under what conditions — can be a nightmare. Ask a handful of developers for a quote and you might get a rooftop solar array from one, a ground-mounted solar and battery system from another, and a gas turbine from a third, each with its own size, price, and financing terms.
That leaves buyers comparing apples to oranges. And for businesses evaluating a portfolio of potential projects, the process gets even messier. “These are very local-centric systems. Different interconnection requirements, different permits, different suppliers,” Gareth Evans, CEO of the onsite energy planning and procurement startup Veckta, told me. “There are hundreds of solar developers in every state.” The hard part, he added, is “knowing what supplier to go with, how to ask them the right questions in the right language, in the right format, so that you’re getting consistent bids back that you can compare and contrast.”
That’s the tension San Diego-based Veckta has built its business around. And on Tuesday, the startup announced an oversubscribed $11 million Series A to scale its solution. Origin Ventures led the round, with participation from others including the climate-focused investor VoLo Earth Ventures, which led Veckta’s $3.3 million pre-seed round in 2022.
The company starts with a single input: a property address. Veckta’s software analyzes over 5,000 data points, including utility rates, grid emissions, outage risk, local equipment and construction costs, and available incentives to assess — in under a minute — whether an onsite energy project makes financial sense. That helps buyers define their needs, from system size and installation type to contract terms, and ensures that potential suppliers are bidding on the same requirements. The result is a set of comparable proposals, without the upfront cost of hiring a consultant or supply chain expert.
Veckta’s platform includes more than 3,000 vetted suppliers. As bids come in, the startup automatically compares them based on factors including the supplier’s track record, warranties, equipment offerings, compliance with foreign entity of concern requirements, and ability to leverage federal and local incentives. From there, Veckta makes its recommendations. “Supplier A is your best option if you want U.S.-made equipment with the longest warranty, best guarantee, and they’ve done these projects before,” Evans explained, by way of example. “Supplier B is disqualified because they’ve never done a project in your state.”
Out of the roughly 34,000 customer sites Veckta has analyzed, Evans said 37% would see positive returns today by installing solar panels, battery storage systems, or both. That translates to $3.1 billion in potential project value, concentrated largely in markets with high electricity rates such as the Northeast and California, and among businesses facing steep peak-demand charges. But as utility rates continue to rise and installation costs fall, he expects onsite power to become cost-competitive with the grid at “almost 100%” of sites within five years. The startup estimates that would unlock a whopping $12 billion in potential project value.
Veckta wouldn’t capture all that itself, of course. Rather, it generates revenue in two ways: buyers pay an upfront platform fee, and the winning supplier pays a success fee once a contract is signed. Evans told me the startup has been net profitable for the past year, though he would not share specifics. So far in 2026, customers have signed contracts for onsite energy projects at 128 sites. These typically range from 250 kilowatts for businesses like car dealerships and retail stores to 10 megawatts or more for manufacturing facilities, warehouses, or cold storage facilities. “That ranges from Fortune 500s right down to your individual business owner,” Evans told me.
With this latest raise, Veckta plans to expand its supplier network and grow its sales, marketing, and customer support teams. It also wants to help customers capture additional revenue streams from their onsite energy systems, such as by connecting them with demand-response programs, using batteries to provide grid services like frequency regulation, and selling renewable energy credits.
Named customers include rental car company Enterprise Mobility, real estate investment trust Regency Centers, and auto dealership group Lithia & Driveway. About 80% of the projects the platform facilitates today involve rooftop solar paired with batteries, but the company has begun to branch out.
“We’ve done waste-heat-to-energy, we’ve done EV chargers, done backup generators, and then the latest is, we’ve just finished our first pilot on roof replacements,” Evans told me. “We are firm believers that for any complex purchase that is a non-commodity that you can’t just buy off the shelf, we are best placed to help our customers competitively source those deals.”
The Iran war has been a gift to the country’s vehicle, solar, and battery business.
This is Heatmap Daily, a weekday evening digest written by our executive editor.
Happy Monday and welcome back. For months now, we’ve been talking about how the U.S. and Israel’s war in Iran has been a boon for electric vehicles, clean energy, and (unfortunately) coal.
But today we got data that confirms: This clean energy export boom is not just a side story. It is one of the brighter spots in the overall Chinese economy, which remains the world’s second largest.
According to economic data released on Monday, China grew 4.5% during the summer quarter as compared to the quarter from a year earlier. That means the country will likely hit its growth target this year, albeit on the low end.
The country’s economic expansion wasn’t driven by domestic consumption, however. Consumer confidence remains low, and residential investment has yet to return after the property crash earlier this decade.
Instead, booming exports are now driving China’s economy. Exports were more than 36% higher in September than a year earlier, driven by chips, ships, electric vehicles, and solar panels and batteries. The country will likely record its biggest trade surplus ever this year.
Some of those categories are clearly flourishing thanks to the global AI boom — think chips and even batteries. But the preponderance of vehicle exports suggests surging oil prices aren’t hurting. Sales of ‘new energy vehicles,’ a category that includes 100% electric vehicles and plug-in hybrids, were up more than 13% on a year-over-year basis in September, according to the Chinese car manufacturer’s trade group. But exports of these vehicles are booming. Battery electric vehicles were up 130% last month compared to the same period in 2025, and plug-in hybrid exports were up more than 200%.
It’s interesting to consider how much the Chinese and U.S. economy are mirroring each other at this moment. Americans are dealing with a remarkable investment boom, which is buoying the labor market and stubbornly maintaining high inflationary pressure. China is struggling with deflation, and exports are its quickest path to growth. (Consumer sentiment in both countries, interestingly, seems to be in the doldrums, even though American consumers appear to be in much better shape.)
When thinking about what artificial intelligence could do for the United States over the next decade, some subject-matter prognosticators (and even some Anthropic employees) imagine a world of 4%, 5%, or even 7% GDP growth. Such a growth rate is difficult even to envision in the modern era, of course, and it seems like it could propel the U.S. economy to staggering prosperity.
I know better than to make a prediction about where we’re headed. But amateur economic commentators should keep China in mind, too: a country that dominates along many technological axes, but where the standard economic math of supply, demand, and consumer sentiment still holds. Except if the United States economy were to stumble, no exterior source of demand will come to our rescue.