You’re out of free articles.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
If it turns out to be a bubble, billions of dollars of energy assets will be on the line.

The data center investment boom has already transformed the American economy. It is now poised to transform the American energy system.
Hyperscalers — including tech giants such as Microsoft and Meta, as well as leaders in artificial intelligence like OpenAI and CoreWeave — are investing eyewatering amounts of capital into developing new energy resources to feed their power-hungry data infrastructure. Those data centers are already straining the existing energy grid, prompting widespread political anxiety over an energy supply crisis and a ratepayer affordability shock. Nothing in recent memory has thrown policymakers’ decades-long underinvestment in the health of our energy grid into such stark relief. The commercial potential of next-generation energy technologies such as advanced nuclear, batteries, and grid-enhancing applications now hinge on the speed and scale of the AI buildout.
But what happens if the AI boom buffers and data center investment collapses? It is not idle speculation to say that the AI boom rests on unstable financial foundations. Worse, however, is the fact that as of this year, the tech sector’s breakneck investment into data centers is the only tailwind to U.S. economic growth. If there is a market correction, there is no other growth sector that could pick up the slack.
Not only would a sudden reversal in investor sentiment make stranded assets of the data centers themselves, which will lose value as their lease revenue disappears, it also threatens to strand all the energy projects and efficiency innovations that data center demand might have called forth.
If the AI boom does not deliver, we need a backup plan for energy policy.
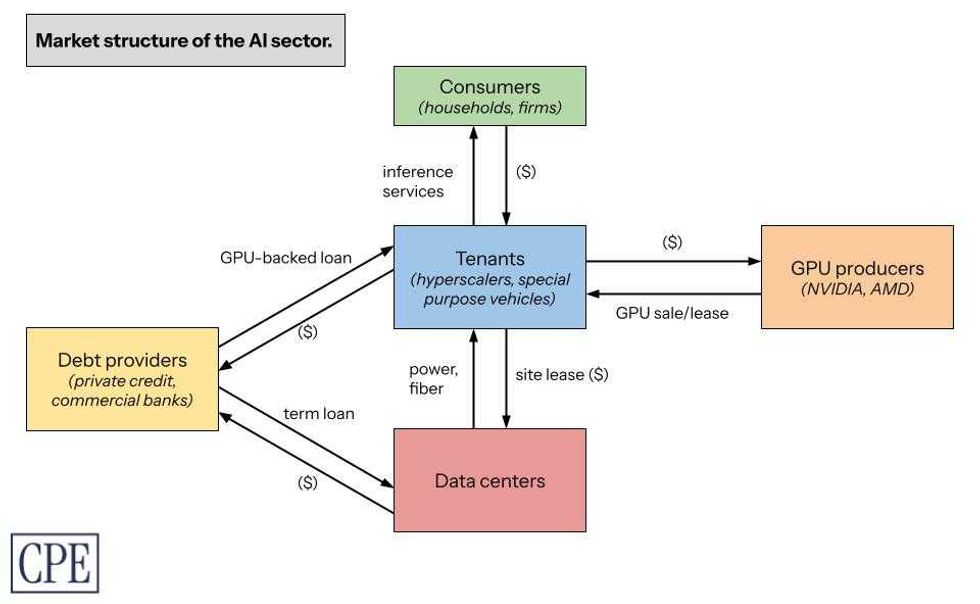
An analysis of the capital structure of the AI boom suggests that policymakers should be more concerned about the financial fundamentals of data centers and their tenants — the tech companies that are buoying the economy. My recent report for the Center for Public Enterprise, Bubble or Nothing, maps out how the various market actors in the AI sector interact, connecting the market structure of the AI inference sector to the economics of Nvidia’s graphics processing units, the chips known as GPUs that power AI software, to the data center real estate debt market. Spelling out the core financial relationships illuminates where the vulnerabilities lie.

First and foremost: The business model remains unprofitable. The leading AI companies ― mostly the leading tech companies, as well as some AI-specific firms such as OpenAI and Anthropic ― are all competing with each other to dominate the market for AI inference services such as large language models. None of them is returning a profit on its investments. Back-of-the-envelope math suggests that Meta, Google, Microsoft, and Amazon invested over $560 billion into AI technology and data centers through 2024 and 2025, and have reported revenues of just $35 billion.
To be sure, many new technology companies remain unprofitable for years ― including now-ubiquitous firms like Uber and Amazon. Profits are not the AI sector’s immediate goal; the sector’s high valuations reflect investors’ assumptions about future earnings potential. But while the losses pile up, the market leaders are all vying to maximize the market share of their virtually identical services ― a prisoner’s dilemma of sorts that forces down prices even as the cost of providing inference services continues to rise. Rising costs, suppressed revenues, and fuzzy measurements of real user demand are, when combined, a toxic cocktail and a reflection of the sector’s inherent uncertainty.
Second: AI companies have a capital investment problem. These are not pure software companies; to provide their inference services, AI companies must all invest in or find ways to access GPUs. In mature industries, capital assets have predictable valuations that their owners can borrow against and use as collateral to invest further in their businesses. Not here: The market value of a GPU is incredibly uncertain and, at least currently, remains suppressed due to the sector’s competitive market structure, the physical deterioration of GPUs at high utilization rates, the unclear trajectory of demand, and the value destruction that comes from Nvidia’s now-yearly release of new high-end GPU models.
The tech industry’s rush to invest in new GPUs means existing GPUs lose market value much faster. Some companies, particularly the vulnerable and debt-saddled “neocloud” companies that buy GPUs to rent their compute capacity to retail and hyperscaler consumers, are taking out tens of billions of dollars of loans to buy new GPUs backed by the value of their older GPU stock; the danger of this strategy is obvious. Others including OpenAI and xAI, having realized that GPUs are not safe to hold on one’s balance sheet, are instead renting them from Oracle and Nvidia, respectively.
To paper over the valuation uncertainty of the GPUs they do own, all the hyperscalers have changed their accounting standards for GPU valuations over the past few years to minimize their annual reported depreciation expenses. Some financial analysts don’t buy it: Last year, Barclays analysts judged GPU depreciation as risky enough to merit marking down the earnings estimates of Google (in this case its parent company, Alphabet), Microsoft, and Meta as much as 10%, arguing that consensus modeling was severely underestimating the earnings write-offs required.
Under these market dynamics, the booming demand for high-end chips looks less like a reflection of healthy growth for the tech sector and more like a scramble for high-value collateral to maintain market position among a set of firms with limited product differentiation. If high demand projections for AI technologies come true, collateral ostensibly depreciates at a manageable pace as older GPUs retain their marketable value over their useful life — but otherwise, this combination of structurally compressed profits and rapidly depreciating collateral is evidence of a snake eating its own tail.
All of these hyperscalers are tenants within data centers. Their lack of cash flow or good collateral should have their landlords worried about “tenant churn,” given the risk that many data center tenants will have to undertake multiple cycles of expensive capital expenditure on GPUs and network infrastructure within a single lease term. Data center developers take out construction (or “mini-perm”) loans of four to six years and refinance them into longer-term permanent loans, which can then be packaged into asset-backed and commercial mortgage-backed securities to sell to a wider pool of institutional investors and banks. The threat of broken leases and tenant vacancies threatens the long-term solvency of the leading data center developers ― companies like Equinix and Digital Realty ― as well as the livelihoods of the construction contractors and electricians they hire to build their facilities and manage their energy resources.
Much ink has already been spilled on how the hyperscalers are “roundabouting” each other, or engaging in circular financing: They are making billions of dollars of long-term purchase commitments, equity investments, and project co-development agreements with one another. OpenAI, Oracle, CoreWeave, and Nvidia are at the center of this web. Nvidia has invested $100 billion in OpenAI, to be repaid over time through OpenAI’s lease of Nvidia GPUs. Oracle is spending $40 billion on Nvidia GPUs to power a data center it has leased for 15 years to support OpenAI, for which OpenAI is paying Oracle $300 billion over the next five years. OpenAI is paying CoreWeave over the next five years to rent its Nvidia GPUs; the contract is valued at $11.9 billion, and OpenAI has committed to spending at least $4 billion through April 2029. OpenAI already has a $350 million equity stake in CoreWeave. Nvidia has committed to buying CoreWeave’s unsold cloud computing capacity by 2032 for $6.3 billion, after it already took a 7% stake in CoreWeave when the latter went public. If you’re feeling dizzy, count yourself lucky: These deals represent only a fraction of the available examples of circular financing.
These companies are all betting on each others’ growth; their growth projections and purchase commitments are all dependent on their peers’ growth projections and purchase commitments. Optimistically, this roundabouting represents a kind of “risk mutualism,” which, at least for now, ends up supporting greater capital expenditures. Pessimistically, roundabouting is a way for these companies to pay each other for goods and services in any way except cash — shares, warrants, purchase commitments, token reservations, backstop commitments, and accounts receivable, but not U.S. dollars. The second any one of these companies decides it wants cash rather than a commitment is when the music stops. Chances are, that company needs cash to pay a commitment of its own, likely involving a lender.
Lenders are the final piece of the puzzle. Contrary to the notion that cash-rich hyperscalers can finance their own data center buildout, there has been a record volume of debt issuance this year from companies such as Oracle and CoreWeave, as well as private credit giants like Blue Owl and Apollo, which are lending into the boom. The debt may not go directly onto hyperscalers’ balance sheets, but their purchase commitments are the collateral against which data center developers, neocloud companies like CoreWeave, and private credit firms raise capital. While debt is not inherently something to shy away from ― it’s how infrastructure gets built ― it’s worth raising eyebrows at the role private credit firms are playing at the center of this revenue-free investment boom. They are exposed to GPU financing and to data center financing, although not the GPU producers themselves. They have capped upside and unlimited downside. If they stop lending, the rest of the sector’s risks look a lot more risky.

A market correction starts when any one of the AI companies can’t scrounge up the cash to meet its liabilities and can no longer keep borrowing money to delay paying for its leases and its debts. A sudden stop in lending to any of these companies would be a big deal ― it would force AI companies to sell their assets, particularly GPUs, into a potentially adverse market in order to meet refinancing deadlines. A fire sale of GPUs hurts not just the long-term earnings potential of the AI companies themselves, but also producers such as Nvidia and AMD, since even they would be selling their GPUs into a soft market.
For the tech industry, the likely outcome of a market correction is consolidation. Any widespread defaults among AI-related businesses and special purpose vehicles will leave capital assets like GPUs and energy technologies like supercapacitors stranded, losing their market value in the absence of demand ― the perfect targets for a rollup. Indeed, it stands to reason that the tech giants’ dominance over the cloud and web services sectors, not to mention advertising, will allow them to continue leading the market. They can regain monopolistic control over the remaining consumer demand in the AI services sector; their access to more certain cash flows eases their leverage constraints over the longer term as the economy recovers.
A market correction, then, is hardly the end of the tech industry ― but it still leaves a lot of data center investments stranded. What does that mean for the energy buildout that data centers are directly and indirectly financing?
A market correction would likely compel vertically integrated utilities to cancel plans to develop new combined-cycle gas turbines and expensive clean firm resources such as nuclear energy. Developers on wholesale markets have it worse: It’s not clear how new and expensive firm resources compete if demand shrinks. Grid managers would have to call up more expensive units less frequently. Doing so would constrain the revenue-generating potential of those generators relative to the resources that can meet marginal load more cheaply — namely solar, storage, peaker gas, and demand-response systems. Combined-cycle gas turbines co-located with data centers might be stranded; at the very least, they wouldn’t be used very often. (Peaker gas plants, used to manage load fluctuation, might still get built over the medium term.) And the flight to quality and flexibility would consign coal power back to its own ash heaps. Ultimately, a market correction does not change the broader trend toward electrification.
A market correction that stabilizes the data center investment trajectory would make it easier for utilities to conduct integrated resource planning. But it would not necessarily simplify grid planners’ ability to plan their interconnection queues — phantom projects dropping out of the queue requires grid planners to redo all their studies. Regardless of the health of the investment boom, we still need to reform our grid interconnection processes.
The biggest risk is that ratepayers will be on the hook for assets that sit underutilized in the absence of tech companies’ large load requirements, especially those served by utilities that might be building power in advance of committed contracts with large load customers like data center developers. The energy assets they build might remain useful for grid stability and could still participate in capacity markets. But generation assets built close to data center sites to serve those sites cheaply might not be able to provision the broader energy grid cost-efficiently due to higher grid transport costs incurred when serving more distant sources of load.
These energy projects need not be albatrosses.
Many of these data centers being planned are in the process of securing permits and grid interconnection rights. Those interconnection rights are scarce and valuable; if a data center gets stranded, policymakers should consider purchasing those rights and incentivizing new businesses or manufacturing industries to build on that land and take advantage of those rights. Doing so would provide offtake for nearby energy assets and avoid displacing their costs onto other ratepayers. That being said, new users of that land may not be able to pay anywhere near as much as hyperscalers could for interconnection or for power. Policymakers seeking to capture value from stranded interconnection points must ensure that new projects pencil out at a lower price point.
Policymakers should also consider backstopping the development of critical and innovative energy projects and the firms contracted to build them. I mean this in the most expansive way possible: Policymakers should not just backstop the completion of the solar and storage assets built to serve new load, but also provide exigent purchase guarantees to the firms that are prototyping the flow batteries, supercapacitors, cooling systems, and uninterruptible power systems that data center developers are increasingly interested in. Without these interventions, a market correction would otherwise destroy the value of many of those projects and the earnings potential of their developers, to say nothing of arresting progress on incredibly promising and commercializable technologies.
Policymakers can capture long-term value for the taxpayer by making investments in these distressed projects and developers. This is already what the New York Power Authority has done by taking ownership and backstopping the development of over 7 gigawatts of energy projects ― most of which were at risk of being abandoned by a private sponsor.
The market might not immediately welcome risky bets like these. It is unclear, for instance, what industries could use the interconnection or energy provided to a stranded gigawatt-scale data center. Some of the more promising options ― take aluminum or green steel ― do not have a viable domestic market. Policy uncertainty, tariffs, and tax credit changes in the One Big Beautiful Bill Act have all suppressed the growth of clean manufacturing and metals refining industries like these. The rest of the economy is also deteriorating. The fact that the data center boom is threatened by, at its core, a lack of consumer demand and the resulting unstable investment pathways is itself an ironic miniature of the U.S. economy as a whole.
As analysts at Employ America put it, “The losses in a [tech sector] bust will simply be too large and swift to be neatly offset by an imminent and symmetric boom elsewhere. Even as housing and consumer durables ultimately did well following the bust of the 90s tech boom, there was a one- to two-year lag, as it took time for long-term rates to fall and investors to shift their focus.” This is the issue with having only one growth sector in the economy. And without a more holistic industrial policy, we cannot spur any others.
Questions like these ― questions about what comes next ― suggest that the messy details of data center project finance should not be the sole purview of investors. After all, our exposure to the sector only grows more concentrated by the day. More precisely mapping out how capital flows through the sector should help financial policymakers and industrial policy thinkers understand the risks of a market correction. Political leaders should be prepared to tackle the downside distributional challenges raised by the instability of this data center boom ― challenges to consumer wealth, public budgets, and our energy system.
This sparkling sector is no replacement for industrial policy and macroeconomic investment conditions that create broad-based sources of demand growth and prosperity. But in their absence, policymakers can still treat the challenge of a market correction as an opportunity to think ahead about the nation’s industrial future.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Heatmap’s latest poll adds urgency to one of the biggest questions questions facing the climate: Can the environmental movement come back?
Three years ago, I wrote a piece for this website about how I’d stopped openly describing myself as an environmentalist. Looking back at it now, it’s a bit of a head-scratcher: I love nature, conservation, and all things outdoorsy, and while I stand by my greater point — that we can’t let uncompromising ideals about the environment hold back renewable energy development — the truth is, I am absolutely an environmentalist. But saying so felt analogous to calling myself tender-hearted, naïve, and retrograde.
The truth is, most Americans are environmentalists, at least if you take a wide definition. In new polling and focus group research conducted by Heatmap News and Embold Research, nearly three in four registered voters (72%) told us “the environment” is extremely or very important to them personally. The environment, in fact, ranked a full 17 points higher than “climate change” in a battery of potential voter issues, despite the latter’s much more obvious existential threat. Even among the subset of people we labeled “skeptics,” for whom climate change was of minimal to no importance, a third (32%) still told us the environment matters to them greatly.
It’s no secret that “climate change” has fallen out of vogue; we’ve reported extensively on the rhetorical shift, including in coverage of our latest poll. But in a forced-choice test of three political messages, we also found voters preferred a hypothetical candidate who emphasized the environment while avoiding any words related to climate (38%, compared to 28% for a clean energy affordability message and 35% for an energy independence-focused message). Specifically, voters who picked our environmental message said they were drawn to its pitch for “cleaner air and a healthier environment for our families and communities.”
Given that the environment still seems to be a way for policymakers and communicators to reach people — including some of the most entrenched climate skeptics, who need the most convincing to back renewable energy — it appears to be a golden opportunity for a modern environmental movement to emerge and advance some of the overlapping goals of the climate movement.
But … where is it?
“As a movement, it’s semi-dormant,” John Reid, the founder of the Conservation Strategy Fund and the author of a recent Atlantic article on the decline of environmentalism in the United States, told me. The son of a Republican Senate aide who worked on the 1968 bill to establish California’s Redwood National Park, Reid stressed that environmentalism “was absolutely not a partisan issue in Congress” in the late 1960s and 1970s — what many consider the golden age of the movement, when clean air and water protections passed through Congress with conservative support. But the “trail started to go a little bit cold” under President Ronald Reagan, Reid added, calling him “the first president I’m aware of who put an anti-environmentalist in charge of the [Environmental Protection Agency]”: Anne Gorsuch.
When activists started paying attention to climate change and the fossil fuel industry in the 1990s, 2000s, and early 2010s, Reid said the movement began to shift away from its core themes of nature and conservation. “The kinds of solutions developed by free market enthusiasts isolated CO2 as a potentially investable, tradable commodity,” he said. “I think they got hyperfocused on carbon, and on the one hand it drew people who weren’t traditional environmentalists into the environmental debate — like Bill Gates and some pundits like Ezra Klein — but it’s also almost like they’ve never been on a hike before.”
The election of President Donald Trump, of course, added heretofore unimaginable headwinds to the environmental movement. Adam Rome, an environmental historian at the University of Buffalo, called the current federal situation “hopeless,” and told me he’s even seen the retreat from large-scope environmental policy play out in his classroom. Every year, he assigns students in his Environmental Movements course to organize a hypothetical Earth Day-like event to inspire people to action. “Just in the last couple of years, none of my students anymore had ideas at all about anything that you might remotely call politics,” he told me. “The thing that they were most excited about was, ‘Well, we could organize community gardens. That has a direct positive impact, and it can be a kind of consciousness-raising activity.’”
When Rome told me this, it felt drained of ambition — Really? Community gardens? But when I spoke to organizers at some of the country’s most prominent and historically influential environmental and climate groups about the state of the modern environmental movement, they framed it differently. Holly Bender, the chief program officer of the Sierra Club, told me that what inspires people and makes them feel agency is “not as much climate decisions” — which may feel far off or nebulous — “but this idea that the environment is close to home.”
Amy Moas, the climate director at Greenpeace USA, pointed specifically to how data center fights have become a new nexus of environmental action at the community level. “People are seeing the impact of environmental choices in their backyard, they’re seeing how it impacts their lived experiences, and they’re willing to stand up and fight for it.”
Kidus Girma, the campaign director at Sunrise Movement, told me that the youth activist network is now focused on finding “the most immediate and pressing thing” in people’s lives and “clarifying how it’s a climate issue.” He pointed to community resistance to data centers, which has risen in response to the idea that “a couple of tech billionaires [who are] able to radically reshape the American energy market in a couple of years, and what degree of local control folks should have about energy production,” but which people also oppose due to concerns about electricity and water use.
Girma sees the climate and environmental movements as deeply intertwined but ultimately separate — however, each can be considered the umbrella under which the other nests. If anything, though, the modern environmental movement has only gotten wider: After seeming to reach its peak of influence in 2021 and 2022, the Sunrise Movement has since reassembled to take on the Trump administration more explicitly, including patrolling for Immigration and Customs Enforcement Officers in Minnesota.
“Environmentalists understand that the forces in the federal government that are sending troops out to arrest and deport innocent people are the same forces that are destroying the environment and making climate change worse,” Aaron Sachs, an environmental historian at Cornell University and the author of the forthcoming book The Earth Is Ours, Not Mine: A History of Environmental Justice, told me. He added that the environmental movement at large is “so much more aware of intersectionality now,” and that organizers “don’t make the kinds of distinctions that older people might be tempted to make, which I think is a good thing.”
If our polling found the possibility of a cross-spectrum coalition under the banner of the environment, Girma has seen it in person in local data center fights. “We’re at the point where MAGA voters and lefty Sunrisers are strategizing together on how to get their county to make a different decision,” he told me. But others told me that part of the reason the environmental movement may seem absent from people’s minds right now is that “there are so many crises happening at the same time,” as Moas, the climate director at Greenpeace USA, said. Election corruption, concerns about AI, the Iran War, immigration — “there are too many issues for any one to be center stage,” she went on. “There are multiple ‘top priority’ issues.”
But to Reid of the Conservation Strategy Fund, it’s exactly this dilution of focus that is the core obstacle for the modern environmental movement. “It’s like a Christmas tree dynamic, where people get to come and hang whatever liberal cause they care about and act as if right-minded people should all be on the same side of all of these issues,” he said. He told me that strange bedfellows can come together on specific issues and make a change — like how onX, a popular mapping software among hunters, is currently galvanizing its members to oppose the rollback of the Roadless Rule. “If you think of alliances as Venn diagrams, insisting on near-total overlap will limit your allies to a number too small to make a movement,” he later wrote me in an email.
Whatever is holding back the modern environmental movement, it does not appear to be its ultimate underlying aim of protecting the planet. “If you drop the label ‘environmentalism’ and just ask people: Will my kids’ water be safe, or is the air going to make my family sick? — you get resonance from that,” Marc Yaggi, the CEO of Waterkeeper Alliance, told me. “I think that’s because people have learned to distrust the process, but not the goal.”
Our data seemed to back his view. When we asked voters why they haven’t done more to support clean energy, for example, just 7% (and only 16% of climate skeptics) said it was b ecause “I don’t believe in the goal.” Distrust in politicians and advocacy groups, the futility of the current political environment, and competing priorities (“other issues matter more to me”) all ranked higher.
“I really believe there is a whole lot of love and affection for nature and concern for environmental quality out there in the general public,” Reid said. “It may be quiet, it may be latent, it may get silenced by more immediate concerns that people have. But I do believe it’s out there.”
This new report is the first in a series of Heatmap reports on how American voters view climate, clean energy, and sustainability issues. If you'd like to receive our latest updates, downloadable reports, and invitations for special briefings, please fill out this form.
Current conditions: The Atlantic set a record on Saturday for the longest stretch of the hurricane season since the advent of satellites without a major named storm • Argentina is bracing for severe Zonda winds, a type of intense downslope gust unique to the eastern side of the Andes Mountains • While the wildfires darkening skies over Indonesia have receded, blazes are still raging across the southern shores of Sumatra, Borneo, and West Papua.
The United States is preparing to eliminate any cap on the amount of planet-warming pollution from burning coal or gas that power plants can spew into the atmosphere. On Sunday night, The New York Times reported that the Environmental Protection Agency planned to announce a final repeal of climate rules on the power sector at this week’s summit in Houston of energy ministers from the Group of 20 nations. The EPA already moved to remove the entire legal basis for regulating greenhouse gases at any level by gutting its endangerment finding, which my colleagues Robinson Meyer and Emily Pontecorvo explained last winter. In March, as I told you at the time, almost half of all U.S. states sued to block the administration from rescinding the finding. The EPA went on to scrap standards on climate-heating emissions for car tailpipes and loosened rules on heat-trapping chemicals used in refrigerators and air conditioners. Under the new proposal, which the Times noted would come out Monday, power plants would still face limits on mercury, arsenic, and other contaminants, “though the EPA has already loosened restrictions on how much mercury they can emit.”
Nearly a year ago, I told you about the legal challenges already mounting for President Donald Trump’s order to keep a Michigan coal-fired station open past its planned retirement date on the grounds that the broader grid system is under an “emergency” level of stress. Maintaining the J.H. Campbell coal station for just three months past its previously-agreed closure cost the utility Consumers Energy nearly $30 million. And all that was to fulfill an illegal order, a federal court just decided. On Friday, the D.C. Circuit Court of Appeals ruled against the Trump administration’s use of emergency powers to force the plant to stay open. The court found that the Department of Energy illegally invoked Section 202(c), the emergency authority of the Federal Power Act, to override the long-term planning process through which Consumers, Michigan, and the Energy Department had agreed to terminate power production at the 1.4-gigawatt plant. The agency has since used the same statute to order coal plants in Colorado, Florida, Indiana, and Washington to remain open. “The DOE needs to stay in its lane and use its emergency powers only in actual emergencies,” Michael Lenoff, Earthjustice attorney, said in a statement. “Preventing the market-driven retirements of coal plants to advance a coal-friendly agenda is not a proper use of emergency powers.” In July, Washington State announced a deal with utility TransAlta to convert the state’s only remaining coal plant to run on natural gas. But that same day, the Energy Department renewed its directive to keep TransAlta’s Centralia coal plant running for at least another three months. “America needs more reliable power, not less, and today’s order will help ensure reliable electricity generation remains available to help address periods of peak demand,” Secretary of Energy Chris Wright said in a statement at the same time. “The Trump administration remains committed to reversing the misguided energy subtraction policies it inherited from past leaders.”
The White House, meanwhile, is considering using the Defense Production Act to expand U.S. oil refining capacity. The proposal, reported by Reuters, came up during a meeting between Trump and a dozen U.S. refiners, who told the president that federal money “would be better directed toward making refineries more efficient or expanding existing plants rather than financing an entirely new refinery,” which would cost more and take years to complete.
A surge of utility-scale solar projects racing to completion before the federal tax credits expires in July added 11.4 gigawatts of capacity to the U.S. in the second quarter of this year, representing a 45% increase. That’s according to a PV Tech analysis of the latest Solar Energy Industries Association report I told you about on Thursday. Rooftop solar was a mixed bag in the second three-month stretch of 2026. Residential solar installations fell 12% year over year and community solar declined 14%, but corporate and industrial projects grew by 11%. Utility-scale projects, on the other hand, soared by 61% year over year. “The concentration on utility-scale developments was a direct response to the Trump administration’s phaseout of tax credits for renewable energy deployments from July 4, 2026 and the ‘safe harbor’ period that requires projects are placed in service,” PV Tech wrote.
Sign up to receive Heatmap AM in your inbox every morning:
Canadian Prime Minister Mark Carney instructed his special envoy to Europe to “scope out the most ambitious possibilities short of full membership” in the European Union or its common market, The Wall Street Journal reported Sunday. The details, the newspaper noted, “are still being sketched by technical working groups for what the prime minister has told his aides will be the reorienting of an economy and a society that for half a century has been dominated by the U.S.” If successful, the pivot to Brussels would reshape the energy and resource profile of both continents, pairing Europe’s wealth and vast population with Canada’s vast supply of oil, gas, and minerals. “In a more dangerous and divided world, Canada and our European partners are moving ever closer,” Carney said in a statement over the weekend. “Our shared values, complementary strengths, and common interests serve as the strong foundation on which we can build a stronger future. Together, Canada and our European partners have the ambition and strength to create a more just, stable, and universally prosperous world.”

Canada boasts the world’s second-biggest output of uranium, a potential boon to Europe’s nuclear sector. But with Kazakhstan, the world’s top supplier, cautioning that more of its supply could end up going to China and other new buyers, Australia — the world’s No. 4 supplier — is looking for a bigger stake in the world’s third-place producer, Namibia. A pair of Australian companies are pushing ahead with plans to build new projects in the southwest African nation, Bloomberg reported last week. Bannerman Energy and Deep Yellow are both based in the Western Australian mining hub of Perth. Bannerman is considering a joint venture with China National Nuclear Corporation in which Beijing’s state-owned reactor operator would buy a 45% stake in a mine and agree to buy 60% of its output once the project is commissioned in 2028. Deep Yellow’s nearby Tumas project is, per the newswire, “a little less advanced but targeting a final investment decision toward the end of the year.”
China’s wind turbine champion, Goldwind, is getting into another green sector. The world’s largest turbine manufacturer shipped its first batch of green methanol from a 160-megawatt project in Inner Mongolia to South Korea, where it’s expected to be shipped to a buyer in the EU, Hydrogen Insight reported. It’s yet another sign of how China is stepping up to meet the EU’s carbon tariff.
Even the hardiest are shivering at the price of heating oil.
As leaves begin to turn from green to autumn hues of amber, gold, and brown, New England is preparing for an expensive winter.
While most of the country heats their homes with natural gas or electricity, about 5 million households — overwhelmingly located in the Northeast — use oil. Like diesel and gasoline (both of which have set price records recently) home heating oil is distilled from crude oil, which is currently trading at prices not seen since the early months of the war between the United States, Israel, and Iran.
Benchmark oil prices are over $100 for the first time since the spring as the Iran War grinds forward with no end in sight. Houthi attacks on Saudi oil tankers and infrastructure in and around the Red Sea and continued Ukrainian drone strikes on Russian refineries have put added pressure on U.S. facilities to supply the world with gasoline, jet fuel, and diesel, raising prices domestically. Russia’s own fuel imports reached a record 172,000 metric tons in August, according to an analysis from the Centre for Research on Energy and Clean Air, mostly from South Korea and India, putting further strain on the global market (the country was once the largest exporter of refined products).
The effects have trickled downstream to the distillate market, as well. Diesel prices surged past $6 per gallon on Friday, while retail home heating oil prices in Maine, one of the Northeastern states most dependent on oil to heat homes, are around $5.39, their highest since April. Making matters worse, stocks of distillate fuel oil, which includes heating oil, are at their lowest level for this time of year since the Energy Information Administration started keeping records. The EIA released a new forecast this week projecting that “global production of distillate fuel will remain below last year’s levels in the coming months, contributing to low U.S. diesel inventories and high diesel prices.”
For Mainers and others across New England, that adds up to a hard winter to come.
“As the most heating oil reliant state in the country, Mainers are uniquely impacted by rising and volatile oil prices,” Acting Commissioner of the Maine Department of Energy Resources Celina Cunningham told me in an emailed statement. About half of the state’s residents “still rely on oil as their primary heating fuel,” she told me, even as outgoing Governor Janet Mills has encouraged heat pump adoption. “The cost of heating oil is already more than 60% higher than it was at this time last year,” Cunningham added, “putting added pressure on Maine households as we head into the winter heating season.”
Mark Wolfe, executive director of the National Energy Assistance Directors Association, told me that the total cost of heating a home exclusively on oil will jump from $1,740 to $2,297 this winter. “Families using heating oil will get hit twice — first from gasoline, and then heating oil,” he said.
The price of home heating oil has long been a hot button issue in New England politics, and this year’s slate of Congressional races is no exception. Matt Dunlap, the state auditor and Democratic nominee in Maine’s Trump-voting 2nd Congressional District, told reporters earlier this week while standing in front of a heating oil delivery truck that “right now, families across this district are sitting at their kitchen tables signing their heating oil contracts for the winter and staring at numbers they simply cannot afford.” In keeping with Trump’s recent admonition to pretend he’s on the ballot, Dunlap used the occasion to criticize the president’s foreign policy. The Iran War, Dunlap said, “is not an abstract foreign policy debate. That’s the reason your heating bill this winter could be hundreds of dollars higher than it was last year.”
Susan Collins, the Republican senator running for re-election in Maine, regularly highlights her role in bringing in funding from the Low-Income Home Energy Assistance Program for Mainers, even as staff in charge of administering the program were laid off early in the Trump administration.
To the extent New Englanders can expect any relief, it likely won’t come from the supply dynamics of heating oil — the EIA has upped its price forecast for both this year and 2027. They may, however, simply need less. Thanks to what could be an historically strong El Niño, New England may be in for a warmer (albeit wetter) winter than usual.