This transcript has been automatically generated.
Subscribe to “Shift Key” and find this episode on Apple Podcasts, Spotify, Amazon, YouTube, or wherever you get your podcasts.
You can also add the show’s RSS feed to your podcast app to follow us directly.
Robinson Meyer:
Hello, it’s Wednesday, October 7, and we have a permitting reform proposal. Last week, a gang of four senators, two Republicans and two Democrats, released the Bipartisan American Affordability and Jobs Act, or the BAAJA, as we’re calling it at Heatmap, BAAJA. Now, BAAJA would overhaul how the U.S. conducts environmental reviews and permits large-scale infrastructure and energy projects. It would encourage states, utilities, and grid regions to build more transmission. It would make it much easier to build geothermal energy in this country. It makes a huge number of changes to U.S. environmental energy and climate law, and we are not talking about it on this show. We are covering it right now at heatmap.news. I’m going to stick some links in the show notes and we will talk about it on this show. We have so many episodes planned, they’re going to be great. But this show is about batteries. This show is actually a long form interview with someone who I think has one of the most impressive resumes in the battery world today. But before we get there, I want to talk about the two big trends in batteries and especially in the American battery sector at the moment. The first trend is that the EV market is deteriorating. I’m not sure if you saw, but automakers really didn’t sell a lot of EVs in the third quarter of 2026, which just ended at the end of September. GM sold 25,000 EVs in Q3. Ford sold just 6,000 EVs. And some of the models from those two companies that were long awaited, such as the Chevy Bolt, this was the sub $30,000 inexpensive hatchback. It’s made in the U.S. People were really excited for it. GM actually initially just limited its production run to 150,000 units. Well, since the beginning of this year when the Bolt went on sale, it has sold just 8,000 vehicles. So a fraction of its initial production run. GM’s going to probably have to cut that production run even shorter. Rivian, by comparison, is clearly doing well. It sold 19,000 vehicles in Q3 of this year. It was its best quarter ever for deliveries. And that was all due to the debut of its new, more affordable SUV, the R2.
Robinson Meyer:
At the same time, as the U.S. EV sector is going through a rough patch, which is partially, by the way, because these EV tax credits went away. It’s also because a number of new EV models are coming out next year. So we’re kind of in a lull. But at the same time as all that is happening, the data center boom and the return of load growth is boosting batteries of all kinds. It is a great time to be making batteries in the U.S. as long as you’re not making them for cars, because nothing incentivizes production like demand. And there is huge demand for lithium ion batteries. Now, a number of companies have been left in the middle. They’re trying to navigate those trends. GM, for instance, has retooled some of its EV battery production lines to now make batteries for the grid. My guest today is in charge of navigating those trends and figuring out what comes next. He has, as I said, one of the most impressive resumes that I think you can have in the U.S. battery sector. He started his career at Panasonic in 1993, where he led the battery research lab and worked in lithium-ion batteries. In 2006, he went to Tesla, where he led Tesla’s battery cell development team and helped build the first Gigafactory. He was then vice president at Sila, a silicone anode producing startup here in the U.S. And then since February 2024, he’s been vice president of battery and sustainability at GM.
Robinson Meyer:
His name is Kurt Kelty, and we have a great conversation on today’s show. We talk about manufacturing generally, how the U.S. battery manufacturing sector should look, and how companies should be structured to compete globally, even though they’re making batteries for a mostly U.S. audience. It’s about the state of battery technology today and where it’s going. I learned a lot from this episode. I think a lot of Shift Key listeners will enjoy it. Unfortunately, we recorded it right before the Q3 data came out, so we didn’t get a chance to talk about that. But I think we talk about a lot of other things that you will enjoy. I’m Robinson Meyer, the founding executive editor of Heatmap News. All that and more. It’s all coming up on Shift Key.
Robinson Meyer:
Kirk kelty welcome to Shift Key.
Kurt Kelty:
Thank you, I’m excited to be here today.
Robinson Meyer:
I’m excited to have you. So you joined GM at this point, I think, two, three years ago. A lot has changed the auto industry at GM and, I don’t know, the entire U.S. energy sector since 2024. Give us a little bit of your background, what brought you to GM, and maybe what’s changed since you arrived.
Kurt Kelty:
Yeah, so I arrived, you said, two and a half years ago, but I’ve been in the battery industry forever, for almost 35 years at this point. I joined Panasonic in 1990, back in Japan, and worked for a cell manufacturer essentially for 15 years. I joined Tesla in 2006. I was employee number 50 or 60 there, and led the battery team there for 11 years. After that, I joined up with Sila, a silicon carbon material company, so a material supplier to the industry, a startup, and then I joined GM after that. Been in the battery industry for a long time, seen it from different angles, from a material supplier to a cell manufacturer to an OEM. I’ve really seen it from various angles. The problems we’re challenged with are very similar to the beginning. The beginning, it was how do you extend the runtime of a camcorder? That was kind of the big thing. Now we’re trying to extend the range of vehicles, and we’ve got our Silverado now at 492 miles, which is just crazy to think about how far we’ve come in these last 30, 35 years.
Robinson Meyer:
It’s interesting you mention that, because I think of this as key to the emergence of the Chinese battery industry, is that it begins as a personal electronics, starts by making lithium-ion batteries for personal electronics, and then that scales. Obviously Tesla huge in this story as well scales to delivering vehicle mileage and all sorts of other you know energy storage needs at all sorts of other scales I guess what’s striking to me is that even here in the kind of U.S. version of the battery industry that is still part of your experience and everything that we’ve been working on even in the U.S. side of the industry is still built basically on on personal electronics.
Kurt Kelty:
No, you’re absolutely right. When I was in the business in the early 90s, it was all electronics. The main drivers, I mean, camcorder was really the first usage of lithium-ion cells, but the battery business was driven by laptops, power tools, and cell phones. Those were the three drivers of the business. And it’s one of the reasons why the battery industry took off in Asia is because the electronics market was there. It was in Asia. And so it’s really important to have that proximity in developing new products. And you get R&D engineers from the cell phone makers working with the battery guys on a regular basis. That’s how you get really faster innovation. And so the Japanese were leading at that point. And then as Korea kind of got bigger and bigger into the small electronic items, then Korea started to take off. And then gradually that shifted to China. And then the battery industry went to China with them. And what’s interesting now is that we now have an EV industry that’s driving the demand around the world, including in the U.S. And so now we have, they have the customer here for the battery industry. So it’s ripe for the battery industry to be developing here in the U.S., to have manufacturing here, to have R&D here. We’re finally at that point because we just weren’t making the appliances, the applications before. And now we are.
Robinson Meyer:
It seemed to me that the story, right, of batteries emerging basically from electronics, from camcorders, from laptops, and then giving birth to a vehicle sector, or then informing the work of a vehicle sector and becoming a vehicle sector, is like a classic case of disruption. And the fact that now we’re trying to scale up in the U.S., a battery sector in part, you know, because it competes with the existing vehicle sector and because it’s a really important input into the existing vehicle sector and kind of the next big vehicle technology that is To some degree, the challenge that I think the U.S. is still trying to overcome is there really is not a domestic electronics manufacturing operation. There’s semiconductors, but there’s not a final assembly or battery domestic industry here. And that is like remains the challenge that the U.S. EV industry has to overcome.
Kurt Kelty:
The EV market is much, much bigger than anything the electronics industry ever provided. I mean, if you look at the demand for cell phones and laptops and combine it all together, it’s absolutely time.
Robinson Meyer:
On like a kilowatt hour basis?
Kurt Kelty:
Yeah. So to give you an example, when we decided to get into manufacturing of cells at Tesla, this is in 2013 is when Elon and I and JB made the decision to make cells at the Gigafactory. We’re going to make 35 gigawatt-hours for Model 3 alone. That was the plan. The industry at that time, including all the electronics and everything, was 35 gigawatt-hours. So we were going to double the market size with one vehicle. And we did it. But that gives you an idea of where it is. And to put that in perspective today, so our Ultium factories, our joint venture with LG, we’ve got two factories here. In the U.S., and last year we were the largest producer of cells among any of the OEMs, each one of those factories can produce 40 gigawatt-hours. And so going back, the electronics market is tiny compared to what we can do in the EV market. We could do the whole electronics industry, most likely, in one of our Ultium factories.
Robinson Meyer:
Oh, that’s interesting. And so to some degree, the U.S. kind of scaling up the electronics industry wouldn’t be a question of battery capacity, like manufacturing capacity anymore, because it’s all here.
Kurt Kelty:
But now that we have that industry here, we have the end customer here, we can actually now, there’s opportunity for us to be a big developer and commercializer of battery cells. And there’s really two things that are necessary to enable a country to really take a leadership role there. And the first part is you have to have that demand. We’ve got the demand. The second thing you need is you need that facility capability to develop new technologies and to commercialize them and to make them. In the U.S., we’ve got a rich history of developing all the battery technologies here, in combination with Canada, LFP was developed here, NMC was developed here, sodium ion, LMR. You can kind of go down the list. They’ve all been developed here, and they’ve just been commercialized over in Asia. And the reason for that is twofold. One is we didn’t have the demand here, which we just talked about. But the other thing is we didn’t have the capability here, neither the employees that would be necessary for that. The skill set, nor the facilities. And what we’ve done at GM over the last five years, we’ve invested over $900 million in these facilities that will take a new chemistry and bring it all the way to production. And that’s going to culminate in Q4 this year when we open up our battery cell development center, BCDC. We’ll open that up.
Kurt Kelty:
To producing our batteries. And this is the facility that enables the scale up of cells. And so if you look at it, there’s kind of three big chunks of it. There’s the first part that’s the R&D part of it, where you do basic chemistry R&D, you make little coin cells, little stamp size pouch cells. And then you go to the next step, which is what we do at our Wallace Center. And what we’re doing there is making full scale cells. So this would be very small volume, maybe a dozen a week or so, but we’re making them in the full size that would go into a vehicle. And we opened that about two years ago, two and a half years ago. And then what we’re opening in Q4 is something where we’re going to scale, where we can make thousands of sales a day. And we’re turning all the little knobs to figure out how do you optimize production here? How do you get a good yield? How do you optimize the production of this recipe that was developed in the Wallace Center? So we were missing that in the States. We didn’t have that kind of capability. We had the R&D, and we do great with that here in the U.S.. We have the best researchers, we’ve got the best labs, the universities, we got a startup environment that’s fabulous, the VC community. We do all that part great. What we were lacking was the other part, the taking it from the labs and commercializing it. And now there’s a first opportunity really we have where we’re going to have all of those key steps that will enable us to really take this from an idea all the way to production.
Robinson Meyer:
Okay. So you have anticipated like 10 questions that I want to get to later in the conversation, but I actually want to just come back first and start with what’s changed about your role in the past two and a half years, which is, I think when you joined, I mean, it was 2024, it was obviously all the original IRA tax credits still in effect. The current administration at the time was throwing the full weight of the federal government behind accelerating the EV transition as fast as it could go. Obviously, things have changed since then. And one of those things is this data center boom, which has totally changed with the market for energy storages. So how has your role changed in the past two and a half years at GM? And how has kind of GM’s role in the battery industry changed during that time as well?
Kurt Kelty:
Well, I mean, historically, GM worked closely with manufacturers in the battery industry, and we bought cells. That was the typical approach that we did in the early 2000s with the Volt battery pack as well, so in the 2010s. And then the decision was made, I think it was in 2017, 2018, to partner up with LG. And that was a really smart decision because GM didn’t know anything about cell manufacturing. And so now the partnership with LG really got us to a point where we could invest in factories. We own a 50% each. And it’s been a fabulous collaboration where we’ve been able to ramp up production. Our yield is among any best in the world on that. So that’s here in the States. So we’ve got two factories here and the yield here will match any in Korea or China, anywhere in the world. We’ll go head to head with them. So we’re doing very well with that. And these are making NMC pouch cells. That’s what we put into all of our vehicles. We’ve got one cell, one form factor that goes into each one of our vehicles. Now, since I’ve joined, we’ve made some pretty big changes in terms of the chemistry, the form factor, and where we’re actually developing these. So we made the decision last April, it was when we announced it, is we would go with LMR prismatic cells for our future. So that’s a huge change. We were using pouch NMC from before, and now the direction we’re going right now is a real focus on LMR, which was developed internally here at GM. We developed cells. We’re making cells with that. We got LG on board with that, so we’re now co-developing these LMR cells with LG. So that’s going to be really exciting for us because we’re driving down the cost of battery cells while increasing the performance.
Robinson Meyer:
I know what you’re talking about when you say LMR, but for listeners who may not, can you give us an array? It’s a battery chemistry. Can you give us an array of like what the battery chemistry is that GM is currently making now or currently uses in its vehicles? Sure. What the strengths of those different chemistries are.
Kurt Kelty:
Yeah, so generally the EV industry uses two chemistries right now. You have the high nickel or NMC, especially used in the West. And then you have the LFP.
Robinson Meyer:
And that’s like nickel, manganese, cobalt, right?
Kurt Kelty:
Yes, nickel, manganese, cobalt. And it’s got roughly 85 to 90% nickel. It’s really high in nickel. And nickel is the most expensive material that we’re putting in there. You really want to reduce the amount of nickel. But it gives you the energy density that you need. So you really stuff it full of nickel. So you’ve got a lot of that NMC chemistry. And then LFP is at the other end where it’s low cost, but it’s also low energy. And that’s what China is really focused on is that LFP. And again, it was developed here in North America and then commercialized in China. What we’ve got in our vehicles right now is...
Robinson Meyer:
I’m sorry, that’s lithium iron.
Kurt Kelty:
I’m sorry, iron phosphate. Yeah, lithium iron phosphate. Lithium iron phosphate. So NMC and LFP are the two main chemistries. We use NMC for all of our cells that are made in North America at our Ultium factories. The LFP we use in the Bolt. So we use it in just one program today in North America. So it’s generally used as that low absolute cost. When you’re really driving for low cost, that’s what you want to go for. Now, the LMR or lithium manganese rich chemistry, this is what was developed at GM.
Robinson Meyer:
I just want to make sure I understand something before we go on, which is the NFC is lighter, but it has more power. And it can exert more power at the same time. LFP, cheaper, but you can kind of X it because it’s so much cheaper that sometimes that has its own economy of scale and you can get a lot of range out of a heavier battery, right? Is this wrong? Yeah.
Kurt Kelty:
I want to differentiate between power and energy because they’re very different. So the NMC does not give you more power. The NMC gives you better energy. And when we speak of energy, it’s watt hours per liter or watt hours per kilogram, whichever way you want to look at it. But it’s that numerator, the watt hour, that’s really good with the nickel-based chemistries with the high nickel. The LFP on the other end has got the lower numerator. It’s got the lower energy, but at the same time, it’s got a lower cost. And cost we speak of in dollars per watt hour is what you would look at for cost. So LFP has got that lower cost, dollar per watt hour, and that’s why it’s really taken off in China is because it’s got that characteristic. But if you really want a vehicle to drive far, like our Chevy Silverado, you got to put high nickel in there. I’ll give you a comparison. So Silverado, we’re putting NMC in there. You get 492 miles of range. If we were to put LFP in there, we’d get about 350 miles. We’d save a bunch of money. We’d save like 10 grand on the battery pack. So it is a big savings, but it’s a trade-off. And batteries are all about trade-offs. You either want high energy or you want low cost. And then you also put fast charge in there. It’s kind of a triangle. It’s those three. Which do you want?
Robinson Meyer:
I mean, you’re describing a cost-related trade-off in that triangle right now, but is there a trade-off between energy and fast charge as well?
Kurt Kelty:
Yes. Yeah. So you can increase the energy and you can increase the fast charge, but it’s going to come at a cost. You can’t optimize all three. I mean, you can optimize all three, but you’re going to end up with a solution that isn’t the best on any category.
Robinson Meyer:
And before we move to LMR, my understanding is LFP, there’s no U.S. Company that makes LFP. Like that is where China has both kind of built its EV industry and also it remains, at least in terms of key midstream and assembly steps, really something that’s only done in China, right?
Kurt Kelty:
So over 90% of the LFP today comes from China. While saying that, we are also producers of LFP. So at our Ultium factories, we’re also making LFP there right now, selling it to LG for energy storage applications. So we just started that this year. And there’s very small production of LFP in the States. It’s almost insignificant today. If you look at monthly volume, we’re probably the largest now of producing that. But that’s for energy storage applications.
Robinson Meyer:
Yeah. And so even the kind of LFP and the Bolt, those are just imported packs that are put in the vehicle, right? Yeah.
Kurt Kelty:
Yeah. And you raised up a really good point here on the components here. So the cathode material, the iron phosphate, is the main driver of cost here. And in China, it’s a byproduct of titanium manufacturing. And so you get this product for almost free in China. And it’s just very difficult for anywhere else in the world to compete against free. If you’re going to compete head to head with China on LFP here in the States, I wish you good luck. It’s going to be challenging. The only way to do that is with tariffs, with production tax credits. There’s ways that you can compete. If you’re going head to head without any protection from the government, it’s going to be a tough battle.
Robinson Meyer:
It is funny, whenever we talk about these dynamics of the U.S. And China, China gets all these inputs into its production, quote-unquote, for free, because it’s getting them as byproducts of some other industrial process that it’s doing. It’s like this dynamic also exists in the U.S. It just exists like only for fossil fuels. Like we get all this free gas, quote-unquote, because it comes out with the oil. For Heatmap, which focuses on decarbonization, the energy transition, not necessarily the kind of free byproducts that we’re looking for in the industrial process. Let’s talk about the kind of next chemistry that you’re working on.
Kurt Kelty:
Yeah. So LMR, lithium manganese rich chemistry, has got something we developed over the last 10 years. The advantage LMR has is it uses much less nickel. So instead of using that 85% to 90% nickel, we’re in that 35% to 40% nickel. So it’s come way down. And as a result, we have much lower cost. So in the end, what you end up with is a battery cell that can compete with LFP on cost. If you were to make LFP here in the States and you compared it with LMR, it’s going to be similar cost on a dollar per watt hour basis. But the advantage is that the energy you’ll get is 30% to 35% greater. So if you go back to that Silverado example, the 492 miles of NMC, the 350 miles with LFP, with LMR, you’ll get about 420 miles. But it’s at the same cost as the LFP. And so that’s the real advantage of it is the performance versus cost. It’s a huge advantage. It’s not we’re off of that triangle where you have to do these tradeoffs. It’s a different triangle. So we’re able to get good energy at a low cost.
Robinson Meyer:
How soon would I be able to buy a GM vehicle with LMR batteries in it?
Kurt Kelty:
So, interesting timing. You’ll see an announcement in a few days on that. We are manufacturing LMR. We are planning to manufacture that in the States for our next generation EV vehicles. We’re going to be the first to market with it. And we’re on schedule with the development since we announced it last year. This is something that we’re really excited about bringing to market.
Robinson Meyer:
All these different chemistries were invented in the U.S. or by Western R&D labs, universities, companies, 20 to 30 years ago. And my understanding is LMR is the same, but it’s also an older chemistry, or it’s not a new chemistry, let’s say. It just has faced these production challenges or these kind of yield challenges or challenges inherent to the chemistry. So what’s been the hardest part of scaling up the LMR production and getting it to where it goes from the lab to it can actually be in vehicle soon?
Kurt Kelty:
So the LMR was first invented in, it’s kind of controversial, either Jeff Don’s lab or Argon. This is 20, 25 years ago. So it’s not a new chemistry. But what is new is what we’ve been able to do with it to increase the voltage that we’re charging to while still retaining cycle life and while reducing the impedance values. So that’s really the direction that we’ve gone. So we get a cycle life now that meets any kind of warranty requirements that we’ve got on the vehicle and all the performance requirements. It’s really a very good chemistry for applications that are the SUV or truck size, where you’ve got a little bit extra space in there so you don’t need that NMC, the highest energy density, and where you’re trying to really drive lower costs. And that’s what we’re really doing with this. It’s enabling us to get that really good range at a low cost.
Robinson Meyer:
It sounds like one of the ideas behind LMR is that you can leapfrog LFP, or at least it’s kind of the U.S. equivalent of LFP. Is there anything that keeps Chinese manufacturers from just going directly to LMR once the U.S. starts doing it at any real scale?
Kurt Kelty:
We do have patents on this. Combined with LG, we’ve got a pretty extensive patent portfolio, so that is one thing. But the bigger thing is, does it make sense for China to go down this LMR pathway? They don’t have the inherent advantages that they do in iron phosphate, where they basically have the free raw material. They’re going to have to go head to head with the rest of the world on the raw material there. If I’m in China trying to produce a sale, I would stick with what I can make incredibly cheaply. And that’s LFP. Now, for us, not only is it something that we can make and enable us really to leapfrog the Chinese in this, but the other thing is the supply chain here is domestic. That’s the key thing. is that for a lot of this, we can get the supply chain outside of China, and we can produce the cathodes here domestically. These materials are still coming from around the world, so it’s not necessarily sourced from the U.S. On the LMR. We can talk about sodium ion in a few minutes, which will be a little bit different, but we can source these outside of China, and we can be competitive with China with LMR.
Robinson Meyer:
Well, let’s talk about sodium ion, because my understanding is you’re also now producing sodium ion but much with LFP also primarily for grid scale use is that right?
Kurt Kelty:
So sodium ion, we announced in June that we’re going to start developing and then manufacturing sodium ion for the ESS market. And we’re going to do this in collaboration with Peak Energy. They are the ones that are making the system. We’re the ones that are making the cells for their systems.
Robinson Meyer:
ESS being grid and data center?
Kurt Kelty:
Yes. Thank you. Energy storage systems. And this is for grid stabilization. It’s for data center. It’s for backup. These are, imagine 20-foot or 40-foot containers just filled with batteries. You could put hundreds on a site. These are just massive battery packs, very different from an EV in the sense that they’re enclosed in a container. They’re expected to last 10, 20 years, and they’re used ideally on a daily basis. One of the biggest use applications is peak shifting, where you’re going to take that peak during the middle of the day of electricity demand, and you’re going to supply it from a battery. And then vice versa, when you have your peak production, when the wind is blowing high or the sun is shining, you’re going to use that to charge the battery packs. So that’s kind of the typical application.
Kurt Kelty:
And what we announced is that we’re going to use sodium ion instead of LFP. So LFP is the chemistry of choice. Again, the Chinese LFP being incumbent chemistry here. And what we’re going to do is, again, leapfrog them by using sodium ion. Now, what’s the difference between sodium ion and LFP? If you look at that just at the cell level, the cost of the LFP is actually cheaper than sodium ion. And it’s got higher energy density. So you say, wait a minute, why would anybody want to do sodium ion? And that’s why it was discounted by most researchers and companies until now. But what we’re doing with Peak is we’re developing a system and a battery that actually operates very effectively at high temperature. We’ll cycle these cells at 55 degrees C and they’re almost flat as a stone. The capacity does not degrade. And that’s the real advantage here is that you can get these things to last forever at a high temperature. What that enables is if you can last for a long time at high temperature, you don’t need to cool them. You can just let them rise in temperature. And well, if you eliminate the cooling part of it, the advantage there is that you have that initial capex costs that you eliminate from the cooling system. Your maintenance costs are much lower. One of the big maintenance issues you have is just cooling systems breaking down pipes, not connecting well to each other, leakage. So you eliminate that part of it. And then the parasitic load loss where you’re powering the cooling system. So you’re losing energy there. Another big thing is your round-trip efficiency is better by a couple of percent. So all these little things, they add up. So in the end, your total cost of ownership is lower. So that’s the big thing we’re going after in sodium ion versus LFP is you have a lower total cost of ownership. And we estimate it’s going to be roughly 20% lower than LFP over the life of a program.
Robinson Meyer:
I kind of alluded to it earlier, but this … utility scale business or the data center business was not around as far as I was aware of in 2023 I mean there were beginning you were beginning to see utility scale battery installations but the scrambling of grid operators and utilities and now hyperscalers to manage load growth it just wasn’t the same even a few years ago as it is now what does that mean to GM is that just like an important new source of demand and a big customer and you’re happy to meet that customer or is that does it allow GM to do something that it wouldn’t be able to do without this kind of scale of economic activity?
Kurt Kelty:
Well, one of the nice things about it is it leverages our skills. Our skills right now as a company are we can develop battery chemistries and we can bring them all the way from the labs all the way to production. Because we’ve got all that and it’s all in one campus. It’s all within walking distance of each other. Again, that proximity advantage that I mentioned earlier.
Robinson Meyer:
Was the Tesla Gigafactory like this or were you primarily focused on commercializing? You didn’t have this full vertical integration.
Kurt Kelty:
So the Gigafactory at Tesla was actually run by Panasonic within the Tesla roof, but it was Panasonic running it. The workers were not going across to the other side of the wall, even though it was the same building. Very distinct. It was production. Even Tesla today, where they’ve got their production in Texas, and they’ve got R&D in one location, Pilot in another location, Prototype. We’ve got everything in one location, which really gives us an advantage. Because you can imagine putting engineers together. I mean, I love doing this. Mixing in engineers with different backgrounds and putting a whiteboard in front of them. And I’ll tell you, magic just occurs when that happens. So we take full advantage of that. And going back to your question, like the sodium ion, what we’re doing is we’re in the ESS market in general. We’re taking advantage of these facilities that we have. It’s just perfectly designed for this. Let’s develop a new chemistry that is appropriate for this market. Let’s figure out how to manufacture it at volume. And that’s what we’re doing. And it’s an indication so far are really encouraging that we are, again, leapfrogging the competition. And it’s not only on the performance side, but this is a great domestic play because sodium, the source of that is soda ash. That’s available around the world. The U.S. happens to have the largest reserves anywhere in the world. It’s a great story in terms of not just performance and cost, but also the supply chain is a great story because we can really bring that whole supply chain to the domestic market here.
Robinson Meyer:
In 2024, GM retired the Ultium brand, except for the Ultium cells. And I would say that as an outsider, unlike other domestic automakers, the whole GM stack where you have a single battery kind of design that you then slot into different vehicles seems to be working and certainly seems to be producing profitable vehicles in a way that other automakers’ approaches were not. And so why retire the Ultium name? In traditional automakers, you talk about platforms and different cars designed on the same platform. But are there going to be a few platforms at GM, each with their own chemistry, and then you design different vehicles on top of that? Why get rid of Ultium when it seemed to be working?
Kurt Kelty:
Yeah, so the way I look at the future when EV volumes really start to ramp up, we’re going to need prismatic form factor, pouch form factor, cylindrical form factor. We’re going to need nickel cell, high nickel cells. We’re going to need some LMR cells. We’re going to need some LFP cells. We’re going to need it all. What we do here at GM is we design the right battery for the right application. And generally, depending on the need, you may need high nickel. You may need LFP. Most likely, you’re going to need LMR in most of our applications. That’s what we think. And in some cases, the prismatic form factor will work best. In other cases, the cylindrical form factor will work best. I do not see a future where we’re standardizing on a single chemistry or a single form factor. We tried to do that in the battery industry in the late 90s when I was in the business and all the laptop companies got together and said, we’re going to make a standard form factor, so we’re going to drive down costs. We made the form factor. Everybody signed up for it. Nobody used it, and nobody used it because it was the way to really customize your laptop was the battery. Everything else had been standardized. At that point they had the hard drive, you had the floppy and the screen, and all those were standard components. The battery was the way you made it custom, and with EVs, it’s the same thing. The battery is going to decide your driving range, your acceleration, your space in the car, your safety of the car. I mean, it just determines so much about how fast you can charge it. All these things are determined by the battery. And so you’re not going to see a standard. And so at GM, we are preparing for that by having this battery innovation center, this electrification powerhouse that we’ve got. It’s something that we’re really proud of. And in the future, we’re going to really take advantage of this.
Robinson Meyer:
You’ve used this term a few times, which is about yield from a factory. It’s the amount of successful batteries you’re able to produce in that factory, right? In the rate, the percentage of successful production, so to speak, but what determines yield for a factory? And is it different from, say, assembling engines or doing a different kind of commercial assembly or manufacturing?
Kurt Kelty:
Yeah, so a couple of things. First of all, batteries are chemistry versus an engine, which is much more mechanical. The basic difference starts there. The other thing is batteries, you have to make an absolutely massive amount of these things. You have to make hundreds of millions per year exactly the same, exactly the same. You cannot have a variance there because you could have a safety issue. So that’s another thing that differentiates them. If you look at The impact of it, the cost is dollars per watt hour, which we talked about earlier. And if you look at the cost that goes into a battery cell, one of the big components is depreciation of the equipment. And so it’s how much output you can get for that given amount of investment that you’ve made there. If you’re dropping down 1%, 2%, 3% versus others, your depreciation cost is going up. So that’s one part of the equation. The other part of the equation is when we look at yield, how much material goes into the factory versus goes out into a good cell. And so if you’re losing some of that material in process there due to failures or whatever else it is, that’s adding to your material cost. So it’s really critical to get that right. And the way you get that right is it’s a lot of little tiny tuning of knobs. I’m exaggerating here, but you basically, you’ve got your technicians on the line, and they’re tweaking their knobs ever so slightly to optimize it. And where you learn from that is you learn from scaling it up in a smaller scale first. So that’s what we’ve got in the BCDC that comes out in Q4. That’s where we’ve got the 100, 200 knobs, the little things that you’re making, these little incremental improvements. We’re getting that learning from BCDC and where we can do it on smaller volume. And then we can shift it over to Ultium for mass production.
Robinson Meyer:
What is another production process that it’s like, if any? Is it like semiconductors? Is there another product that has to be assembled like a battery?
Kurt Kelty:
You know, it’s interesting, the original battery companies were all tape companies like VHS that were making tapes because it’s a lot of winding is a basic technology that it comes from. And even today, we’re so much bigger than the tape industry now, but that’s where it originally came from. And today, the winding machines are, I think, the most interesting parts of the cell manufacturing process, where you could sit there and look at these machines and just be in awe because how fast and the precision that they are operating in to manufacture these cells. It just really is amazing.
Robinson Meyer:
But that would even be a Panasonic story, right? Because Panasonic would have been making tapes, right, before it was making batteries?
Kurt Kelty:
Absolutely. So back then, it was Panasonic, Sanyo, and Sony, and Toshiba. Those are the four companies that own 90-some-odd percent of the market, and they just crushed it because they had all that internal technology already that they extrapolated on.
Robinson Meyer:
We’ve been talking about a new facility that you’re about to open that’s going to allow for tweaking of production and allow what sounds like a vertically integrated battery production line from conceiving the chemistry or testing new chemistries to actually commercializing it. But what can the U.S. still not do in the battery market? Where are we still catching up? Is it in know-how? Is it in producing the machines that then produce the batteries? Where does the technology not exist here yet?
Kurt Kelty:
So we definitely have the know-how in manufacturing in terms of developing new chemistries. We’re still early stages of the know-how to manufacture cells. There’s a bunch of companies here in the States, and we’re now developing that capability. So we’re in a really good spot now there. I think the biggest challenge is the supply chain. How are we going to bring this supply chain over to the West? It just is clearly still dominated by the Chinese. And we need to figure out how do we develop that outside of China. Some of them may be appropriate for the U.S., some may be appropriate for Indonesia or Australia, you can imagine, but to get that supply chain so that we’re not dependent upon China.
Robinson Meyer:
What’s an example of a supply chain that we’re dependent on right now? I mean, are you thinking upstream or midstream or where are you thinking?
Kurt Kelty:
The biggest one right now is graphite. We’re totally dependent on China for graphite. And so give you another example, which is in sodium ion, hard carbon is used for the anode there. Instead of graphite, you use hard carbon. The Chinese have the capability to manufacture this. They’re limiting their exports right now. So because of that, the cost is very high for hard carbon. If a new company wants to get into that business, they can get into that. But you have to keep in mind that China at any point could flood the market. And so if you’re a startup here, It’s like, well, wait a minute, do I want to do that, get into that business? When I know that at any time China can say, okay, exports are okay now. You can go ahead and export to the U.S. So there’s things like that are difficult for the industry. That’s going to require really collaboration with the government. We need some kind of support there from the government in working on domesticating the supply chain for battery cells. I think that’s going to be a real important element going forward.
Robinson Meyer:
Are American companies as able to produce batteries as efficiently as they would be able to if more of those upstream components were here? By which I mean, I’ve heard that One advantage of Chinese battery manufacturers is they can work pretty closely with refineries or with their upstream providers and learn about the materials that they’re getting and also tailor the supply that they’re receiving to the products that they’re trying to make. It just seems to me like there would be a disadvantage for U.S. companies without having basically relationships with their commodity providers or input providers.
Kurt Kelty:
So this is a theme that we’ve hit on several times in this conversation, which I think you’re absolutely on target with this, is proximity matters. Being close together, having an ecosystem, having the whole supply chain vertically integrated in proximity to one another makes a huge difference. And so it’s important. Now, at GM, we’ve been investing in companies. Lithium Americas is an example of that. Where we’re investing in the supply chain. We’ve got countless examples of this where we’re either investing or we’re giving contracts to startups here in the States or working with the government to help have them help finance them. It’s really important for us to get that supply chain here domestically. So we’re really focused on doing that to try and enable that because it’s only going to now allow us to go faster. And we’re also doing this like with LMR. We had the first World Conference on LMR last year at GM, where we brought together all the developers of LMR last November into our Warren, Michigan facility. And we’re doing it actually again next month. We’re having our second annual LMR get-together, where it’s invitation only to certain companies that are really big impact players through the whole supply chain. We’re bringing them on-site so we can collaborate together. But right now, most of them are overseas. Ideally, in the future, it would be a whole domestic get-together. But we’re taking advantage of what we’ve got right now. And those cards are mainly overseas, outside of China.
Robinson Meyer:
I realize you’re not in a policy role, but if you had to choose between continued aggressive federal support for reshoring or nearshoring some of those inputs into battery production versus restoring some of the incentives for consumer EV purchasing, which one would be more helpful?
Kurt Kelty:
I’ll tell you, the way to have the biggest impact on the domestic battery manufacturing industry is by having high demand. If you get high demand here locally, that domestic manufacturing will follow very quickly. So it’s whatever will get us that demand. Now, how do we get that demand is your follow-up question. The way you do that is you make a compelling vehicle. And that’s what we’re really focused on here at GM is our next generation has to be that really compelling vehicle where customers just flock to it and say, that’s what I want because of performance and the cost. It is a challenging period right now because ICE vehicles, we make really great ICE products right now. And to compete against them is tough both on cost and performance. And so there is a period where it could be helpful working with the government to make it to enable greater demand than would naturally be there. But our focus on our team is, hey, forget about any kind of incentives or anything like that. Let’s just make just a kick-ass product and really make something the consumer wants to buy.
Robinson Meyer:
You’ve anticipated my final question. We began this conversation by talking about how a single Tesla’s single gigafactory or a single GM factory basically produces batteries at the scale that the old consumer electronics did, industry did globally. But it just seems to me when you think about, you know, U.S. Automakers competing with Chinese automakers or U.S. automakers competing, I think especially with Chinese automakers, that there is a demand and scale problem that ultimately the size of the U.S. Domestic market is just smaller than the size of the Chinese domestic market. And at this point, you know, Chinese automakers, as has been widely covered, are not just targeting a domestic market, they’re targeting a global market. And so to what degree is the primary obstacle to U.S. EV production, U.S. Battery production, just remain the scale of domestic demand and perhaps even the scale of the domestic U.S. vehicle market?
Kurt Kelty:
I can’t overemphasize how important it is to have that demand. And going back to your earlier question on the ESS market, that’s helping. Having this ESS market is certainly helpful, but it doesn’t replace the EV market. The EV market is many times bigger than you’ll ever get in the ESS market. I think the upside here is tremendous on the EV market side. Remember, we’re like a 5% or 6% market share on EVs right now in the U.S. For comparison, Europe’s at 29%. China’s way beyond that. I mean, if we can get this EV market up to that 20, 30% of the market, that’s huge. It will be getting so much more competitive as a result of that increased demand.
Robinson Meyer:
It’s funny that we were talking about at the beginning of this conversation, my conversation with Secretary Wright, and there were other questions I wanted to get to that I didn’t get to. And one of the questions was, in fact, sure seems like it would be helpful for everyone involved in U.S. energy policymaking if the EV share of U.S. vehicle purchases was higher than it is now?
Kurt Kelty:
Yeah. The battery industry here domestically is so important for economic security, for national security. I mean, we’ve got so much that’s dependent on it. You’ve got the electrical grid that’s dependent on it. You got your data center growth depending on it. You got transportation dependent on it. You got the defense related stuff like drones. I mean, It all depends on battery technology. You need this to be successful. And the best way to get better drone technology is to have better demand for vehicles. If you have more EV demand, that’s going to help you on the drones.
Robinson Meyer:
Thank you for coming on the show. When you announce the LMRs or when there’s a next fleet of vehicles, let’s have you back and keep it going.
Kurt Kelty:
Look forward to it. Thank you.
Robinson Meyer:
And that will do it for today’s show, but we’ll be back soon with a new episode of Shift Key, all about permitting reform. Until then, Shift Key is a production of Heatmap News. Our editors are Jillian Goodman and Nico Lauricella. Multimedia editing and audio engineering is by Jacob Lambert and by Nick Woodbury. Our music’s by Adam Kromelow. Thanks so much for listening. We’ll see you soon.

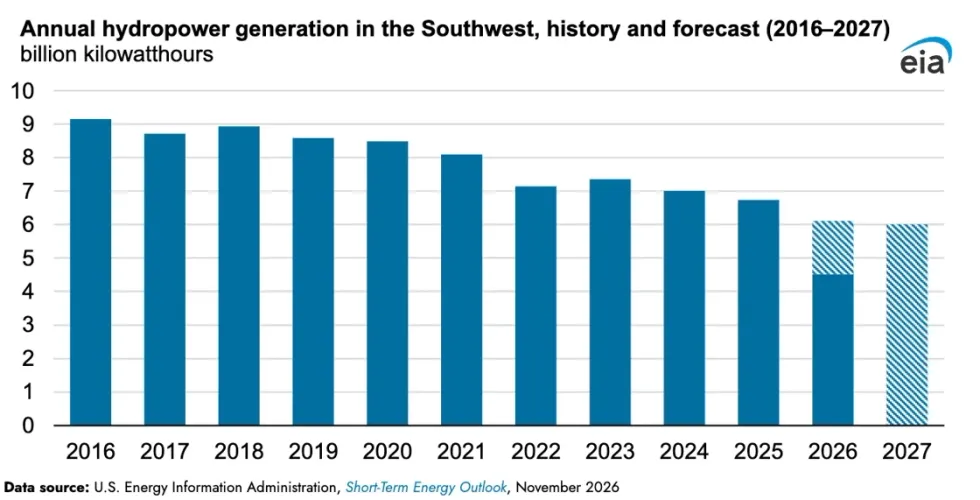 Evaporating. Chart: EIA