Robinson Meyer:
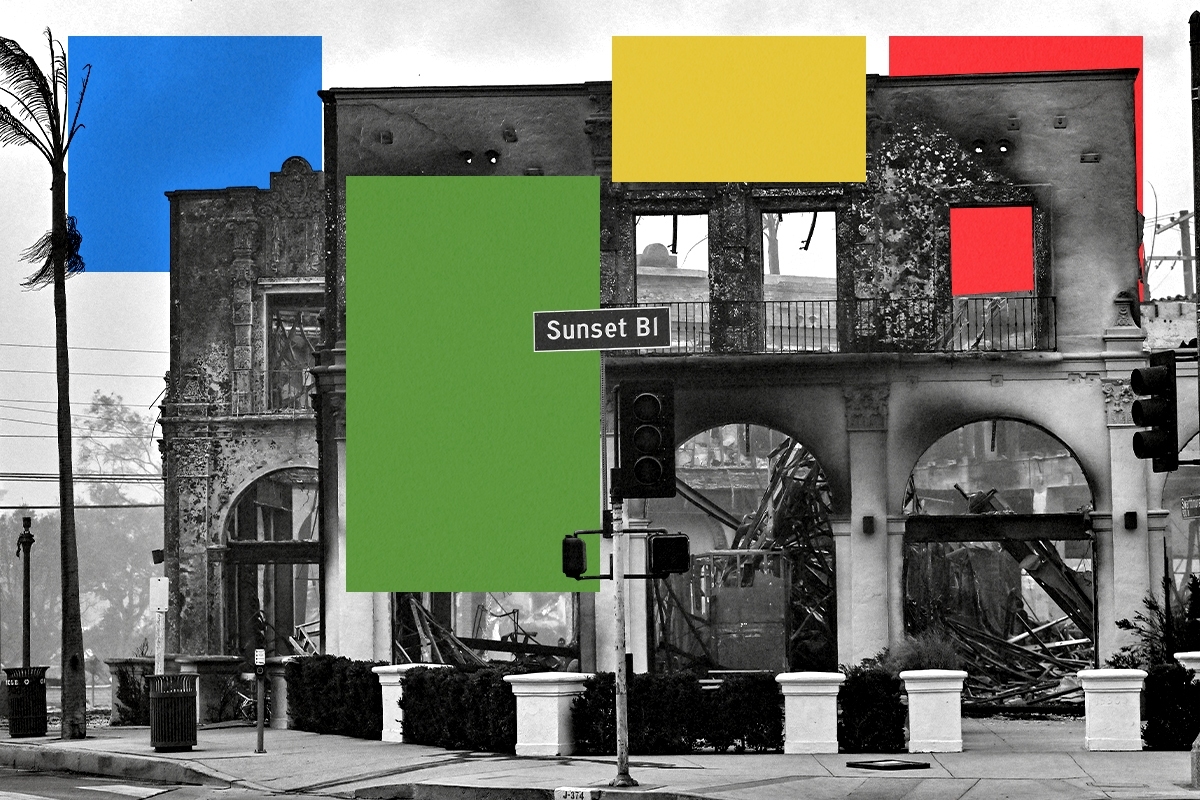
Hello, it’s Thursday, August 20, and we’re just a few months from the end of Gavin Newsom’s second term as California governor. He should be coasting to the finish line, maybe gearing up to run for president. But earlier this month, he took up a big legislative push, which, if successful, would be one of his last acts as governor. It’s to reduce how much California’s utilities pay for wildfires. Now, I realize that may sound arcane and maybe even surprising in a populist era. But as you’ll hear, it’s a policy with huge implications for the state’s economy, for its housing costs and for its electricity costs. California’s electricity costs, as you may remember, have surged in recent years and are now the most expensive in the continental United States. In fact, rates are rising in part because of the very dynamic we’re going to talk about today. And given that high power rates, expensive electricity keeps people from electrifying and switching to EVs, and given that California has the country’s most aggressive climate policy, and that wildfires are worsened by climate change, this is quite a messy and important problem. The stakes are very high.
Robinson Meyer:
Now, how did we get here? Before we get to our guests, I think it’s worth clarifying something about where all of this started. Under the California constitution, the state government has what’s called strict liability, meaning that if a piece of government infrastructure damages your property, then the government is responsible for paying for it, even if it wasn’t negligent or even necessarily at fault. Now, since 1999, as you’ll hear, that trait has applied to utilities too. And that means that if a piece of utility equipment starts a wildfire, even if the company was doing everything right and it had the best technology and it had cleared out brush near its wires, even buried the wires, then it’s very easy for that company to become wholly responsible for the wildfire. Well, what does that mean? Well, you’ll hear in a moment. But according to our guest today, it potentially raises electricity rates for California households by $300 to $500 dollars a year. Maybe you can see why Governor Newsom wants to fix it. Our guest today is Lauren Teixeira. She’s a senior analyst at the Breakthrough Institute and the author of a recent report called “Rewiring Risk,” which is all about this dynamic. We talk about how the state of affairs came about, how it might be remedied, and what it means for California’s economy and climate progress. I’m Robinson Meyer, the founding executive editor of Heatmap News, and you are listening to Shift Key. Lauren Teixeira, welcome to Shift Key.
Lauren Teixeira:
Thank you. I’m so happy to be here.
Robinson Meyer:
I think I’m thinking of this episode already as a sequel to an episode that we did a few years ago about why California’s electricity prices are so broken.
Lauren Teixeira:
That was a good one.
Robinson Meyer:
You came out of the report recently about how the legal system that governs California’s wildfires is broken. And we’re going to talk about the different ways that it’s broken, but how that’s now kind of starting to almost leak into the rest of the state’s governance and drive issues throughout the rest of the California economy. Can you give us, like, what is the status quo for how California pays for wildfires right now? And how is that different from maybe other states in the U.S.?
Lauren Teixeira:
So you can imagine that there’s a certain amount of wildfire risk. California has a lot of it because it’s a hot, dry place. And we have really extreme wind events. And combined with a large fuel buildup, things are going to burn. And so how we pay for that right now is weirdly through our utilities and through ratepayers’ electricity bills. And how that ended up happening is that... We have a unique legal doctrine. It’s called inverse condemnation with strict liability. And what this says is, as applied to utilities, it says if a utility happens to ignite a fire and it damages your property, the utility is liable for all of those damages. In other states apply this doctrine to utilities, but they don’t use a strict liability standard. They use a fault-based standard.
Robinson Meyer:
And so get into a little bit of the distinction there, because I think at first, that’s going to sound like very reasonable. That like, yes, of course, if a wildfire.
Lauren Teixeira:
That’s why we have it. Yeah, exactly.
Robinson Meyer:
If a utility starts a wildfire and then the wildfire burns down my house, then like, yes, of course, the utility should like pay to replace my house. That makes sense. And that also as a homeowner seems to me that it would do things like keep my home insurance cheaper, which I would like as a homeowner.
Lauren Teixeira:
Yes.
Robinson Meyer:
But can you maybe walk us into why this standard is not as simple as I have just described it?
Lauren Teixeira:
Yeah, so it sounds totally plausible. There are a couple of reasons why it is actually causing a lot of negative consequences. One is we should make a distinction between a strict liability standard and a fault-based standard. So fault-based standard says if the utility was negligent, they’re responsible for the damages. Strict liability says even if they were not negligent, even if it was a total freak accident and a palm frond from hundreds of feet outside the right of way flies into a power line, touches it, sparks a catastrophic fire in a wind event, the utility is still responsible for it. So that’s one distinction, and I think the latter is less reasonable than the former. The second is a little philosophical, and it has to do with, you could say, the causation, chain of causation for wildfires. Because at first glance, you’re saying, okay, a utility ignited a wildfire. It’s their problem. But let’s think about all the other things that contribute to wildfires. Fuel buildup. Whose fault is that? Is it the utility? No. You know, homes in high-risk areas, what facilitated that? In California, we can get into this. A lot of it was price controls on insurance. There’s also the failure of local governments to construct fuel breaks. You know, also climate change. It does contribute to wildfire. Exactly how much is, of course, a matter of enormous dispute and very hard to say. But yeah, so for that reason, it does not make as much sense as it would initially seem to place all of the liability on a utility.
Robinson Meyer:
So it almost seems like you’re getting into like different distinctions around the word ignite, right? Because there’s like ignite as in if I were to ignite a candle, I like take out a match and I like light the candle on fire. And then there’s ignite as in it seems like under the law, ignite for utilities means anytime a piece of utility equipment happens to intervene in a situation that then produces a wildfire. The utility is judged to have ignited the wildfire, even if the utility essentially did nothing wrong or acted in a very reasonable way. Is that like a correct summary?
Lauren Teixeira:
That’s correct. That’s the status quo. Yeah, it’s whoever started it pays for everything, even if it wasn’t their fault and it was a total freak accident.
Robinson Meyer:
What does this mean for California’s electricity system, for California’s economy, for the whole ecosystem of state policy that exists around wildfires and the utility system?
Lauren Teixeira:
So the first thing it means, and the reason why it’s getting a lot of traction now, is that it is the primary driver of our famous rising electricity rates, which are quite eye-popping and the highest in the continental U.S. The reason for those high electricity rates are qua wildfire is one, grid mitigation. So utilities invest exorbitantly in grid mitigation, which again sounds reasonable, but in fact, it’s possible to do it to the point of diminishing marginal returns. And the second is ratepayers are actually paying up front for people’s property damages through their bills. So what happens is utilities can get sued for the damages. The insurer goes to the utility and says, I represent, you know, this homeowner and I want the money and the utility pays out. And of course, those costs are passed along to ratepayers. Now we have a fund called the Wildfire Fund, which is created after PG&E went bankrupt in 2019. And that is something that is meant to keep utilities from going bankrupt ever again. It is capitalized in part by shareholders and in part by the rate payers.
Lauren Teixeira:
So the ratepayers pay into that. It’s a $21 billion fund that was recently depleted. The ratepayers also pay for self-insurance, utility self-insurance, because they need that money before $1 billion in damages. They cannot access the wildfire fund, so they need to make up that difference. So in short, ratepayers are paying billions of dollars in insurance and grid mitigation. Then there’s a hidden effect. So they pay up front for insurance, but then we should also think about what incentives does this create?
Lauren Teixeira:
As you alluded to before, this disincentivizes homeowners and municipal governments to invest in mitigation because they know that they can eventually get bailed out by a utility.
Lauren Teixeira:
The other issue is that we have price controls on insurance through this kind of strange system called Prop 103. And one of the only reasons insurers are staying in the state is that they have this recourse to subrogate and recover the damages. So we are essentially subsidizing wildfire risk through our utility bills in a lot of ways.
Robinson Meyer:
Okay, so, and my understanding, too, is like this only became a problem, I’m going to say recently. This wasn’t really an issue right until the campfire. Like this legal doctrine sat, kind of emerged on the books in what, the 1980s? And then it just was there for a while?
Lauren Teixeira:
1999, yeah. Okay. It was just there, yeah.
Robinson Meyer:
Tell us some of that story.
Lauren Teixeira:
So what happened is that there are nonlinear effects with, we call it the WUI. It stands for wildland urban interface. So there are nonlinear effects to this. And there also are to climate change and to fuel buildup. And in the 2010s, all of those things kind of broke. And there was the campfire, which PG&E equipment started, wiped out the town of Paradise. Extremely tragic. About 90 people died. PG&E went bankrupt from those damages. And what changed legally after that fire is lawmakers said, we can’t have our utility go bankrupt because we need electricity. So we’re going to start a wildfire fund to make sure this never happens again. And in order to get access to the wildfire fund, utilities have to show that they’ve done this whole menu of mitigations. And they are not going to take any risks there in losing access. They are going to err on the side of over mitigation so that’s why bills start skyrocketing a lot it’s not just capital expenditures they also do vegetation management which is incredibly expensive and also passed through in its entirety because it’s operational it’s not amortize it of.
Lauren Teixeira:
Course yeah yeah
Lauren Teixeira:
Insurance by the way it also counts as OPEX so that’s also passed so.
Robinson Meyer:
It just gets fully passed along too and it
Lauren Teixeira:
Sounds like.
Robinson Meyer:
Yeah so basically like almost rate payers aren’t only paying to like insure, quote unquote, utilities from the wildfires. They’re like paying like three different ways to do it. Is that right?
Lauren Teixeira:
Exactly. That is exactly right, Rob. And that is exactly the point I make in my report that that grid mitigation, the capex, which, by the way, has reached diminishing marginal returns, is in fact a form of insurance. And it’s also a huge subsidy to the 10 percent of people who live in the very high risk areas.
Robinson Meyer:
How did this emerge in the first place? Pre-Camp Fire, like 1999. Yeah. Can you talk about the 1999 decision?
Lauren Teixeira:
Yeah, it was a courts of appeal decision called Barham versus Southern California Edison. That’s the big utility in Southern California. And, you know, I’ve talked to Eric Biber about this, who’s a legal scholar and studies these things. And he was kind of just like, it kind of just made sense at the time, the interpretation. Most states do apply inverse condemnation to utilities, even though it’s not the government, because inverse condemnation is supposed to apply to a public use. However, they’re like, even though it’s private, electricity is a public use. We’re going to say that’s inverse condemnation. The strict liability standard is something that was kind of just how they interpreted it. They said, if it’s a public use and it’s a taking, we should socialize that among the public. Of course, usually when we socialize things among the public, it’s through the tax base, which is progressive, not the rate base, which is regressive. And what Eric said is he suspects if they had known, you know, what the consequences would be, they would not have made that interpretation. But that’s how the cookie crumbled.
Robinson Meyer:
Can you just talk through the different parts of that phrase? Inverse condemnation versus strict liability. What does that mean?
Lauren Teixeira:
So I’m not a legal scholar, but inverse condemnation is kind of the flip side of eminent domain, which I’m sure everyone is at least glancingly familiar with. Eminent domain says, you know, the government wants to build a highway. They’re going to take your property. If they’re going to do that, they have to compensate you justly and reasonably. Inverse condemnation says the government did a taking, but they didn’t pay you. So ex post, the government owes you money. So that’s how we get to this. And it’s not immediately obvious that that should be applied to utilities because they’re not the government.
Robinson Meyer:
Inverse condemnation is like initially designed for, I don’t know, maybe there’s some your property backs up to a military base.
Lauren Teixeira:
Yeah, a streetlight falls on your house or something.
Robinson Meyer:
A streetlight falls on your car. And now, obviously, the government has to fully pay you for the car. And it might not have, like, been the government’s fault that the streetlight fell. But the idea is basically if the streetlight falls on your car, they’re going to have to pay you for the car, even if they were doing an OK job of, let’s say, watching the streetlight.
Lauren Teixeira:
Well, no, usually the standard is negligence. And that’s what’s weird about California.
Robinson Meyer:
OK, so now explain strict liability to us.
Lauren Teixeira:
So it’s just a, you know, usually in tort law or, you know, the law of people harming others, you say that person owes me only if they were negligent. And obviously that will generate a lot of case law of what exactly was negligent. Strict liability says that doesn’t matter. Even if they’re crossing all of their T’s, dotting all of their I’s, they’re still liable. Got it. So that’s what we have in California. And we’re the only state that does that.
Robinson Meyer:
And is this applied to California’s government too, or is this only in the case of wildfires? Caused by public utilities?
Lauren Teixeira:
No, no. It applies to anything that could be a taking by the government. And then it was an extension of the doctrine to extend it to utilities because, again, they’re not public. So it’s not obvious it would apply to them. It’s a public use.
Robinson Meyer:
Yeah. Got it. Is the state government generally bound by strict liability?
Lauren Teixeira:
Yes. That’s the law of the land in California.
Robinson Meyer:
Yeah. I want to get into how this could be fixed and kind of what the way would be to fix it. But even though this legal doctrine has been on the books since 1989, the whole situation broke relatively recently because it like sat there. I don’t know, were utilities worried about it? It seems like probably not.
Lauren Teixeira:
No, they had. They’d sued many times to try to get this overturned because they knew it was a huge issue. Yeah, and they failed every time.
Robinson Meyer:
And then the campfire happened in 2019 and it was like suddenly Chekhov’s gun in California state utility law kind of went off. And it was like, oh no, this actually doesn’t work at all because PG&E went bankrupt. And since then, I don’t know, lawmakers just been trying to clean it up.
Lauren Teixeira:
Yes and no. I mean, how lawmakers initially addressed it was just like, we cannot let a utility go insolvent again. And that’s why they created the Wildfire Fund. But what that did is it did keep the utility solvent, but it also drove up electricity rates by quite a lot. And that is increasingly politically untenable. At the same time, we are in the midst of an insurance crisis because the Chekhov’s gun of insurance policy, Prop 103, also went off. And in the past few years, a lot of the private insurers have declined to renew their policies or they have left, because they say, you know, we can’t recover, we can’t stay solvent if we’re not allowed to let our premia match our claims, which is how, of course, an insurance business works. That has had the effect of rolling an astronomical number of people, it’s increased 5x in the past year, six years, onto the insurer of last resort, the FAIR Plan, which of course is in part capitalized by all the other insureds in the state. So that’s another subsidy from low risk people to high risk people. And that is politically very untenable, especially since many of the people receiving the subsidy of the FAIR Plan are rich people with second homes in
Lauren Teixeira:
Calabasas or Tahoe or Malibu or whatever.
Robinson Meyer:
We did an episode last year about California’s housing insurance and how broken it is. But it seems like these are like two latent problems in state law that both became active problems in the past decade and have this deep interrelation. And so how would you, how do you think we should go about fixing them?
Lauren Teixeira:
Wow, I’m so glad you asked. So it’s not going to be easy. However, it will get fixed in part if only because it’s become so politically untenable to have all of these people going on to the state insurer and to have incredibly high electricity prices, which people hate. And by the way, our hurt, you know, poorest people the hardest because it’s regressive. Also, the people who need the most air conditioning in California live in the Central Valley. They tend to be poor and don’t have rooftop solar, which is something that reduces your electricity bills.
Robinson Meyer:
So in California,
Lauren Teixeira:
We don’t have the huge subsidy for rooftop solar anymore, but we still subsidize it.
Robinson Meyer:
Users are grandfathered in, right?
Lauren Teixeira:
Existing users are grandfathered in. That is an awesome subsidy for them. And by the way, second to wildfire, that’s the biggest driver of rising electricity bills is the rooftop solar subsidy.
Robinson Meyer:
Want to hear more about that? You can listen to the episode we did with Severin Borenstein in 2024. We’ll put it in the show notes.
Lauren Teixeira:
Yes. Severin is the absolute GOAT of California land energy policy.
Robinson Meyer:
So basically, you have this system where, and I just want to make sure I understand this correctly. Anytime utility touches a wildfire at all, that utility then becomes responsible for the wildfire. And so utilities are obsessed with making sure they reduce their risk of ever touching a wildfire in any way. And they are willing to pay out the wazoo, as they are encouraged to do by state law, to reduce their risk. At the same time, the housing insurance system in California is breaking down. And one reason that homeowners who live in this so-called wildland urban interface, this kind of sprawly area into nature, where your chance of your home burning down in wildfire are much higher, one place they can dump risk is into utilities, too. And so almost the whole economy of the residential sector in California, both homeowners and also how the primary source of homeowner energy, the electricity system, like all just want to like dump risk onto the utility sector. And then the utility sector is like trying to get the risk off of it as fast as it can. It’s like basically almost like the scapegoat.
Lauren Teixeira:
Oh, that’s exactly what it is. Yeah.
Robinson Meyer:
So how would you fix this? We were kind of getting into how you would fix this, but it seems to me to be tricky because all of this emerges from this constitutional issue, allegedly, around how the utilities face wildfire risk.
Lauren Teixeira:
So I think one good thing is you wouldn’t necessarily have to change the constitution, and the legal scholars have ideas about how we can get around that. But the risk does need to be redistributed, and that’s the thing that’s important. As you allude to, doing that will be incredibly hard for a number of classic political economy problems, which is that incumbents will resist any policy that will make them pay more. Those incumbents being homeowners in high-risk areas as well as local governments who do not want to charge people higher property taxes for wildfire mitigation because they want people to move there, as well as some I would say uniquely Californian entities such as Consumer Watchdog I don’t know if you’ve heard of them, but they’re kind of like a Naderite organization whose kind of sole purpose in life is to resist any.
Lauren Teixeira:
Kind of pro-business or thing that will make the economy function more efficiently. So yeah, they have like a whole apparatus where their whole thing is whenever insurers try to raise their rates, they immediately intervene in the consumer intervener process. And by the way, get a nice cut from that because that’s how Prop 103 works is you can pay out to the people who intervened. So that’s a huge constituency that is really against any reforms to the insurance market. There’s also the wildfire victims who are obviously very sympathetic and, in my opinion, are a little bit being used to launder some consumer watchdog type sentiments, but they’re hard to argue with. So people are going to resist this a lot. And, you know, what I propose in my report is essentially buying out the incumbents. So... There are going to be people in high-risk areas who, if we get rid of strict liability and we sunset the FAIR Plan, so that’s another thing I think needs to happen.
Robinson Meyer:
Let’s talk briefly, what is the FAIR Plan? So right now, the home insurance market in California is kind of increasingly broken because of wildfire risk as well. And the particular scapegoat or the particular kind of magical risk absorber that’s been created under California law is called the FAIR Plan. So just tell us a little bit about the FAIR Plan and how that fits into this stew.
Lauren Teixeira:
So the FAIR Plan was conceived in the late 1960s as an insurer of last resort, essentially for black people who could not get insurance because of racism. And that’s what it was. And it served its purpose. And up until quite recently, people on the FAIR Plan were people in low risk areas, low risk urban areas. So over time, and this is actually, it’s not just California and other states, it’s turned into an insurer for people who live by the beach and in high-risk areas that are prone to wildfire. You might think, why is the state, you know, giving automatic insurance to people in very high-risk areas who also are often quite wealthy? Not always, but often. And the reason is that it’s very politically popular to offer insurance to everyone, and, Another reason is it props up the real estate market because you can’t really get a mortgage without insurance.
Robinson Meyer:
Right. And there’s this crucial interlinkage where mortgages exist for 30 years. You’re in hock to a mortgage for 30 years, but that mortgage is dependent on an annual renewal of your home insurance. And so if suddenly home insurance stops working for people, then either they have to go naked, which is the insurance industry term for not having insurance, which may eventually affect their mortgage and therefore their largest store of wealth. Or you like find some way to kind of make all the math math as a state because suddenly you have a fairly large population of people which even if the majority of homeowners covered by the FAIR Plan would be able to bear the risk and maybe should bear some of the risk you still have a large group of people who may not be able to bear the risk who may have gotten to this situation through no fault of their own or through very little kind of fault of their own and suddenly their main store of wealth is like tied up with this uninsurable asset.
Lauren Teixeira:
And that would be disastrous. Yeah. I mean, both politically and just for people’s welfare.
Robinson Meyer:
So your idea, as I understand it, is that these things would have to be fixed as a single package. So like describe that package.
Lauren Teixeira:
So my idea is that we have these issues in insurance and utilities. Utilities are propping up the insurance industry. Homeowners are going to be greatly damaged if the insurance industry is no longer popped up. So you kind of have to address all of these concerns at the same time. So my proposal is switch it to a fault-based standard. I don’t know if it’s going to require changing the constitution or not, but the point is you need to transfer some risk off of the utilities. This will be greatly damaging to homeowners.
Robinson Meyer:
A fault-based standard is that utilities, in order to be responsible for a wildfire, would have to have been negligent in some way. Their negligence would have had to, you know, originated the fire.
Lauren Teixeira:
So, yeah, I do think they should maintain some liability. Again, it doesn’t address the more philosophical question of, you know, what really created the risk, because there’s the ignition risk, but there’s also the conflagration. So, moving on. We changed to a fault-based standard, and that will cause an insurance market crisis. Luckily, California has finally faced the music with that. And we have finally started letting insurers charge forward looking, like using forward looking risk models, which before you were not allowed to do. And we’ve also started letting insurers pass on the cost of reinsurance, which before you were also not allowed to do, which is kind of crazy because, you know, that’s how the business works. So that’s getting repaired. We still require insurers to offer coverage to meet quotas of coverage, which obviously poses some moral hazard, but...
Lauren Teixeira:
The point is we need to restore actuarial pricing to the insurance market. That will be fine for the people who are getting subsidized coverage in Lake Tahoe or Malibu or Calabasas. It will be very bad for, you know, you could call them affordability migrants rather than amenity migrants. They left the cities because housing was unaffordable. Now they’re in the wild and urban interface. They’re not rich. Their home is their greatest store of wealth. My suggestion is to keep the FAIR Plan, but put a sunset on it. Say, you know, after 2040, no more FAIR Plan. And in that time, just offer either second mortgages or straight up grants for home hardening so that those people can get an affordable premium when they have to go back into the private market. And that would be funded through taxpayer grants.
Robinson Meyer:
And so that way, first of all, you shift it from the rate base to the tax base. But the idea there basically is that you give people a deadline and then you say, you got to get your home ready by this date and we’re going to pay you a ton of money or we’re going to do it for you, basically.
Lauren Teixeira:
Yeah. And it would make sure that no one gets on the FAIR Plan in the future, right? It just kind of helps slowly depopulate it if you know that you’re not going to have it forever.
Robinson Meyer:
One interesting kind of subtext of your report is that these two systems, the electricity system where prices are increasingly high, and the insurance system where homes in California are becoming increasingly uninsurable, are like tied together which is very interesting, but means that opportunities for reform are like even more difficult than you would expect them to be generally. So do you have to resolve them together? The recently Politico reported that Governor Newsom is proposing ways to the state legislator to like fix the electricity insurance issues or to reform the electricity insurance issues. How much of that needs to happen in conjunction with the home insurance issues? Or can you kind of piecemeal them out?
Lauren Teixeira:
I think they do need to happen in conjunction. The reason being that, you know, as far as we know, and insurers did submit testimonials about this, is that the extent they are solvent, it’s because they have this recourse of suing the utilities and recovering damages. So if strict liability goes away or if utility liability is capped or something like that, it will mechanically mean that insurers have to pick up more risk, and that could mean more non-renewals. They could be even less solvent. That would be bad because, again, it’s politically popular for everyone to have insurance. So you would need some kind of reform in the insurance market where either, you know, the rich people can go to actuarial prices and the poorer people can get FAIR Plan. And the insurers are one of the main constituencies lobbying against this reform for this exact reason. And the idea is that if they see on the table that they will be able to maintain solvency in other ways, they will be less opposed to the reform.
Robinson Meyer:
What’s the case for strict wildfire eligibility? Like, how did this come about in the first place?
Lauren Teixeira:
It was kind of just how they interpreted it at the time. I think the theory with strict liability is that it’s the public inflicting this on you, right, in the form of the government. So we should socialize it across the public. And usually that’s going to be through the tax base if the streetlight falls on your car. But in the case of wildfire, that’s getting socialized through the electricity rates.
Lauren Teixeira:
It’s just a very strange, strange case of this doctrine being applied.
Robinson Meyer:
California state policy is so interesting because it’s this interesting mix of like fixes that were a good idea at the time that just emerged from the court system or emerged from the state system. And then variously like politicians or voters having bad preferences. Often when non-Californians discuss California policy, there’s a temptation to blame the politicians or the state Democratic Party, because it’s had trifecta control of the state at this point for a long time, 10 years or something. It seems to me that the more elevated assessment is that actually voters want a lot of things that are like very difficult to reconcile. And so like politicians kind of like do their largely their best to reconcile. So my question about this whole situation is, is this kind of a voter problem? Or is this a politician’s problem? Or is this like, unfortunately, multiple Chekhov guns that were accidentally written into state law, like all had their trickers wired together and nobody realized it because of the the you know kitchen twine bubble gum and twigs that constituted the legal regime at the time it made sense to implement them but then like when one trigger went off like suddenly all the guns fired and it was like oh shit you know so like whose fault is this
Lauren Teixeira:
Great question. I think that … I don’t think California voters are dumber than voters anywhere else in the country. I do think that the California ballot system gives the dumbness of voters a real chance to shine and be enshrined in law, which for the listeners, we have a ballot proposition system where there will be all of these propositions on the ballot every year that kind of sound good in the three-sentence summary that’s like, do you think puppies should be given treats? That’s something on the ballot. And people say, yes, that sounds good to me. And that’s what happened with Prop 103 in 1988, the consumer watchdog Naderite people said, hmm, these auto insurance premiums are kind of high. What if you could have lower ones? And people said, sounds great, right? And most people have not seen supply demand curves. They don’t realize that it’s a bad idea for the market not to clear. And they say, cool. And by the way, it didn’t pass overwhelmingly. Like there were people who were like, maybe this is a bad idea. It passed, I think it was only 54% or something like that. But now that’s the law of the land, and...
Lauren Teixeira:
Insurance increases are subject to the whims of an elected official who has every reason to not approve insurance increases. So, yeah, I think the proposition system has been somewhat bad for the state. I think in general there’s an unwillingness to acknowledge tradeoffs in California or to accept them. However, it turns out that when you don’t do that, the risk just gets pushed somewhere else. So insurers and utilities are pretty easy bad guys. It’s also easy to perpetuate something when the costs are diffuse and the benefits are concentrated. But eventually, you know, push comes to shove and people are wondering, why are we subsidizing the insurance of people with second homes in Tahoe?
Robinson Meyer:
This seems like an interesting case, though, because it seems like the insurance market being broken is sort of related to the prop system. But the utility insurance being broken is like not related to the prop system. That’s just related to like a combination of this unusual doctrine in the California constitution around government liability and the unusual role that public utilities play.
Lauren Teixeira:
I mean, utilities are such a weird business model. They’re not like anything else. And they are also captive, famously. So it’s really easy to put stuff on them and to hide stuff in the rape base. And you don’t want them to go bankrupt.
Robinson Meyer:
Yeah, like a utility can’t exit the state. Like it’s kind of captive both ways, right? Because on the one hand, lawmakers can put costs on the utilities and utilities have to pay them. On the other hand, the utility can force the state to bear costs because the utility can’t go anywhere. Where it’s imminent in the infrastructure. I think one theme of your report, and one theme of the story you’ve just kind of spun for us, is that utilities are acting reasonably. They’re acting like very rationally when they try to reduce risk because this is an existential issue for them and it’s existential in like a corporate way. They will go bankrupt. If they start a catastrophic wildfire, you know, on top of the many other horrible consequences of starting a catastrophic wildfire, and that would be bad. And so therefore, they’re acting like very reasonably when they try to reduce these expenses. But it also seems to be that policymakers, and I want to defend the regulatory system that exists here. When policymakers, like, can’t assume the utility will take the public’s best interest when they are writing policy about the utility, because the utility is kind of like a monster or it’s like a very well-trained but not perfectly trained large beast in that it is going to usually do the things you expect.
Robinson Meyer:
It is also, the utility is in fact interest bound and legally bound to like, be a for-profit company. It seems like this is a challenge of utility governance more broadly, is that you have to like both write policy that allows the utility to provide reasonable service and that is bound by, I don’t know, where we assume it’s kind of bound by supply and demand curve. But in fact, the utility isn’t bound by supply and demand curves at all. It’s this totally anomalous form of corporation. And if you write the policies wrong, then it will kind of go haywire on you.
Lauren Teixeira:
Yeah. I mean, people respond to incentives or companies respond to incentives and they very rationally follow the incentives that were created by the structure. Would making it not for profit change that? I don’t know. I mean, a not for profit utility would also be subject to inverse condemnation with strict liability in California. And you know we can get into public power stuff but it’s a little beyond the scope of this. I don’t see that as the solution.
Robinson Meyer:
I don’t think it needs to be part of the solution to just be like an interesting challenge of this policy making
Lauren Teixeira:
In that yeah it’s just nothing’s perfect like it’s just a really really hard thing the the incentives for utilities are inherently, bad and perverse no one solved it right we have the idea that maybe performance-based rate making could solve something and at least make them, a little more responsive to the idea that you should be cost-effective. I think that would be great if we did that. We’ve already drifted toward that a little bit in that in SB 254, the utilities were required to report how cost-effective the various interventions were, like per units of risk reduced. And they have made some advancements. Like, to give them credit, they have figured out that you can reduce a lot of risk very cheaply through operational measures. However, the existential thing is still around, that the utility could go poof if they happened to set a fire. So... I don’t know. It’s really tough.
Robinson Meyer:
Just to go back to like California specific policy challenges, how much of this is an issue of it’s very hard to raise tax revenue in California, but it’s very easy to raise electricity rates. Speaking of the prop system, right, it’s very hard to pay to like increase the tax base in California. But the CPUC can raise electricity rates when the utility asks it for, asks it to do so.
Lauren Teixeira:
I think that’s a big part of it. Yeah.
Robinson Meyer:
Yeah. And so to some degree, this is the public’s in California, not the public in the sake of the government, but the public in the sense of like the society’s easiest way of raising revenue in the California system. And so therefore, it’s the revenue that tends to get raised. Unfortunately, it’s very regressive and bad for climate policy.
Lauren Teixeira:
Right. It’s a tax through a different system. It’s a regressive tax. And it’s rational to do that. But as I argue in my report, this is actually a really ineffective and inefficient way of reducing wildfire risk. And that, you know, say we weren’t parking all of this on the utilities, I think it’s very possible we would get a lot more risk reduction for the same amount of money, in that when it’s all on the utilities, they could very expensively underground a power line or a local municipality or property owner could construct a fuel break or do mitigation much more cheaply, and reduce the same amount of risk. But with the status quo, we end up with the expensive power line instead of the fuel break. And I think that’s a huge loss of opportunity because obviously wildfire is very dangerous and bad. And we want to get as much risk reduction for a certain sum of money as we can. So what we have right now is the politically convenient thing, but it’s not the most risk reducing thing. And the most risk reducing thing is not the politically convenient thing. But we may have to go toward it because electricity rates have also become politically unattainable.
Robinson Meyer:
And just talk briefly about the challenge of high electricity rates in California. What do they mean?
Lauren Teixeira:
They are very bad for everyone. California famously has very ambitious climate goals having to do with electrification. We’re still holding down the an EV in every home kind of paradigm. We hope people will switch to electric stoves, etc. Obviously, it’s very hard to do that if your electricity rates are incredibly high. And I think I saw somewhere it’s like it doesn’t even make sense at this point to get an EV rather than a gas car because of the electricity rates. And that’s, you know, you want people to not make that choice. And for that reason, a lot of the green groups actually are pushing. They want inverse condemnation reform. So that’s another reason to have lower electricity rates. In general, abundant energy is great. We don’t want it to be expensive. And yeah, it’s a big challenge.
Robinson Meyer:
And when it’s expensive, decarbonization’s even harder. Laura Teixeira, thank you so much for joining us on Shift Key.
Lauren Teixeira:
Thank you so much for having me.
Robinson Meyer:
And that will do it for us today and this week. We’ll be back next week with a new episode of Shift Key. Until then, Shift Key is a production of Heatmap News. Our editors are Jillian Goodman and Nico Lauricella. Multimedia editing and audio engineering is by Jacob Lambert and by Nick Woodbury. Our music’s by Adam Kromelow. Thanks so much for listening. We’ll see you next week.

 Evaporating. Chart: EIA