You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
This is what we’re tracking in energy and climate over the next four months — and beyond.

This is an edition of Heatmap Daily, an evening review of the day’s news written by our executive editor. Sign up for it here.
We’re in the last third of 2026. In yesterday’s newsletter, I looked at the biggest planned upcoming events in climate and energy policy that we’re tracking at Heatmap for the rest of this year.
Today, I want to look at some of the biggest questions that I’m pondering for the rest of the year.
What will the AI backlash mean for data centers and energy demand?
In just the past 24 hours, existential concerns about artificial intelligence has gone mainstream. Even though AI engineers have warned that the technology could trigger some kind of mass fatality event — or even human extinction — for years, the resignation of Sam Coxon from Anthropic seems to have broken through into a new tier of public awareness. “We really do earnestly believe AI could kill all humans! I personally think it is >10% within the next decade,” Evan Hubinger, an Anthropic employee, posted on X after Coxon’s resignation broke.
It’s unscientific, but I’ve seen more celebrity Instagram posts, vertical videos, and concerned messages from friends about AI doom in the past day than I have in weeks. Senator Bernie Sanders is now holding a bipartisan meeting next week to discuss the “extraordinary dangers” posed by AI, according to Axios.
We already know that the public detests AI data centers. But so far the data center story has been somewhat severable from the AI story — voters, politicians, and journalists could talk about the AI infrastructure buildout separately from the tales of, say, AI allegedly solving century-old math problems. Will that remain the case? Or will the two stories merge? If that happens, will politicians and AI safety experts start to encourage (or even empower) the data center backlash because it might slow down AI’s overall development? What will that mean for the politics of infrastructure, electrification, and load growth — and will it cut greenhouse gas emissions?
What will happen in Iran, how high can oil go, and what will it mean for the energy system?
President Donald Trump has never been “looking for long term” in Iran, yet his war continues to drag on without an obvious or easy resolution. It has dragged energy prices up with it.
The global crude benchmark has now edged above $100. Gasoline costs more than $4.20 a gallon on average in the United States (and far more in Europe), and diesel is even more expensive. According to an ongoing estimate from Brown University researchers, the war has now cost Americans more than $100 billion due to energy inflation since it began. Hostilities have seemed to intensify in the past few days; Iran fired missiles at U.S. Navy ships and the United States responded by destroying oil tankers.
This has been generally bad for European economies, which are to some degree still recovering from the triple shock of Covid, energy inflation from Russia’s invasion of Ukraine, and China’s ongoing export boom. At the same time, the Iran war has broadly vindicated China’s energy strategy, which has used electrified technology, strategic stockpiling, and a coal, solar, and battery-dependent power grid to reduce economic dependence on seaborne liquid fuels. (China’s greenhouse gas emissions actually fell in the second quarter because of a drop in the country’s oil consumption.)
The most urgent question here, of course, is whether President Trump will find a way to end the war that he began earlier this year — and how expensive oil and liquified natural gas will get in the interim.
But an end to the war will trigger another set of questions about what this energy shock will mean for energy, climate, and industrial policy going forward. Shocks like these tend to dominate national strategy for years or decades after they happen; Thailand’s government announced last month that it’s backing off LNG imports in favor of renewables. Will we start to see a wider set of countries do the same? Will more countries build strategic oil stockpiles, driving up oil demand in the short term? And will more middle- and low-income countries embrace Chinese-made electric cars in the name of boosting energy security and cutting their oil dependence?
Will the U.S. get bipartisan permitting reform?
The most important political question this year — if you are a normal person — is whether Democrats will take over the House of Representatives and even the Senate in the upcoming midterm election. But we aren’t normal people here at Heatmap. And the midterm elections will, for us, only commence the year’s most interesting political moment.
Right now, lawmakers from both parties say they are trying to reach a deal on bipartisan permitting reform. Such a bill would make it easier to build transmission lines, renewable energy, and some fossil fuel infrastructure, as well as presumably restraining the president’s extralegal war on solar and wind. It could even make it easier for the government to build public infrastructure of all sorts.
We haven’t seen the text of such a deal yet — although my Shift Key interview with Daniel Palken, a permitting expert at Arnold Ventures, offers a lot of clues to its potential content. So it remains an open question whether lawmakers can reach a deal in November and shepherd it through a lame-duck Congress before the end of the year.
If they can, it could enable a future president to conduct a faster and more aggressive clean energy or infrastructure buildout than was previously imaginable. If they can’t, then it will be hard to imagine when such a deal might ever come together, as it has failed to congeal under almost every partisan combination of a president and Congress.
Will 2026 be the hottest year ever?
Back in the spring, climate scientists assigned low odds to the probability that 2026 would become the hottest year ever measured. Since then, though, a monstrous El Niño has clawed out of the Pacific Ocean, nudging up global temperatures and contributing to America’s record-breaking summer.
2026 now has a greater than 33% chance of eclipsing 2024’s hottest-year-on-record title, according to a late July estimate from Carbon Brief; the odds have probably risen further since then. Either way, 2026 will probably come in about 1.5 degrees Celsius warmer than the pre-industrial average — and 2027 is very likely to be even hotter.
Are we entering a post-Trump, post-2010s energy and climate era — and what will it look like?
President Donald Trump is about as unpopular as he has ever been, and on a range of issues, he seems to be losing touch with the American public. Simply by dint of being the country’s most prominent political figure for most of the past 10 years, he has become an establishment politician. He now champions AI, data centers, and the Iran War, for instance, while Americans seem skeptical of all three (at best).
In the next several months, these trends are all likely to intensify: Trump is likely to lose control of Congress — at least according to the polls and the betting markets — and a new presidential election will begin, one in which he will probably not be running.
Which isn’t to say that Trump will lose his grip on the Republican Party or its voters — nor that his actions in the coming years will be lawful, or even Constitutional. But nevertheless if you squint, you can begin to imagine what a post-Trump political era might look like, and it is quite different from the epoch that we have just lived through. It is an era where voters will likely be more worried about inflation and the cost of living than unemployment and economic growth. It is an era where Democrats will be looking to play up economic populism and where the federal deficit might matter again. It is an era where Millennials will be in their prime earning years, where politicians will fear a backlash to industrial policy and infrastructure buildout, and where America’s role in the world will remain unsettled.
It is, in short, not at all like the era that gave us the Green New Deal or the other energy and climate policy of the early 2020s; even if a recession hits and employment becomes a major concern once again, then the resulting political environment might look more like 1992 (or even 1937) than 2008. We are, in short, entering a new era — one we’re excited to watch, develop, and cover here at Heatmap.

Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
‘Our entire company was built for this purpose.’
After decades of stagnation, the nuclear industry has drummed up all kinds of ideas meant to revive the prospects for building reactors in the United States. Make the reactors smaller. Micro, even! Cool them with helium or molten salt instead of water. Invite the Koreans or Canadians to come teach us how to construct atomic power stations again.
Yet the startup bold enough to name itself The Nuclear Company launched in 2024 on a simpler thesis: Just go with the large-scale reactors we have built before, and construct them in bulk to bring down costs.
Essentially, do what the Chinese did.
While the U.S. struggled for 15 years to complete its first two Westinghouse AP1000s, the 1.1-gigawatt units designed at the dawn of this century to be America’s flagship nuclear technology, China built four in the same time period. Beijing then reverse-engineered the technology to make its own version with an entirely domestic supply chain. China now has 10 operating Hualong One reactors and at least 37 more on the way. The U.S. ultimately completed its first two AP1000s at Southern Company’s Alvin W. Vogtle Electric Generating Plant in eastern Georgia right around the same time.
The Nuclear Company was formed by hiring former managers who oversaw the Georgia project. Despite the Trump administration’s pledge to finance construction of at least 10 more large nuclear reactors, the only projects that have broken ground are new, first-of-a-kind small modular reactors that skeptics fear will face the same billion-dollar cost overruns that the AP1000s faced at Plant Vogtle — but without the same output of electricity to balance out the expenses.
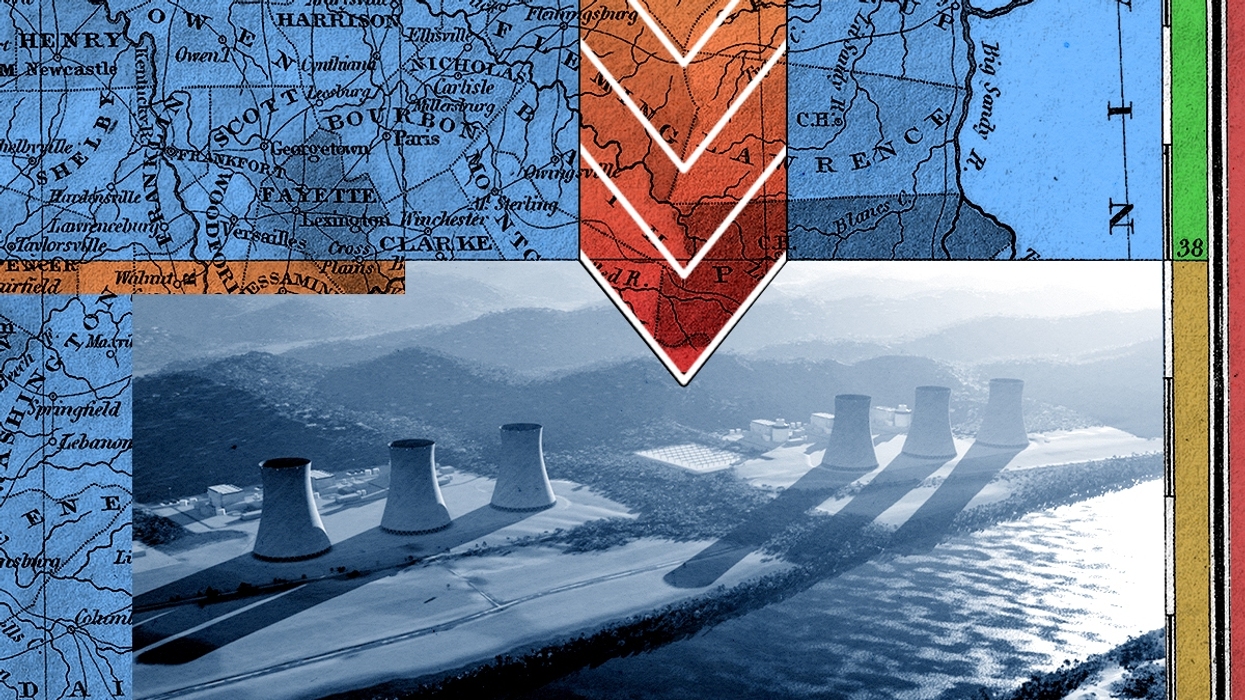
On Wednesday morning, The Nuclear Company announced its most significant attempt at a Chinese-scale buildout yet. The firm unveiled plans to build 6.6 gigawatts of new, large-scale reactors at a greenfield site in Kentucky, along the Ohio River. Dubbed Prosperity One, the project would be located in Lewis County, on property once assembled for a coal-fired station that was later abandoned. The site sits half a mile from a 765-kilovolt transmission line that connects to PJM Interconnection, the nation’s second-largest and arguably most stressed grid system.
“Our entire company was built for this purpose,” Joe Klecha, The Nuclear Company’s chief nuclear officer and a former manager on the Plant Vogtle buildout, told me. “We recognize that this is different and unique in our country. We believe it’s very much needed.”
The project will begin with two reactors at a time; the Kentucky site has room for up to six. The Nuclear Company is already negotiating potential offtake agreements with electricity buyers to help finance construction, and it expects deals by next year. The company told me it has not yet decided whether it will run the Prosperity One as an independent power provider or sell the facility to a utility or another plant operator. “We are preserving all options and will make that decision as we pull the other partners onboard formally,” Klecha said.
Since its inception, The Nuclear Company has focused on the AP1000 as the most promising design in the U.S. That’s particularly true after the Nuclear Regulatory Commission certified the Vogtle Unit 4 design last week as the permanent, settled schematic for future AP1000s.
But Klecha left open the possibility of another technology. “The AP1000 is our basis for the site at this point, but we’ll continue to evaluate other options as we get through the site characterization,” he said. He expects that process to wrap up in “the first half of next year.”
The company’s options are limited, though. Last month, as I reported, South Korea agreed to help the U.S. build up to six new AP1000s at an as-yet-unspecified site in addition to constructing at least two APR1400s — that is, essentially the Korean version of the American technology. In theory, The Nuclear Company could build APR1400s, too. But it’s highly unlikely, since Westinghouse accused the state-owned Korea Electric Power Corporation of ripping off its technology for the APR1400 in 2022. That led to a yearslong lawsuit and settlement that gave the American company the right to demand royalties and keep Seoul out of markets where Westinghouse aims to compete.
The only other viable option is the ABWR. The world’s first so-called advanced reactor, the ABWR was built with General Electric’s boiling water reactor technology, which is used across about a third of the U.S. fleet. It serves as the second-most popular design after Westinghouse’s pressurized water reactor model. Japan successfully built four ABWRs over a decade from 1996 to 2006, and Taiwan nearly completed two before killing the project in a bid to phase out nuclear power altogether. The NRC certified the ABWR for construction in the U.S., but a project in southern Texas that aimed to build the first in the U.S. was scrapped about a decade ago.
“The ABWR has an impressive pedigree of construction success as well as experience being built to U.S. standards that is hard to find outside of the Vogtle project,” Brett Rampal, a veteran nuclear consultant who advises Deloitte and Veriten, told me. Still, he said, the AP1000 is the leading contender for the Kentucky site.
Rampal said Prosperity One represents a welcome break from how large-scale reactors have been planned in recent years. While most of the industry remains focused on small modular reactors, research I covered last month indicates the technologies could face worse cost problems than large-scale units, and the emerging consensus on building AP1000s focuses on expanding existing nuclear plants.
Indeed, The Nuclear Company’s first major deal was to help Brookfield Asset Management, which owns 51% of Westinghouse, complete a thwarted AP1000 project at the V.C. Summer plant in South Carolina. But other potential sites considered for new AP1000s included expansions of Florida Power & Light’s Turkey Point nuclear plant in Florida, the Tennessee Valley Authority’s Bellefonte nuclear station in Alabama, or even adding another two units to Plant Vogtle.
“A lot of the thoughts around AP1000s and large reactors have always been around existing or already-licensed sites,” Rampal said. “It’s very interesting to see TNC’s first project buck the trend of what folks have been talking about around the large reactor story in this country."
At least one thing is certain about The Nuclear Company’s approach: It will settle on one design. The company is animated by the need to avoid one of the U.S. nuclear industry’s biggest financial mistakes, known simply and derisively as “Whoops.” In 1983, the Washington Public Power Supply System — WPPSS — triggered what was then the largest municipal bond default in U.S. history after its buildout of several different reactor designs at once fell apart in a major boondoggle.
Building different reactors at Prosperity One “really goes against our mission, our vision, and our thesis as a company,” Klecha confirmed.
The key is repeating the same design over and over again so the project managers sort out the fastest, most efficient ways to build and workers hone skills in actually constructing the design. “Six AP1000 units on one site creates the scale and repetition needed to drive down costs and sends a strong signal to the supply chain,” Lin Yuan, the senior advisor at the Nuclear Scaling Initiative, a non-profit collaboration working to create the enabling commercial and policy conditions for safe and secure nuclear energy scaling, told me in an email. “Manufacturers and craft labor need to see a sustained order pipeline to invest in capacity, factory expansion, and training.”
Vogtle Unit 4 came online in 2024 roughly 30% cheaper and faster than Vogtle Unit 3, completed a year earlier. Klecha said that’s the minimum cost reduction The Nuclear Company expects for the first two reactors built at Prosperity One.
“The 30%, I would say, is the floor on the savings from the first unit to the second unit,” he said. “How do we capture those lessons? Obviously, our team’s experience. We have a pretty rigorous ‘lessons learned’ document.”
Soon, he hopes, there will be even more lessons learned — in concrete, rather than on paper.