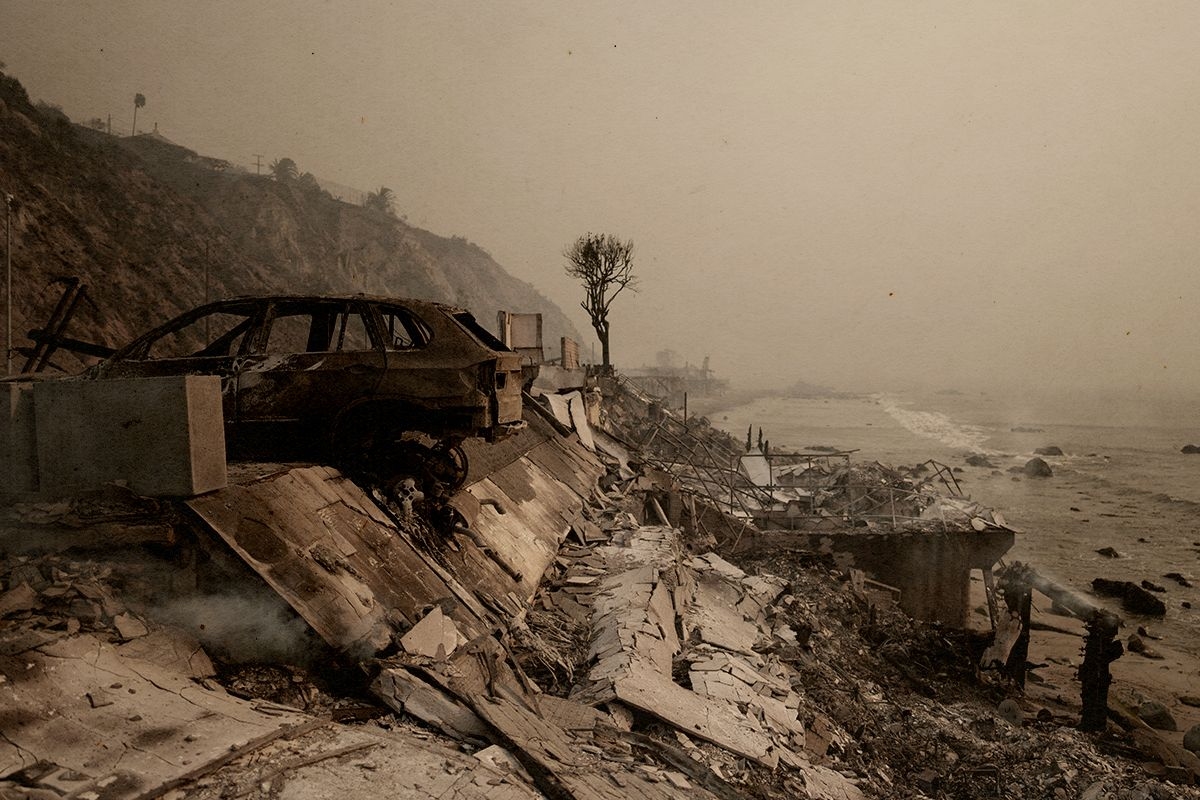
Los Angeles is on fire, and it’s possible that much of the city could burn to the ground. This would be a disaster for California’s already wobbly home insurance market and the residents who rely on it. Kettle Insurance, a fintech startup focused on wildfire insurance for Californians, thinks that it can offer a better solution.
The company, founded in 2020, has thousands of customers across California, and L.A. County is its largest market. These huge fires will, in some sense, “be a good test, not just for the industry, but for the Kettle model,” Brian Espie, the company’s chief underwriting officer, told me. What it’s offering is known as “parametric” insurance and reinsurance (essentially insurance for the insurers themselves.) While traditional insurance claims can take years to fully resolve — as some victims of the devastating 2018 Camp Fire know all too well — Kettle gives policyholders 60 days to submit a notice of loss, after which the company has 15 days to validate the claim and issue payment. There is no deductible.
As Espie explained, Kettle’s AI-powered risk assessment model is able to make more accurate and granular calculations, taking into account forward-looking, climate change-fueled challenges such as out-of-the-norm weather events, which couldn’t be predicted by looking at past weather patterns alone (e.g. wildfires in January, when historically L.A. is wet). Traditionally, California insurers have only been able to rely upon historical datasets to set their premiums, though that rule changed last year and never applied to parametric insurers in the first place.
“We’ve got about 70 different inputs from global satellite data and real estate ground level datasets that are combining to predict wildfire ignition and spread, and then also structural vulnerability,” Espie told me. “In total, we’re pulling from about 130 terabytes of data and then simulating millions of fires — so using technology that, frankly, wouldn’t have been possible 10 or maybe five years ago, because either the data didn’t exist, or it just wasn’t computationally possible to run a model like we are today.”
As of writing, it’s estimated that more than 2,000 structures have burned in Los Angeles. Whenever a fire encroaches on a parcel of Kettle-insured land, the owner immediately qualifies for a payout. Unlike most other parametric insurance plans, which pay a predetermined amount based on metrics such as the water level during a flood or the temperature during a heat wave regardless of damages, Kettle does require policyholders to submit damage estimates. The company told me that’s usually pretty simple: If a house burns, it’s almost certain that the losses will be equivalent to or exceed the policy limit, which can be up to $10 million. While the company can always audit a property to prevent insurance fraud, there are no claims adjusters or other third parties involved, thus expediting the process and eliminating much of the back-and-forth wrangling residents often go through with their insurance companies.
So how can Kettle afford to do all this while other insurers are exiting the California market altogether or pulling back in fire-prone regions? “We like to say that we can put a price on anything with our model,” Espie told me. “But I will say there are parts of the state that our model sees as burning every 10 to 15 years, and premiums may be just practically too expensive for insurance in those areas.” Kettle could also be an option for homeowners whose existing insurance comes with a very high wildfire deductible, Espie explained, as buying Kettle’s no-deductible plan in addition to their regular plan could actually save them money were a fire to occur.
But just because an area has traditionally been considered risky doesn’t mean that Kettle’s premiums will necessarily be exorbitant. The company’s CEO, Isaac Espinoza, told me that Kettle’s advanced modeling allows it to drill down on the risk to specific properties rather than just general regions. “We view ourselves as ensuring the uninsurable,” Espinoza said. “Other insurers just blanket say, we don’t want to touch it. We don’t touch anything in the area. We might say, ’Hey, that’s not too bad.’”
Espie told me that the wildly destructive fires in 2017 and 2018 “gave people a wake up call that maybe some of the traditional catastrophe models out there just weren’t keeping up with science and natural hazards in the face of climate change.” He thinks these latest blazes could represent a similar turning point for the industry. “This provides an opportunity for us to prove out that models built with AI and machine learning like ours can be more predictive of wildfire risk in the changing climate, where we’re getting 100 mile per hour winds in January.”