That’s the landmark finding of a new report by a veteran nuclear researcher, who quantified and broke down the cost of constructing nearly every civilian atomic power station the U.S. built in the 20th century. Adjusting the dollar figures using the Handy-Whitman Index, a specialized formula for calculating inflation in the utility sector’s construction costs, the analysis — shared exclusively with Heatmap — concluded that 47 reactors built in the U.S. between the 1979 partial meltdown at Pennsylvania’s Three Mile Island nuclear plant and the turn of the millennium came in at an average of $8,200 per kilowatt.
“Costs are only going to come down from that,” Charles Komanoff, the economist and energy policy analyst whose consultancy conducted the study on behalf of the Clean Air Task Force, told me.
The paper carves out a pathway down the cost curve that runs counter to the industry’s broader consensus at the moment on the best way to make nuclear less of a luxury choice compared to other generating sources. Billions of dollars have flooded into companies promising to commercialize small modular reactors that generate 300 megawatts or less. The concept is a bet on what Komanoff calls the economies of duplication, meaning that if customers need more individual reactors, developers can ride that repetition to lower prices. But the paper suggests that the way developers have historically reduced nuclear costs — through economies of scale — achieves the same per-kilowatt savings with one gigawatt-sized, water-cooled reactor as 20 smaller reactors would net.
Some small and microreactor developers say that using alternative coolants — molten salt, liquid sodium, high-temperature gases such as helium — could further raise the efficiency of their technologies, allowing them to make up for whatever they lose on economies of scale. But large, traditional reactors such as the AP1000 are “a proven technology” that, unlike next-generation reactors with far less operating experience, won’t have to overcome “teething problems” to reach maximum efficiency levels, Komanoff told me.
There are other options to the AP1000, such as the ABWR that the parent companies of GE Vernova Hitachi Nuclear Energy built in Japan and Taiwan in the 1990s. One was planned for Texas, but abandoned a decade ago amid declining interest in nuclear power post-Fukushima. The technology is approved by the NRC, but GE-Hitachi has since turned its attention to its 300-megawatt BWRX-300. Given that no ABWR was built in the U.S., James Boucher, the former Deloitte nuclear consultant who co-authored the paper, said the AP1000 is the reactor best positioned to replicate the country’s successful buildout of the 1980s.
“We have two AP1000s. They're fully built. They’re operating. They’re doing, as far as I can tell, quite well. And they are like these reactors in our sample,” Boucher told me. “If we wanted to build 20, 30, 50 more AP1000s, I think we’d have a good shot.”
The Nuclear Company, a startup developer that hired much of the team behind the Vogtle buildout in a bid to become the go-to project manager for future AP1000s, called Komanoff’s report “promising because it demonstrates how cost can come down when we don’t focus on building first-of-a-kind projects.”
“There was a 30% overnight capital cost reduction just moving from Unit 3 to Unit 4 on the Vogtle project — there is no reason we can’t continue down the learning curve on the next AP1000s built in this country,” Joe Klecha, The Nuclear Company’s chief nuclear officer and president, told me after reviewing the report I sent him. “Especially with our mix of experience building these reactors and advancements in technology we’re leveraging to scale, achieving below $10,000 per kilowatt is just the beginning for us. We believe we can execute safer, faster, and at lower cost than we’ve achieved in the past.”
Back in the 1980s, the military-like regimentation common at nuclear plants and construction sites wasn’t yet as ingrained in the industry. The Nuclear Regulatory Commission had replaced the Atomic Energy Commission, which was seen as too deferential to the companies it oversaw, and spent the decade tightening rules on constructing and operating nuclear plants. New accident scenarios were being discovered, requiring new plants and existing ones up for relicensing to change operating protocols, upgrade equipment, and conduct additional research.
Komanoff was among those pushing for the changes. In reports he authored on behalf of Greenpeace, an arch opponent of nuclear power, he dissected the fiscal woes atomic energy developers faced, making the economic case for shutting down electrical stations that his fellow activists battled on ecological or moral grounds. Eventually, Komanoff moved on to advocating for a carbon tax as the fairest and clearest way to guide the economy away from fossil fuels and toward decarbonization. While serving as director of the Carbon Tax Center, which he co-founded, he noticed a trend among nuclear plants: They were getting better at operating.
The regulatory changes that followed Three Mile Island succeeded in raising the operating efficiencies of nuclear plants. In the 1970s, reactors had a capacity factor — a measure of how frequently a generating source actually produces electricity — of about 50%. Yet by 1991, that number had risen to 70%, putting atomic energy on par with the most efficient fossil fuel and hydroelectric plants. In 2002, that national average hit 90%. In 2019, it rose to 94%. When the final reactor at Indian Point, the nuclear station that served Komanoff’s native New York City, closed in 2021 due to political opposition to its relicensing, it had just set a world record for an uninterrupted 753-day run of electricity production.
Gradually, Komanoff came to see nuclear power as a vital tool for decarbonization. But, ensconced in the climate movement through his carbon tax advocacy, he found it easier to stay mum on his conversion, lest he ruffle the feathers of fellow activists who remained stalwart anti-nuclearists. After all, he thought, if a carbon tax passes, nuclear plants will benefit, so why bother speaking up specifically for atomic energy? Indian Point’s early shutdown, however, caused Komanoff pangs of regret.
“It just forced me to confront the consequences of not advocating for nuclear power,” he said. “I felt the way I imagined I would feel if a climbing partner — I used to be a sort of mountaineer — had died because of some negligence on my part. I really took personal responsibility because I imagined that — and maybe I’m just in a complete fantasy about my shamanistic power — as someone who had argued 40 years ago for shutting Indian Point, that if I had gone public say ‘Don’t do it,’ that I might have been able to begin turning the tide.”
While $8,200 per kilowatt is half of what Vogtle cost, it’s still nearly four times the cost of building a new natural gas-burning power plant with combined-cycle turbines, which itself rose to $2,157 per kilowatt last year from less than $1,500 in 2023. But the “regulatory churn” that kept the price of nuclear high, Komanoff said, is unlikely to return for new nuclear plants using proven designs such as the AP1000.
“Part of my optimism about nuclear being less subject to regulatory churn going forward is because it’s not a whipping boy,” he said. “It’s really hard to overstate the aura of incompetence that surrounded the nuclear power sector in the United States in the ‘70s into the ‘80s. But when you’ve got plants that are averaging 90% or higher capacity factors, things change.”

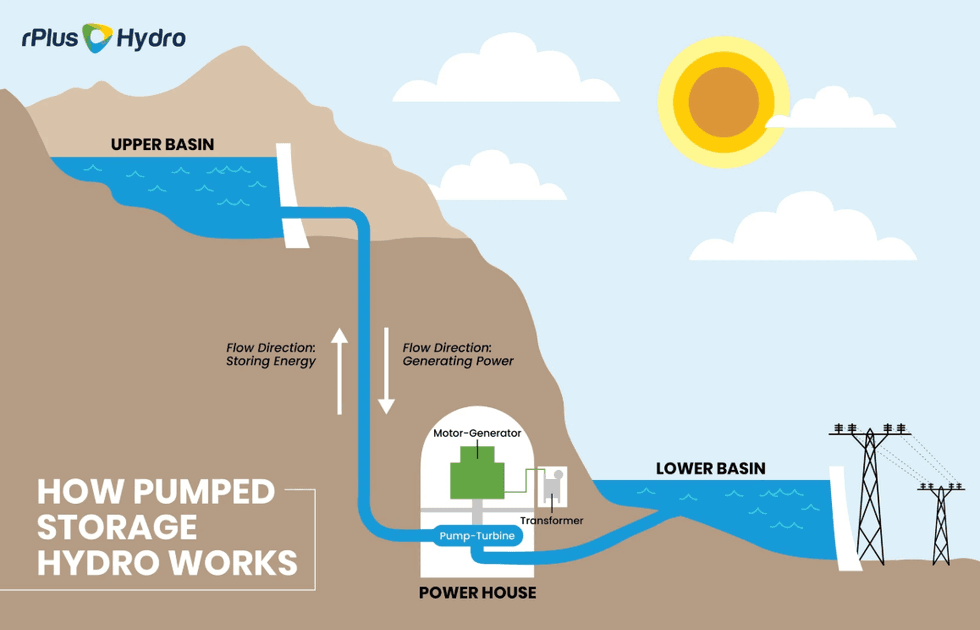 How the Seminoe pumped hydro project would work.rPlus Hydro