Though they appear at first blush to be standard activist fare, at least some are in fact part of paid influencer campaigns led by environmental NGOs or other advocacy groups.
“The prevalence of social media posts regarding BAAJA — both for and against — has all of the hallmarks of a paid and coordinated campaign,” Hennessy told me in an email. “They have shockingly similar talking points about complicated legislation, the same call-to-actions, many posted at the same time, and with repetitive talking points.”
Influencers and creators are appealing messengers for issue advocacy and political campaigns. They can have audiences in the hundreds of thousands, or even millions, of followers, all of whom feel like they have a direct connection to someone talking to them through their phones. And unlike a television ad, which disrupts the regularly scheduled programming, a political influencer talking directly to camera about politics is the main attraction.
Payments to influencers have begun to show up in campaign finance disclosures, and creators often face accusations from their followers or other influencers that they’re being paid to support a candidate or take a certain position on an issue.
“The volume of paid content has been increasing over the years,” Micah Erfan, a liberal creator who runs the social media firm Erfan Media, told me. “There’s a lot of money being spent to attack this thing,” Erfan said.
No one I was able to confirm had been compensated for their posts appeared to be taking a position on BAAJA that ran contrary to their own beliefs — their advocacy was broadly consistent with their worldview as expressed in their previous videos.
Two people I reached out to for this story told me they had been contacted by groups to post content about the bill, both pro and anti. The influencer marketing firm Activate HQ reached out to at least one person about a pro-BAAJA campaign, according to messages I was shown. Activate did not respond to a request for comment.
Julian Brave NoiseCat, a writer and documentary filmmaker, wrote on X that he had been offered $10,000 by The Wilderness Society “to make anti-BAAJA content.”
In correspondence he posted, an intermediary told NoiseCat that the National Association of Tribal Historical Officers, a group that strongly opposes BAAJA due to its provisions reforming the National Historical Preservation Act, “was hoping to connect with a celebrity influencer who could bring greater attention to concerns around the BAAJA permitting bill, particularly Title III and its implications for Tribal sovereignty and cultural protections.”
NoiseCat wrote that he directed the Wilderness Society “to an actually famous Native environmentalist because he has a larger following and would make the case against the bill in as strong and vital a way as possible.”
“His videos on the subject now have 1 MIL views and that’s just on Instagram,” NoiseCat said.
When I reached out to him, NoiseCat declined to specify the person he connected with the Wilderness Society, and told me in an email that he “cannot comment on who reached out to me or who I connect them to.” He added, “I am grateful to know so many incredible people across Indian Country as well as the environmental and progressive movements, etc. When I can help connect the right people and help them get paid for that work, I am happy to do it.”
Nataani Means, a Native American rapper and activist with 78,000 followers on Instagram, posted about BAAJA on November 5, listing The Wilderness Society and New Mexico Climate Justice as collaborators and citing 106 Strong, a coalition formed to oppose administrative and statutory changes to the consultation provisions of the National Historic Preservation Act, and the National College of American Indians. “Visit 106 Strong and the NCAI websites for more actions you can take,” he wrote in the video’s caption.
Means did not respond to emails I sent to his booking email, and The Wilderness Society and New Mexico Climate Justice did not respond to requests for comments. NCAI did not respond to questions about Means’ post.
Means is not the only prominent Native activist to post in opposition to the bill. Dallas Goldtooth, who was a writer and actor on the Hulu series Reservation Dogs, as well as a prominent figure in campaigns against the Dakota Access and Keystone XL pipelines, has posted two videos to his 245,000 followers on Instagram opposing BAAJA.
In one video, posted October 31, Goldtooth said the bill “attacks some of the strongest protections that tribal nations use to protect our sacred sites, burial grounds, and our sacred lines,” and described the bill as an “assault on tribal sovereignty.”
The video was co-posted with Climate Justice Alliance, a collective of community organizations, and references 106 Strong and, in the text on the post, Goldtooth said the video was “a partnership with the National Association of Tribal Historic Preservation Officers.”
In another video posted November 8, Goldtooth criticized the bill’s Clean Water Act, mining, and project certainty provisions in advance of the first Senate vote, which was scheduled for the next day. Again, he described the video as a “partnership” with NATHPO and referenced 106 Strong.
NATHPO and CJA did not respond to my requests for comment. Greg Werkheiser, the founding partner at Cultural Heritage Partners, the law firm that helps coordinate 106 Strong, told me that “106 Strong did not provide a script, talking points, call to action, or compensation of any kind directly or through an intermediary for those posts.”
Instead, Werkheiser said, “the issue has raised an unprecedented level of concern in this field and I've been in it for 26 years.” In fact, “neither 106 Strong nor [Cultural Heritage Partners] is paying any online influencers,” Werkheiser told me.
Other environmental influencers have also posted about the bill in collaboration with advocacy groups focused on conservation and wilderness protection.
Devon Bowker, a creator who goes by Devon The Nature Guy and has 118,000 followers on Instagram, posted a video last week opposing BAAJA’s Endangered Species Act provisions. The Reel asked viewers to click the link in his bio to write a message to their congressional representatives to oppose the bill. The video was co-posted with the advocacy group Defenders of Wildlife.
Laura Sheehan, Defenders of Wildlife’s senior vice president for external affairs, told me that they “pay creators for their time and work, just as we’d pay anyone who helps us reach people.”
She also said they help with the videos’ content, saying, “We gave creators background on our work and the key points we wanted accurately represented, including the call to action. We don’t write their posts. They tell the story their way. We just make sure the facts are right.”
Sheehan did not disclose how much compensation Devon or other creators were given.
Ross Reid, who goes by Nerdy About Nature on Instagram and has 325,000 followers, posted about BAAJA on November 4, criticizing “sneaky revisions” of the bill that “makes sweeping changes that weakens the Clean Water Act, Endangered Species Act and the National Environmental Policy Act” and “puts public lands at greater risk of extraction and development.” The video was co-posted by the environmental group Oregon Wild.
The group reached out to Reid because “there didn’t seem to be any online discussion of the bill’s harms,” Arran Robertson, Oregon Wild’s spokesperson, told me. “We did compensate him, though he did his own research and wrote his own script. He is the only creator we partnered with,” Robertson said.
When I asked Robertson how much the group paid Reid, referencing the $10,000 figure NoiseCat posted, Robertson declined to specify. “I can say that $10,000 would be several times more than our agreement with Ross,” he said.
I also reached out to several creators who posted detailed videos about the bill that didn’t cross post with other organizations or disclose a partnership in their posts to see whether they had been compensated by outside groups pushing or opposing the bill. They did not reply.
While the Federal Trade Commission maintains rules for disclosure of paid product endorsements, there aren’t analogous rules for political posts.
“I’m positive that it’s on both sides,” Erfan said, describing how creators were approaching BAAJA. “It appears to me, surprisingly, the anti-BAAJA people have more money.”


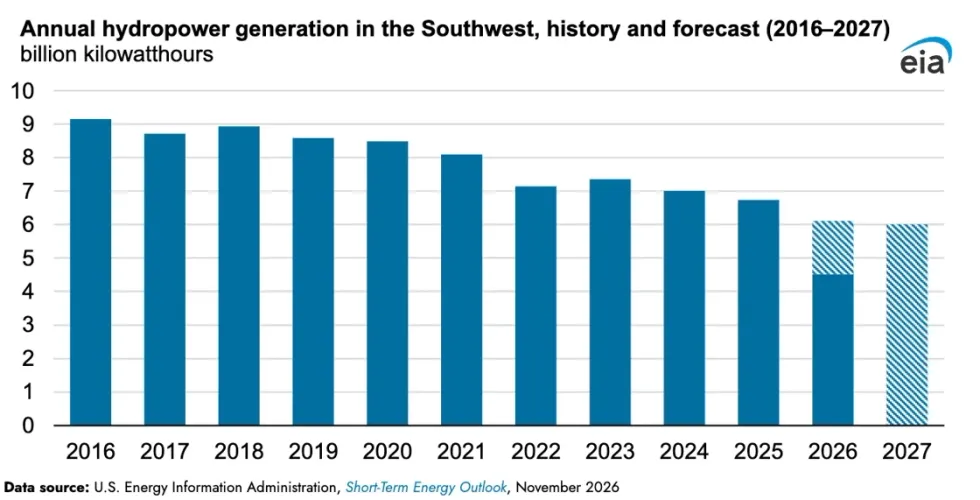 Evaporating. Chart: EIA