You’re out of free articles.
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
The all-American EV startup is cutting costs to survive.

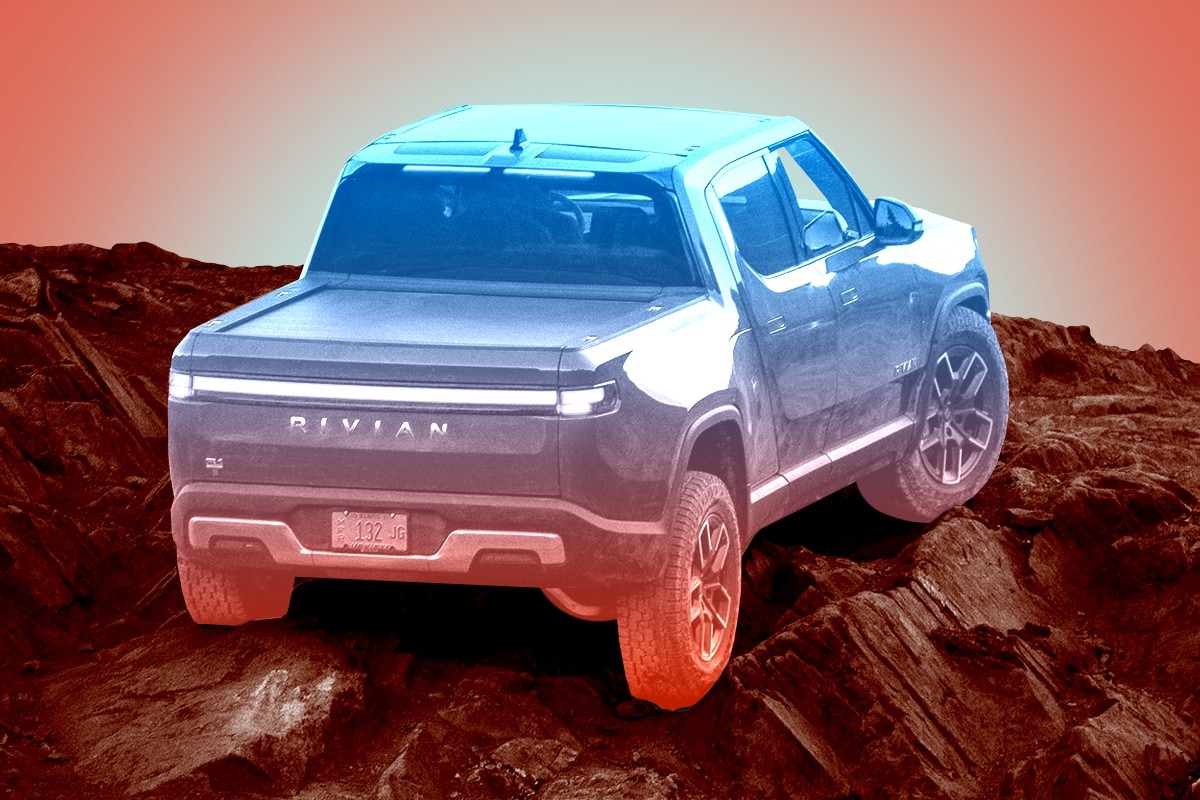
America’s most interesting electric-vehicle company is about to have the defining year of its life.
On Wednesday, the company reported that it lost $1.58 billion in the fourth quarter of last year, bringing its net annual losses to $5.4 billion. It announced that it is laying off about 10% of its salaried employees, but — at the same time — promised that it has a plan to achieve a small profit by the end of this year.
Rivian does not seem to be in trouble — not quite yet, at least. But the earnings made clear what electric-vehicle observers have known for a long time: Either the company will emerge from this year poised to be a winner in the EV transition, or it will find itself up against the wall.
That’s partially because Rivian has a stomach-turning number of corporate milestones coming up. Over the next 11 months, it plans to unveil an entirely new line of vehicles, shut down its factory for several weeks for cost-saving upgrades, break ground on a new $5 billion facility in Georgia, and — most importantly — turn a profit for the first time. It also expects to manufacture and deliver roughly another 60,000 vehicles to customers.
Any one of these goals would be difficult to achieve in any environment. But Rivian is going to have to execute all of them during a time defined by “economic and geopolitical uncertainties” and especially high interest rates, its CEO R.J. Scaringe told investors on Wednesday. Since 2021, Rivian’s once robust stockpile of cash has been cut in half to about $7 billion; at its current burn rate, the company will run out of money in a little more than two years.
Although Rivian’s situation is dire, it’s not experiencing anything out of the ordinary. As I’ve written before, the electric truck maker is crossing what commentators sometimes call “the EV valley of death.” This is the challenging point in a company’s life cycle where it has developed a product and scaled it up to production — thereby raising its operating expenses to eye-watering levels — but where its revenue has not yet increased too.
During this vulnerable period, a company essentially burns through its cash on hand in the hope that more customers and serious revenue will soon show up. If those customers don’t arrive, then it either needs to raise more cash … or it runs out of money and goes bankrupt.
It’s a frightening time, but once a company crosses the valley of death, it can reach an idyll. Not so long ago, Tesla found itself in something like Rivian’s position as it prepared to launch the Model 3. Seven years later, it is the most valuable automaker in the world.
Once Rivian’s revenue exceeds its costs, its problems will get easier, or at least more straightforward: Instead of fighting for its survival and watching its cash reserves dwindle, Scaringe will be able to make more strategic trade-offs. Should the company cut costs to expand its profit margin and reward investors, or should it pass the savings along to customers in the form of lower prices, thus growing its market share? Scaringe can’t make these types of decisions until his firm is safely out of the valley.
Claire McDonough, Rivian’s chief financial officer and a former J.P. Morgan director, has a plan for crossing that canyon — an aptly if strangely named “bridge to profitability” that it will attempt to build this year. Rivian’s survival, she said, will depend above all on cutting the unit costs of producing its vehicles, including by using fewer materials to make every car. Other savings will come from making more vehicles faster. That’s what makes the shutdown plan, though it might seem extreme, worth it; McDonough said those improvements alone will get the company about 80% of the way to profitability.
Another 15% will come from marketing more “software-enabled products” to Rivian drivers and by selling air-pollution credits to other carmakers, whose vehicles are not as climate-friendly. This is a tried-and-true technique; Tesla first turned a profit in 2021 by selling regulatory credits needed to comply with federal and California state-level rules to other, dirtier automakers. But that same year, Tesla also debuted an entirely new vehicle: the Model Y crossover, which quickly became its top seller in the United States. Tesla, in other words, finally started to make money by cutting costs, finding new revenue sources, and releasing new products.
New products, however, are becoming a weak point for Rivian. The company says that high interest rates will keep demand for its vehicles flat this year. It expects to make about 60,000 of them, about 20,000 fewer than what it had once anticipated. The Rivian R1S, a three-row S.U.V., has become the company’s flagship; it is selling better and is cheaper to manufacture than Rivian’s pickup, the R1T. It also costs at least $75,000, or nearly $600 a month to lease. The highest-tier models can cost $99,000. Turns out, it’s difficult to sell a lot of $70,000 trucks when even the cheapest new-car loans hover around 6%.
Rivian once had a first-to-market advantage in the electric three-row SUV market, but that may be fizzling out, too. Kia is now selling its own all-electric three-row SUV, the EV9, for $18,000 less than the R1S; in fact, the Kia EV9’s most expensive trim costs $76,000, which is only slightly more than the cheapest R1S. The Kia SUV can also charge faster than the Rivian under ideal conditions. It remains an open question how many rich suburbanites are still interested in buying Rivians, especially now that the Tesla Cybertruck and Ford F-150 Lightning are competing directly with Rivian’s pickup truck.
The company’s hopes, in other words, rest on its next product line: the R2, which it will launch on March 7. We know almost nothing about the R2 line, except that it will probably include an SUV, that it will go on sale in 2026, and that it will fall somewhere in the $45,000 to $55,000 price range. (The median new car transaction in the United States now costs $48,200.) Last year, Scaringe told me that the R2’s timing was perfect because it would fit “beautifully with what we see as this big shift” in the American EV market. In today’s market, he said, “a lot of people ask themselves, Am I gonna get an electric car? Well maybe the next one.” He better hope they’ll start buying that next one in 2026.
Even if they do, Rivian may still have to confront the problem that Tesla has changed the EV market before Rivian could get there. When the first Tesla Model 3s were delivered in 2017, the sedan was instantly one of the best EVs on the market — because it was one of the only EVs on the market. Now every automaker in the world has plans to compete at the Model 3’s price point.
Rivian’s fortunes don’t rest entirely on American consumers; it also sells vans to commercial fleet operators, as well as delivery trucks to Amazon. (Amazon owns about 17% of Rivian.) But that business can be lumpy. Rivian’s vehicle growth slowed down last quarter, for instance, almost entirely because of a near pause in sales to Amazon, which sets up fewer new vehicles in the fourth quarter. If Amazon is willing to bail out Rivian, in other words, it’s not yet clear in the data.
None of this is to say that the company’s outlook is dire. Rivian was always going to find itself at a moment like this, when its expenses exceeded its revenue by such a large amount. The automaker already has devoted fans, and many people — myself included — are interested in the R2 as a potential first EV purchase.
And the company has shown that it can make strides in a single year. Twelve months ago, I had never seen a Rivian on the road before; today, one is regularly parked on my block. The company rocketed from a standing start to become the No. 5 best-selling electric car brand in America last year. What the company has done so far is impressive. But now it must prove that it can be great.
Editor's note: This story has been updated to correctly reflect Rivian's cash burn rate.
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
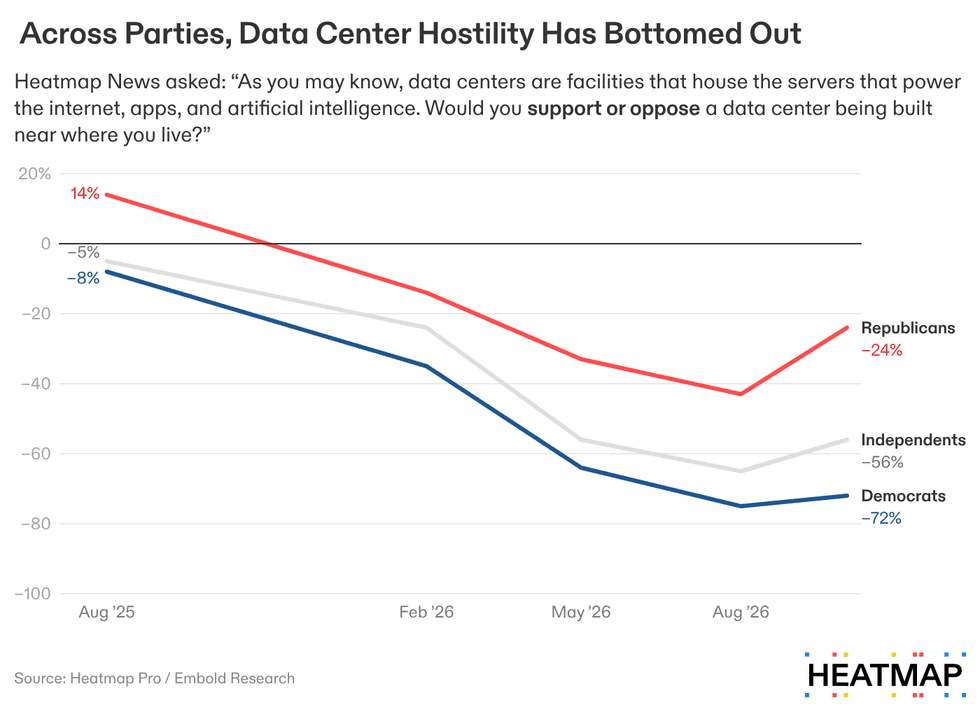
Most Americans still say they would oppose a data center being built near where they live, but the facilities’ standing has improved among Republicans, a new Heatmap Pro poll finds.
The American public’s backlash against data centers may finally be starting to slow down, although the facilities remain staggeringly unpopular, a new poll finds.
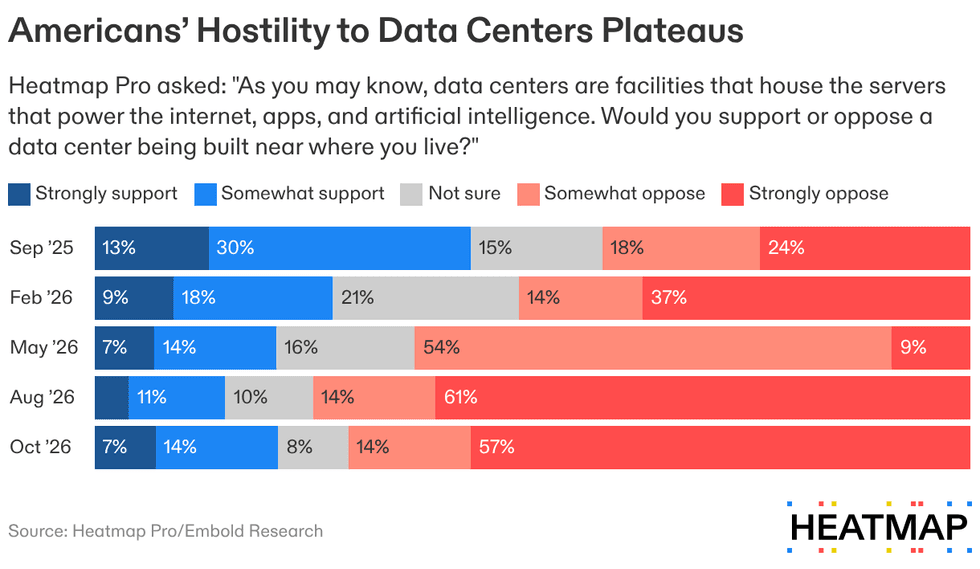
Seventy-one percent of Americans said they would oppose a data center being built near where they live, according to a new Heatmap Pro poll conducted by Embold Research earlier this month.
That is an abysmal finding for technology companies and would-be developers of the computing facilities. But it actually represents an improvement from previous polling, and it suggests one of the fastest shifts in public opinion in recent memory may be tapering off.
That shift has been swift. As recently as September of last year, about 43% of Americans said they would support a data center being built near where they live, and Americans broadly appeared to be evenly split on the infrastructure, according to Heatmap Pro polling. Eleven months later, 75% of Americans told the same poll that they would oppose a nearby data center — a 32 point shift. That monumental turnaround helped make data centers a defining issue in this election cycle.
That backlash has transformed the economics of the data center boom, the largest infrastructure buildout in recent U.S. history. The overwhelming majority of data center projects now face some degree of community opposition, Heatmap Pro reporting suggests. More than $260 billion in proposed data centers have been canceled this year after meeting local opposition. The artificial intelligence company Anthropic even flagged the infrastructure slowdown on Monday when it filed for its initial public offering, which is widely expected to be among the largest ever.
Now our new survey shows that Americans’ rejection of the enormous computing facilities may itself be slowing. The small observed drop, which only slightly exceeds the survey’s margin of error, was driven by a four-point decline in the share of Americans who said they would “strongly oppose” the technology.

While Americans of all parties improved their view of data centers, the change was most pronounced among Republicans. In August, 23% of GOP voters said that they would support a data center being built near where they live. In the new poll, conducted after weeks of favorable campaigning by President Trump, 34% of Republicans said they would support a data center slated for their area, while the share of Republicans who said they would oppose it fell from 66% to 58%. Data centers’ standing among independents improved by nine points during the same period.
Democrats remain largely unified against the infrastructure, and data centers’ improvement among that group was just outside the margin of error.
While Americans of every age, race, gender, and partisan ID remain more opposed to local data center development than in favor of it, their standing has also improved among men since the summer. In August, 21% of men said they would support a data center being built near where they live. Now, 28% of men would support one.
Will America be the land of opportunity for AtkinsRéalis’ tried-and-true CANDU?
Unruffled by President Trump’s taunts of turning Canada into the 51st state, Canadian Prime Minister Mark Carney has vowed to regain leverage over Washington by remaking his nation as an “energy superpower.” Instead of building pipelines from the oil fields of Alberta to American refineries, Ottawa will run them to its West Coast ports to sell crude directly to Asia. Rather than importing electricity from offshore wind farms in the American Northeast, Nova Scotia will build its own turbines and sell the power back to energy-starved New England as the Trump administration thwarts the region’s own buildout.
But Canada’s path to reviving its nuclear industry may run — counterintuitively — through the United States.
Last week, Montreal-based AtkinsRéalis inked a deal with utility Hoosier Energy and the Indiana government to explore building up to 6 gigawatts of reactors in the state. The agreement is only a memorandum of understanding to kick off a study examining potential sites across the state. But it marks the first real effort to export Canada’s unique pressurized heavy-water reactors, called CANDUs, to the U.S., and highlights how America’s domestic nuclear industry has atrophied to the point that foreign developers of large-scale units are racing to establish a beachhead in the world’s largest atomic power market.
“If the Americans had created the CANDU, everyone in the world would know about it,” Joe St. Julian, the American-born president of AtkinsRéalis, told me. “There’s just a cultural difference in the way that the Canadians go about things and the way the Americans do.”
Pronounced “CAN-do,” the upbeat acronym stands for Canada Deuterium Uranium and evokes the government’s post-war, can-do spirit, mustered to help protect its sovereignty during the bipolarity of the Cold War. Developed in the 1950s by Canadian government scientists and now used across the country’s entire nuclear fleet, CANDUs rely on deuterium, a version of hydrogen with an extra neutron, as their “heavy water” coolant to sustain their chains of split atoms. Uranium powers virtually all commercial nuclear reactors, but CANDUs are distinct in that they can run on the raw stuff, rather than enriched uranium. That’s their real advantage: By forgoing the costly and heavily scrutinized enrichment process, Canada can tap its vast resources of mined uranium without facing the bottleneck of the expensive enrichment facilities or attracting the intensive oversight of global regulators monitoring for the production of atomic weapons.
The 17 reactors that provide 15% of Canada’s electricity today are all CANDUs. India’s fleet largely borrowed the technology, and Argentina, China, Romania, and South Korea have all imported their own CANDUs. But the buildout largely stopped in the last century. Canada built its last CANDU in Romania in 2007. The last Canadian CANDU — Unit 4 of the Darlington nuclear plant in Ontario — came online in 1993.
Two years ago, Canada sought to restart its reactor buildout by commissioning its first American-designed unit. Construction began last year on the world’s first BWRX-300, a small modular reactor that uses enriched uranium as fuel. The U.S. plans to build the second version of the same reactor at the Tennessee Valley Authority’s Clinch River site. Whether it can deliver the cost savings SMRs promise remains an open question, given that nuclear developers have historically improved economics by making reactors bigger, not smaller.
But Chris Keefer, a Toronto physician-cum-nuclear advocate who hosts the in-depth energy podcast Decouple, told me he believes Canada’s real error is in benching the CANDU. While Ontario’s government-owned utility “got their backs slapped endlessly for having the courage to go first” in building the inaugural SMR on the continent, “they’re idiots to be investing $21 billion of Canadian ratepayers’ money to prop up an American company with American technology,” he said, colorfully characterizing the move as a massive error and “the result of dis-coordinated decision-making.” (Converted from loonies to U.S. dollars, that figure is about $14.9 billion.)
While Keefer added that he opposes the trade war between Washington and Ottawa, he also recognizes it as a potential opening. “Part of me loves it and this deglobalization moment we’re in, where strategic autonomy and national interest matter,” he said.
The Carney administration has yet to set clear rules on what kind of reactor technology it will support domestically, but it could, in theory, limit access to federal subsidies for provinces and utilities that opt for non-CANDU technologies. For now, however, there appears to be quiet agreement between the U.S. and Canada on bringing the technology south. St. Julian said the Canadian Ministry of Energy has been “very supportive” in talks about providing financing for CANDU exports to the U.S. AtkinsRéalis is also in talks with the U.S. Department of Energy, though a source familiar with that agency’s thinking cast doubt over the possibility that the Trump administration would ultimately fund a Canadian project in the U.S.
None of this was a part of AtkinsRéalis’ long game, St. Julian told me. “The U.S. had four or five of its own reactor technologies,” he said. “Why would it build a foreign technology?” But shortly after Trump returned to office, “We looked at it and realized the U.S. is down to a single large reactor technology: Westinghouse. The other three or four are no longer in business.”
That was the opening AtkinsRéalis needed. “The U.S. made clear it had the aspiration to build 300 new nuclear power stations,” St. Julian went on. “Between Westinghouse and new technologies coming online with SMRs, we said they couldn’t possibly reach their aspiration no matter how optimistic they are about the capacity and supply chain of first-of-a-kind technologies.”
So the company applied to the U.S. Nuclear Regulatory Commission for approval of the CANDU. In June, AtkinsRéalis sent the regulator a formal heads-up about its plans to file an application this past summer, and it expects to complete its second topical report for the NRC by the end of this month.
The CANDUs aren’t the only foreign reactors making a play in the U.S., though. Last month, South Korea unveiled a deal with the Trump administration to fund construction of up to six AP1000s and two APR1400s.
The CANDU does have some drawbacks that the APR1400 doesn’t. The same characteristics that let its reactors sustain fission using raw uranium also cause wear and tear that requires a significant refurbishment every 35 years. (Canada is already funding a campaign of repairs domestically.) And while a typical refueling outage for a light water reactor lasts up to two months and renovations ahead of a relicensing can take up to a year, the refurbishment process for a CANDU can take the unit offline for two years or more.
AtkinsRéalis declined to comment on its internal estimates of the cost of such a refurbishment, which is — among industry experts — widely criticized as costly. But St. Julian said the company guarantees at least two refurbishments in a CANDU’s lifetime, giving each unit a 105-year lifespan. Amortizing the costs over more than a century of electricity production, not to mention the company’s experience building units all over the world, means a CANDU is “a lot less expensive” than rival technologies, he said.
“The APR1400’s biggest advantage is the Korean industrial ecosystem,” Nana Menya Ayensu, a non-resident senior fellow at the Atlantic Council who worked on energy policy in the Biden White House, told me. “But the CANDU has lots of advantages that are specific to the technology in terms of not needing enriched fuel.”
Keefer highlighted another upside he’s acutely aware of due to his day job as an emergency-room doctor: CANDUs are particularly well-suited to batch-producing “enormous amounts” of medical isotopes, such as cobalt-60, used in cancer chemotherapy and the sterilization of surgical instruments, among other uses.
The technology is certainly attracting attention. Last month, Argentina and Romania agreed to work together on more CANDU projects. Weeks later, as I reported, Poland’s state-backed nuclear developer approved a tender for a second nuclear power station, for which it’s considering the CANDU. Last week, Turkey signed an agreement with Carney to cooperate on civilian nuclear energy, putting the CANDU in contention for the country’s second atomic power station.
And earlier this month, Atlas Atomics, a startup backed by Ohio’s Republican gubernatorial candidate Vivek Ramaswamy, raised $400 million in a Series A to commercialize its own pressurized heavy water reactor, in what Keefer dubbed in his newsletter the “AmeriCANDU.”
St. Julian said the new competition shows the unique value of the CANDU. “The difference is, we’ve been doing it for 70 years, and we spent tens of millions of dollars to perfect this technology; they’re just starting,” he said. Then he cracked a half smile. “They have the benefit of being a second movement,” he added. “But, man, we have a big head start.”
Plus, one big opportunity for climate change.
Anthropic is worried about its ability to power data centers.
While much of the company’s more-than-330-page filing for its planned initial public offering focuses on the mundane (executive compensation) and the extraordinary (“existential risks” are mentioned three times), considerable space is devoted to the problems of power.
The word “energy” appears 14 times in the section of the document laying out risks to Anthropic’s business, while “climate” or “climate change” is mentioned four times.
The overarching concern the company has is that it might not get enough power for data centers running its large language models. “Delays in securing energy, water, and other critical services for these facilities could further slow the pace at which newly commissioned compute becomes available for use,” is one representative sample from its risk factors section. The document later notes that “our business may face increased scrutiny related to these activities … including from the investment community and the local communities in which we operate,” in a later section on environmental, social, and governance standards.
Anthropic is also concerned with the pace of the energy infrastructure build-out more generally, noting “the construction of the generation and transmission infrastructure on which we depend is itself capital-intensive and exposed to labor shortages, supply chain disruptions, permitting delays, changes in interest rates, tariffs, other cost overruns, and financing constraints.” These concerns will be familiar to anyone following the debate in Washington, D.C., over permitting reform, which is also centered on making transmission easier and cheaper to build.
Later in the document, Anthropic writes that electricity policy is both highly varied across the country — “Grid-tied electrical supply, for instance, is subject to the jurisdiction of federal and state energy regulators, regional grid operators, and public utility commissions” — and also evolving, noting specifically that “environmental standards applicable to power generation continue to evolve, including as a result of changing governmental priorities and shifting public and political views regarding climate change and the appropriate treatment of various power generation sources.”
The risk of these policies is that they could result in “failure to secure access to adequate electrical power,” which could then “adversely affect our cost structure and limit our ability to scale our compute infrastructure, develop and deploy our models, and service our customers.”
Anthropic also acknowledges energy can be quite expensive, writing that costs are “largely outside of our control” and can “rise sharply during periods of peak demand or constrained supply, and such increases in energy costs could adversely affect our results of operations.”
Anthropic is the charter member of an industry group, along with Nvidia and Google, to promote and enable demand flexibility, which would reduce peak demand — and thus bring down electricity prices and alleviate the need for additional new infrastructure — by having data centers draw down their power usage when demand was at its highest. The company notes that it has also signed on to “voluntary commitments to offset the impact of our data center energy consumption on local communities and electricity ratepayers.” Already, the document says, “these commitments have increased, and we expect will continue to increase, our operating costs.”
And while the document has little to say about climate change per se and even less about sustainability and renewables, it does note that “the physical effects of climate change may increase our operating costs over time, as higher average temperatures can increase the power consumption and water usage required to cool equipment at the facilities on which we depend.”
Climate change also acts as an amplifier for potential disasters that could affect the company. “The impact of climate change may increase these risks,” the company says of “war, terrorist attacks, and other acts of political violence, or any significant natural disaster, such as an earthquake, fire, hurricane, tornado, flood, or significant power outage.”
Specifically, Anthropic calls out climate-related risk specific to the Bay Area, where it is headquartered. Or, as it bloodlessly describes it, “a region known for seismic activity and increasingly for the threat of fires.”
Otherwise, climate change and sustainability policy is largely seen as a regulatory and cost burden. For example, “regulations relating to [environmental, social, and governance] matters, including environmental sustainability and climate change, are under consideration, being adopted, or being rolled back or revised, which may impact our necessary disclosures and increase compliance costs,” and “sustainability initiatives, goals, or commitments could be difficult to achieve or costly to implement.”
It notes a variety of California, European Union, and United Kingdom climate disclosure laws “will require the dedication of significant time and resources” while also observing that “across the United States ... enacted or proposed ‘anti-ESG’ policies or legislation or have issued related legal opinions,” which could “expose any sustainability, employment, governance, or other corporate practices we adopt to the risk of litigation, antitrust investigations or challenges by federal or state authorities, and result in injunctions, penalties, and reputational harm.”
The document is far less detailed about what Anthropic and its products could do to alleviate or prevent climate change and its effects. This is not surprising for a regulatory filing concerned with disclosing corporate information and outlining risks to investors — but the filing is also supposed to explain the business opportunities it sees as well. In that regard, climate is relegated to a laundry list of potential scientific projects Anthropic’s products could be helpful with. “Claude is also being applied to pressing global problems in scientific research, drug discovery, education, and climate analysis,” it writes.
If its S-1 is any indication, there will be a lot of work to do.