You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
There isn’t one EV transition. There are two.

This has not been a good week for the electric-vehicle transition. On Wednesday, General Motors scrapped a self-imposed plan of building 400,000 electric vehicles by the middle of next year. Then it jettisoned plans with Honda to build a sub-$30,000 EV. On Thursday, Mercedes Benz announced that its profits had fallen in part due to turbulence in the EV market, and Hertz ditched a plan to have EVs make up 25% of its fleet by 2024.
Nor has the past month been much better. Ford has slowed down its EV factory build-out. Elon Musk announced that Tesla was taking a wait-and-see approach to opening its next plant, in Mexico, and The Wall Street Journal has reported that EV demand is proving weaker than once expected. Higher interest rates and, perhaps, a continued lack of public chargers now seem to be impairing the EV transition.
It’s an odd time, because while the day-to-day news is bad, the overall trend remains good — surprisingly good, even. More than 1 million EVs have been sold in America this year, and the country is likely to record 50% year-over-year EV market growth for two years in a row. That is not the usual sign of an industry in trouble. The industry is faltering, yes, but only compared to the rapid scale-up that companies once aimed for — and that the Paris Agreement’s climate targets demand. And at a global level, the news is better: The economics of batteries and trends in the Chinese and European markets leave little doubt that EVs will eventually win.
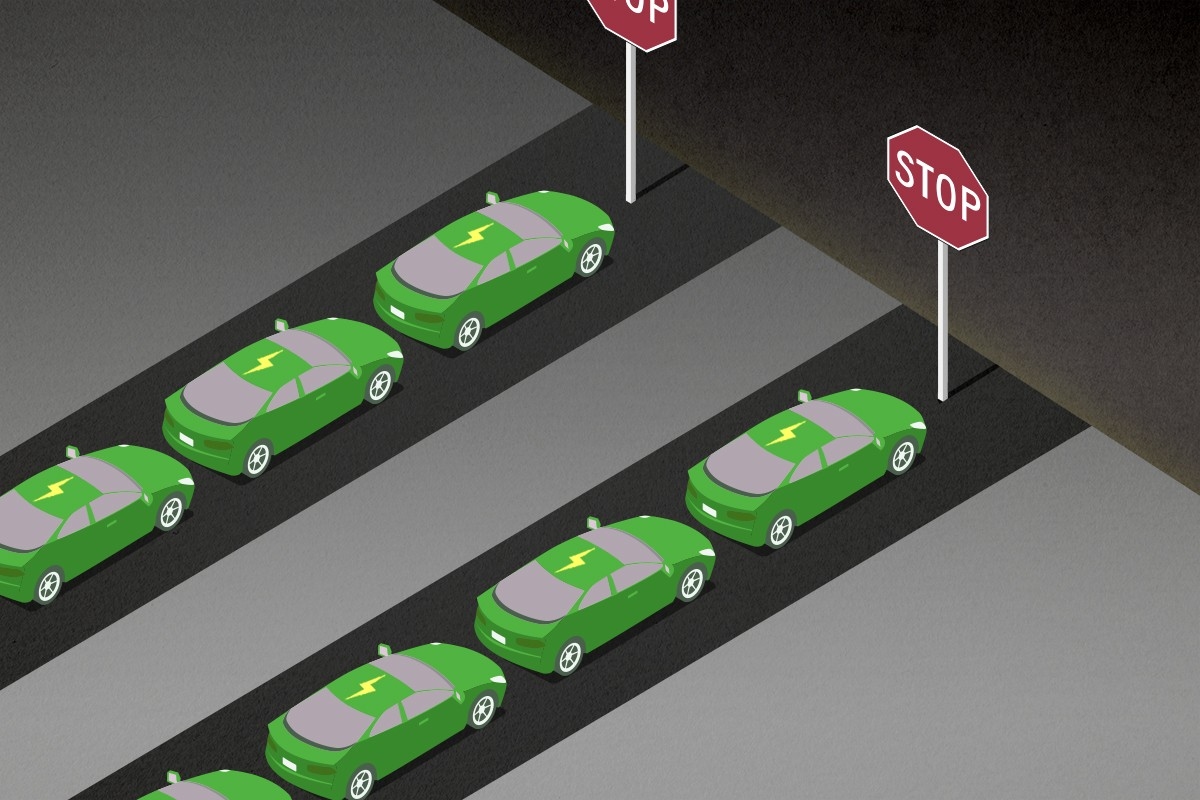
So how to make sense of this moment? Automakers, it seems, are not doubting whether the EV transition will happen; they are pausing to figure out how best to proceed. Journalists often talk about the “EV transition,” but this is something of a misnomer — there are really at least two different transitions, two different bridges to the EV future.
One of those transitions must be navigated by the legacy automakers, such as Ford and GM. The other must be completed by the new electric-only upstarts, such as Tesla and Rivian. Both transitions are, today, half-complete. What is notable about this moment is that both transitions are also in flux — and the companies and executives tasked with navigating them are struggling with their next steps.
The first bridge must be built by Ford, GM, Toyota, Volkswagen, and every other legacy automaker heavily invested in the U.S. market. You can think of it as a bridge made of cross-subsidies — subsidies not from the government, but from other cars in their product line.
Right now, many automakers earn their biggest profits by selling big, gas-burning vehicles: crossovers, SUVs, and pickup trucks. They lose money, meanwhile, on each EV that they sell. So over the next few years, these companies must take the huge profits from their SUV-and-truck business and reinvest them into scaling up their EV business.
You can see how difficult this will be by looking at Ford, which conveniently reports earnings from its internal combustion business separately from its electric vehicle business. During the first half of 2023, Ford’s global gas and hybrid sales earned $4.9 billion before interest or taxes. Ford’s EV business, meanwhile, lost $1.8 billion before interest or taxes.
During this same period, Ford sold nearly half a million trucks and SUVs in the U.S. alone, and roughly 25,000 electric vehicles. By one calculation, Ford lost $60,000 for every EV that it sold during the first quarter of this year.
This is the narrow bridge that Ford and its ilk must walk: They must remain mature businesses, delivering consistent profits to shareholders, even as they overhaul their entire product line and manufacturing system. And while these legacy automakers have certain advantages — brand cachet, a network of dealerships, and an understanding of how to make car bodies — they lack the deep familiarity with software or battery chemistries that underpin the EV business. What’s more, their current business rests on uneasy foundations: Because their profits are so heavily concentrated in just a few SUVs and trucks, a sudden shift in consumer tastes, fuel prices, or regulation could undercut their whole hustle.
We’ve already seen one consequence of this concentration in the United Autoworkers strike. By focusing its strikes on just a few factories at first, and then gradually expanding them to include each company’s most profitable facilities, the UAW was able to make its strike fund go further than outside commentators initially estimated. That strategy resulted in record high pay raises for workers in the UAW’s tentative deal with Ford; strikes continue at GM and Stellantis.
But this is, of course, only the first bridge to the EV future. Other companies — including Tesla, Rivian, and the early-stage EV startups Canoo and Fisker — have to build a different path across the river. You can think of this as the bridge of scaling up, although some auto-industry analysts give it a different name: crossing the EV valley of death.
These companies have to survive long enough to build up economies of scale. You can think of it this way: At the beginning of an EV company’s lifespan, it knows very little about how to mass-produce its EVs, but it has a lot of cash to burn. As it matures, it gets better at making EVs and grows its customer base, and it makes cars more frequently and more cheaply. Eventually, it reaches a point where it can sell lots of EVs for more money than they cost to make — that is, it can be a mature, profitable business.
But in the middle, it faces a hold-your-breath moment where its high costs can overwhelm its meager production. This is the valley of death, “the challenging period between developing a product and large-scale production, when a company isn’t earning much if any revenue, but operating and capital costs are high,” as the journalist Steve Levine puts it at The Information.
Nearly every EV company faces this problem to some extent right now. Elon Musk discussed it during a recent rambling Tesla earnings call. “People do not understand what is truly hard. That’s why I say prototypes are easy. Production is hard,” he said. “Going from a prototype to volume production is like 10,000% harder… than to make the prototype in the first place.”
Now, Tesla seems to have mostly cleared the valley of death with its Model 3 and Model Y this year, allowing it to undertake a campaign of aggressive price cuts that have increased demand while retaining some profitability.
But what Musk was talking about — and what Tesla is clearly struggling with — is the Cybertruck, which will debut next month after a multi-year delay. Musk warned that the company had “dug its own grave” by trying to build the Cybertruck and that there would be “enormous challenges” in producing it profitably and at scale.
But “this is simply normal,” he added. “When you've got a product with a lot of new technology or any brand-new vehicle program, but especially one that is as different and advanced as the Cybertruck, you will have problems proportionate to how many new things you're trying to solve at scale.”
Every other EV company finds itself on the same narrow bridge. Rivian, for instance, is somewhere further behind Tesla in general but is fast making up ground. It scaled up its production of its R1T and R1S models last quarter faster than analysts thought, but was at last report still losing money on each vehicle. Rivian’s CEO, R.J. Scaringe, told me that the company is focusing on making its next line of vehicles, the R2 series, easier and simpler to manufacture to avoid this problem.
Even further behind Rivian are Fisker, which claims to have delivered 5,000 of its Ocean SUVs, and Canoo, which is struggling to stay solvent.
What’s hard about this moment, then, is that the downsides and risks of each approach have never been clearer.
If a legacy company completes its EV transition too quickly, then it risks finding itself with a fleet of electric vehicles that the public isn’t ready to buy. Companies like Ford, GM, Volkswagen, and Toyota must scale up a profitable EV product line at the same time that they sell vehicles from their legacy business.
Worldwide, no historic automaker has transitioned fully to making battery-electric vehicles, although some have come very close: BYD, the Chinese automaker that has surpassed Tesla as the world’s biggest producer of EVs, opted to quit making internal-combustion vehicles last year, but it still sells plug-in hybrids. Volvo, too, is making an attempt: It has promised to stop selling internal-combustion cars by 2030. But Volvo is owned by the Chinese automaker Geely, meaning that both of these companies can sell their cars to a much larger and more EV-interested Chinese domestic market.
Yet the second transition is tough, too. Although it may seem that EV-only companies have a lot of freedom (by lacking a network of EV-skeptical dealerships, for instance), they also have no alternative revenue to cushion themselves through a period of soft demand — they can’t ever cross-subsidize. Although it sold buses and not private vehicles, the American EV-only vehicle maker Proterra is indicative here: It went bankrupt earlier this year after getting stuck halfway through the valley of death.
America is going to have a domestic EV industry. By the mid-2030s, most automakers will be integrated EV companies, building and selling electric vehicles that include some in-house hardware, software, and battery components. Consumers will think of their new vehicles more as technology than as a simple mode of transportation, and they will power them from ubiquitous charging stations, which will be as mundane and abundant as wall outlets are today.
That future is certain. But what kinds of cars will we be driving, and what companies will count themselves among the electric elect? I couldn’t tell you. It will all depend on what happens next — on who makes it across the narrow bridge.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Local opposition has exacted a much higher cost for developers than has been previously understood, according to new Heatmap Pro survey of public records and financial information.
The country’s largest technology companies are expected to spend more than $800 billion this year investing in data centers and artificial intelligence.
But new data suggests the local backlash to data centers may be taking a meaningful bite out of that boom.
At least $260 billion of data center investments were canceled this year after sustained local opposition, according to new Heatmap Pro data.
The pace and size of those cancellations is picking up. About $130 billion in data center investment — or about half of the total — was canceled in the three months ending on September 30. And in dollar terms, the size of canceled projects in the third quarter of 2026 exceeded the size of all data center projects canceled last year.
Roughly $1 trillion in data center investment now faces some kind of sustained or meaningful local opposition, according to Heatmap Pro data. About half of all projects that have met local backlash this year were ultimately canceled, our data suggests.
Our market intelligence service Heatmap Pro tracks local projects and regulations affecting clean energy, batteries, and data centers. We run a continuous survey of public officials, regulatory filings, and local media to monitor energy and data center cancellations nationwide.
Our investment figures, which have not been previously published and are larger than other estimates, are likely an undercount. Only about 60% of data center projects disclose the size of their planned investment, especially during a proposal’s early stage when it is most likely to run aground.
These figures also do not include every project currently stalled because of state-level data center moratoriums in Texas and New York.
But the totals show that the surging backlash to data centers is beginning to kill a sizable share of large computing projects. In August, a Heatmap Pro and Embold Research poll found that 75% of Americans would oppose a data center getting built near where they live — a striking change from a year earlier, when Americans were roughly split over the projects.
“The number of canceled data centers speaks to the vast and growing grassroots opposition to these projects in communities across the country. The fact that many of these projects were defeated in just the past few months speaks to the upward trajectory of this opposition movement,” Mitch Jones, a policy director at Food and Water Watch, an environmental group that opposes AI data centers, said in a statement.
A spokesperson for the Data Center Coalition, which advocates for the industry, did not respond before press time.
Most canceled data center projects in our database are terminated because they fail to secure a local permit or face a hostile local government action. Hundreds of U.S. counties and towns now maintain a ban or moratorium on data center construction, our data shows. The Senate’s bipartisan permitting reform proposal would not affect towns or counties’ ability to prohibit data center development under their jurisdiction.
Current conditions: Cold air is sweeping into the American Northeast after a brief blast of summer-like heat that drove temperatures in New York City up to 85 degrees Fahrenheit last week • Hurricane Nolo crossed the International Date Line, officially becoming Typhoon Nolo • The heat wave roasting Southern California is straining the grid, causing outages for more than 23,000 people in the Los Angeles area.
Greenland’s government on Monday approved the mining and decommissioning plans for Critical Metals’ Tanbreez rare earths project, which Mining.com described as one of the world’s “larger undeveloped heavy rare earth projects outside China.” The preliminary economic analysis for the mine pegged its total value at $2.1 billion, with an estimated initial capital cost of $290 million. “Approval of the Mining and Closure Plans is a defining milestone for Tanbreez and for Critical Metals Corp.,” Tony Sage, the chairman and chief executive of Critical Metals, said in a press release. “It gives us a clear framework through 2050 to responsibly develop one of the world’s largest heavy rare earth deposits, in partnership with the government of Greenland and the communities of South Greenland.”
If it goes forward, the project could be among the first major rare earths mines in Greenland, where the Trump administration has claimed the right to veto any major foreign investments as part of the deal signed with the Danish government last month, which gives Washington perpetual security oversight over the self-governing North American island. Critical Metals, notably, is headquartered in New York, though its largest shareholder is the Australian mineral investor European Lithium Limited. Yet opening a new mine in the U.S. might be getting even easier. As my colleague Matthew Zeitlin reported last week, miners — ahem — struck gold with the regulatory changes in the bipartisan permitting reform bill.
The Department of Energy is preparing to unveil $150 million in funding for a 223-mile transmission line in Alaska that would serve nearly three-quarters of the state’s population of just 735,000 people. The move, reported first by Reuters, comes as Vice President JD Vance prepares to visit the state to support Republican Senator Dan Sullivan’s bid for reelection in what’s expected to be a tight race with Democrat Mary Peltola. The total cost of the project is $400 million.
First Solar built the largest photovoltaic manufacturing business in the U.S. by churning out thin-film panels that, while less efficient than the polysilicon-based technology popularized by China, perform better in low light and high temperatures, earning a solid market among utility-scale developers. But now Chinese manufacturer JA and its subsidiaries are allegedly muscling in on thin film — as is American Panel Solutions, a wholly owned U.S.-based subsidiary of the polysilicon giant Corning. First Solar now accuses the companies of illegally infringing its patent for manufacturing its solar cells, according to PV Tech. The Ohio-based giant has previously sued Jinko, Canadian Solar, T1 Energy, and Trina Solar. First Solar won a key preliminary victory in January.
Sign up to receive Heatmap AM in your inbox every morning:

Starbucks has abandoned or watered down green targets and let go its sustainability staff as the coffee and food chain looks to cut $2 billion in costs. On Monday, the Financial Times reported that the company had revised or dropped pledges to halve water use and waste, and placed a target of slashing carbon emissions by 50% under review. While the pullback comes amid a broader retreat from environmental goals under the Trump administration, other coffee companies are still seeking to reduce pollution. Just yesterday, I told you that Keurig Dr. Pepper had come out with a version of its individual instant coffee pods that uses seaweed instead of plastic.
Type One Energy has raised a $200 million Series B as the startup races to develop the world’s first fusion power plant at the Tennessee Valley Authority’s Bull Run site in eastern Tennessee. The financing round was co-led by Breakthrough Energy Ventures and Clutterbuck Capital, with additional backing from Lowercarbon Capital, Siemens Energy Ventures, and SiteGround Capital. “The breadth and quality of investors in this funding round demonstrates growing support for our strategy to industrialize the commercial deployment of fusion energy,” Christofer Mowry, Type One Energy’s chief executive, said in a statement. “The Series B financing enables us to remain focused on advancing our stellarator technology and Project infinity design activities.”
The company has been working to establish its supply chain. In March, my colleague Katie Brigham broke news of a deal to start getting the material needed for its reactors.
New York City is notorious for the ways in which trash piles up on our sidewalks and evaporates into foul smelling mist during the hot summer days. But did you know it’s also piling up in the places we send it? The latest draft of the city’s once-in-a-decade management plan for solid waste indicates that the landfills receiving much of the five boroughs’ trash are filling up. Per Inside Climate News, the state is projected to run out of landfill capacity for the city’s garbage within 16 to 25 years.
The startup’s system builds on a vessel’s existing engine and makes it effectively fuel-agnostic.
The shipping industry has a dilemma. The European Union and other jurisdictions are increasingly requiring vessels to cut their carbon emissions, pushing shipowners toward lower-carbon fuels and away from traditional bunker fuel or diesel. But it’s still anybody’s guess which cleaner fuel — ammonia, methanol, or liquified natural gas — will prove most economical and efficient at scale. That leaves shipowners facing an uncomfortable choice: They must decide on a technology around which to build new engines and retrofit existing ones without knowing whether the fuel they bet on today will still be the best option a few years from now.
Blaze Energy says that its product will eliminate that choice. The startup, which announced a $6.5 million seed round on Tuesday — is making a compact fuel “reformer,” a device that uses a heated catalyst to split various alternative fuels into a hydrogen-rich gas. That gas can then be combined with the original fuel and conventional shipping fuel to power existing engines. With Blaze’s bolt-on retrofit, which the startup aims to make less than a tenth the size of the engine itself, shipping companies “can adjust their assets based on how the global energy landscape, regulation, as well as their company direction is changing,” the company’s CEO and co-founder, Rok Sitar, told me. For example, maybe LNG looks cheapest in the short term given its established supply chain, but ammonia could win out down the road.
So far, Blaze has conducted small scale demonstrations showing that its proprietary catalyst can reform ammonia, methanol, and LNG. The resulting hydrogen-rich mixture is extremely fast-burning, which helps the other fuels to burn more completely and efficiently than they otherwise would.
Blaze’s first product, however, focuses solely on ammonia reformation. The system works by diverting a portion of the liquid ammonia to flow over the startup’s electrically-heated catalyst, which breaks it down into hydrogen and nitrogen. The resulting gas goes directly into the engine, where the nitrogen passes through and exits via the exhaust, while the hydrogen helps the remaining ammonia burn more efficiently alongside conventional shipping fuel. No burners or complex gas separation systems required.
As Sitar explained, “a certain composition of ammonia and hydrogen burns just like diesel,” allowing Blaze to essentially “trick the engine” into operating like it’s burning just diesel or standard bunker fuel rather than a blend that includes hydrogen and ammonia. That means the startup can add its retrofit system onto an existing ship engine without modifying the engine itself. And if the reformer fails for any reason, the ship can simply revert to running on conventional fuel alone. Sitar said this fail-safe feature lowers the risk for shipowners considering Blaze’s tech.
The company’s strategic partners include vessel owner and operator Lomar Shipping, which expects to pilot the system at sea beginning sometime next year, and ship management consultancy Link Marine, which plans to offer it to tanker operators. Blaze is aiming for commercial rollout in 2028.
Retrofitting the existing global fleet represents “an enormous opportunity” for Blaze, Sitar told me. As he explained, there are roughly 100,000 vessels in the global commercial fleet, but the industry only builds about 1,500 new ships each year. And because shipping companies are unlikely to choose alternative-fuel engines for every new vessel they order, a company in Blaze’s position pretty much has to drum up demand among the ships already in the water. The startup aims to install its system when vessels enter “dry dock” for routine inspection and maintenance, which typically happens at least once every five years.
Blaze is also developing a version of its product for new-builds, however, working with engine manufacturers to integrate its fuel reformer hardware into both conventional ship engines as well as those already designed to run on ammonia. Even in ammonia-burning engines, Sitar said Blaze’s system will improve fuel efficiency thanks to the fast-burning hydrogen in its blend.
The startup has ambitious goals for its seed round, which Sitar says should carry it through the next 18 months. Those include proving out its ammonia reformer on land with unnamed “leading” engine manufacturers, validating its performance at sea with Lomar, securing the maritime certifications needed to launch its first commercial product, and expanding its operations and headcount in the U.S. and Norway.
Blaze will likely look to raise again around 2028, at which point the International Maritime Organization expects to have its Net-Zero Framework in place. This would establish legally binding requirements for the entire shipping industry to reduce its emissions intensity, with the goal of reaching net-zero by 2050. The agency expected to adopt the framework last October, but delayed a final vote to approve the measure after the Trump administration strong-armed nations into withdrawing their support. The framework will come up for a vote again this December.
While the ongoing ambiguity has become a headache for the industry as a whole, Sitar sees it as something of an advantage for Blaze, which, he said, “thrive[s] in uncertainty.” Around 2028, the startup aims to begin piloting its broader multi-fuel technology, which can reform not just ammonia, but also methanol and LNG, for use in diesel engines. Blaze also expects to begin delivering its first commercial ammonia retrofit systems at this time.
From there on, the company sees a path to adapting the technology across numerous other industries reliant on combustion engines, such as heavy equipment, mining, industrial heat, and diesel power generation for data centers. “By proving our system in maritime engines, we can very easily translate this into other hardware sectors,” he said. Shipping, in his view, is perhaps the most challenging but strategically useful beachhead market of all, from both a technical and regulatory perspective.
As he put it to me, “if you prove it on maritime shipping, you basically have a product that can be deployed anywhere else, because everything else is simpler and has less regulation.”