Essentially, do what the Chinese did.
While the U.S. struggled for 15 years to complete its first two Westinghouse AP1000s, the 1.1-gigawatt units designed at the dawn of this century to be America’s flagship nuclear technology, China built four in the same time period. Beijing then reverse-engineered the technology to make its own version with an entirely domestic supply chain. China now has 10 operating Hualong One reactors and at least 37 more on the way. The U.S. ultimately completed its first two AP1000s at Southern Company’s Alvin W. Vogtle Electric Generating Plant in eastern Georgia right around the same time.
The Nuclear Company was formed by hiring former managers who oversaw the Georgia project. Despite the Trump administration’s pledge to finance construction of at least 10 more large nuclear reactors, the only projects that have broken ground are new, first-of-a-kind small modular reactors that skeptics fear will face the same billion-dollar cost overruns that the AP1000s faced at Plant Vogtle — but without the same output of electricity to balance out the expenses.
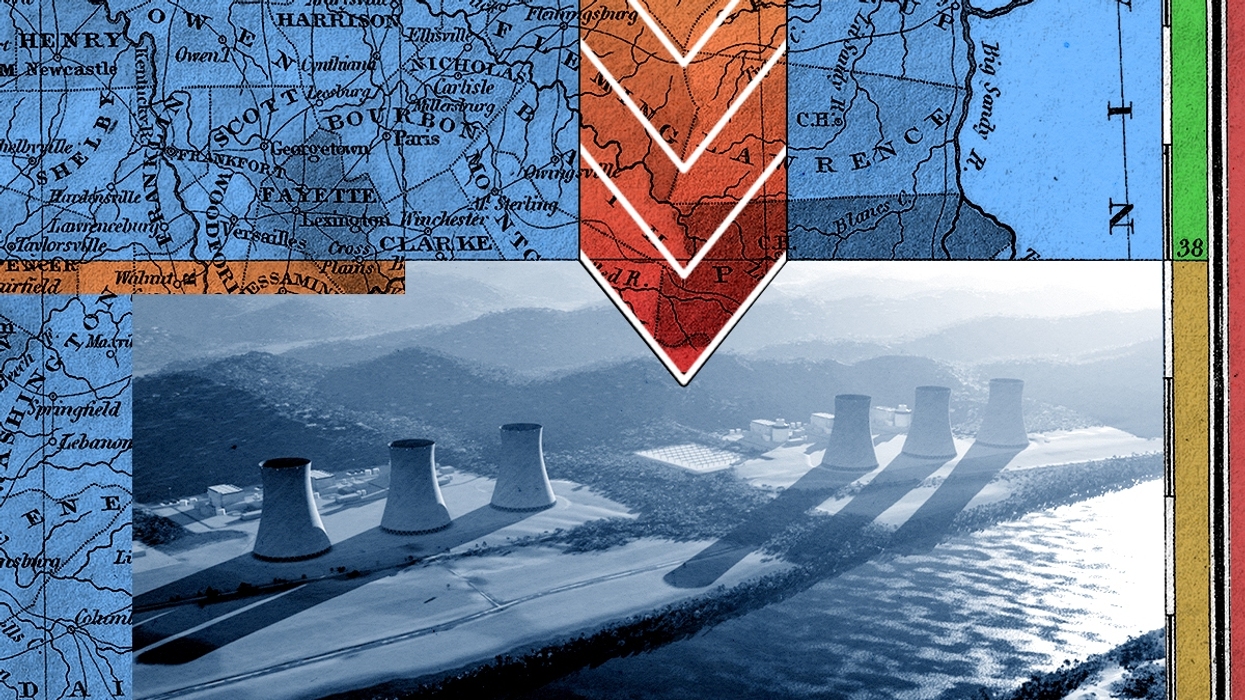
On Wednesday morning, The Nuclear Company announced its most significant attempt at a Chinese-scale buildout yet. The firm unveiled plans to build 6.6 gigawatts of new, large-scale reactors at a greenfield site in Kentucky, along the Ohio River. Dubbed Prosperity One, the project would be located in Lewis County, on property once assembled for a coal-fired station that was later abandoned. The site sits half a mile from a 765-kilovolt transmission line that connects to PJM Interconnection, the nation’s second-largest and arguably most stressed grid system.
“Our entire company was built for this purpose,” Joe Klecha, The Nuclear Company’s chief nuclear officer and a former manager on the Plant Vogtle buildout, told me. “We recognize that this is different and unique in our country. We believe it’s very much needed.”
The project will begin with two reactors at a time; the Kentucky site has room for up to six. The Nuclear Company is already negotiating potential offtake agreements with electricity buyers to help finance construction, and it expects deals by next year. The company told me it has not yet decided whether it will run the Prosperity One as an independent power provider or sell the facility to a utility or another plant operator. “We are preserving all options and will make that decision as we pull the other partners onboard formally,” Klecha said.
Since its inception, The Nuclear Company has focused on the AP1000 as the most promising design in the U.S. That’s particularly true after the Nuclear Regulatory Commission certified the Vogtle Unit 4 design last week as the permanent, settled schematic for future AP1000s.
But Klecha left open the possibility of another technology. “The AP1000 is our basis for the site at this point, but we’ll continue to evaluate other options as we get through the site characterization,” he said. He expects that process to wrap up in “the first half of next year.”
The company’s options are limited, though. Last month, as I reported, South Korea agreed to help the U.S. build up to six new AP1000s at an as-yet-unspecified site in addition to constructing at least two APR1400s — that is, essentially the Korean version of the American technology. In theory, The Nuclear Company could build APR1400s, too. But it’s highly unlikely, since Westinghouse accused the state-owned Korea Electric Power Corporation of ripping off its technology for the APR1400 in 2022. That led to a yearslong lawsuit and settlement that gave the American company the right to demand royalties and keep Seoul out of markets where Westinghouse aims to compete.
The only other viable option is the ABWR. The world’s first so-called advanced reactor, the ABWR was built with General Electric’s boiling water reactor technology, which is used across about a third of the U.S. fleet. It serves as the second-most popular design after Westinghouse’s pressurized water reactor model. Japan successfully built four ABWRs over a decade from 1996 to 2006, and Taiwan nearly completed two before killing the project in a bid to phase out nuclear power altogether. The NRC certified the ABWR for construction in the U.S., but a project in southern Texas that aimed to build the first in the U.S. was scrapped about a decade ago.
“The ABWR has an impressive pedigree of construction success as well as experience being built to U.S. standards that is hard to find outside of the Vogtle project,” Brett Rampal, a veteran nuclear consultant who advises Deloitte and Veriten, told me. Still, he said, the AP1000 is the leading contender for the Kentucky site.
Rampal said Prosperity One represents a welcome break from how large-scale reactors have been planned in recent years. While most of the industry remains focused on small modular reactors, research I covered last month indicates the technologies could face worse cost problems than large-scale units, and the emerging consensus on building AP1000s focuses on expanding existing nuclear plants.
Indeed, The Nuclear Company’s first major deal was to help Brookfield Asset Management, which owns 51% of Westinghouse, complete a thwarted AP1000 project at the V.C. Summer plant in South Carolina. But other potential sites considered for new AP1000s included expansions of Florida Power & Light’s Turkey Point nuclear plant in Florida, the Tennessee Valley Authority’s Bellefonte nuclear station in Alabama, or even adding another two units to Plant Vogtle.
“A lot of the thoughts around AP1000s and large reactors have always been around existing or already-licensed sites,” Rampal said. “It’s very interesting to see TNC’s first project buck the trend of what folks have been talking about around the large reactor story in this country."
At least one thing is certain about The Nuclear Company’s approach: It will settle on one design. The company is animated by the need to avoid one of the U.S. nuclear industry’s biggest financial mistakes, known simply and derisively as “Whoops.” In 1983, the Washington Public Power Supply System — WPPSS — triggered what was then the largest municipal bond default in U.S. history after its buildout of several different reactor designs at once fell apart in a major boondoggle.
Building different reactors at Prosperity One “really goes against our mission, our vision, and our thesis as a company,” Klecha confirmed.
The key is repeating the same design over and over again so the project managers sort out the fastest, most efficient ways to build and workers hone skills in actually constructing the design. “Six AP1000 units on one site creates the scale and repetition needed to drive down costs and sends a strong signal to the supply chain,” Lin Yuan, the senior advisor at the Nuclear Scaling Initiative, a non-profit collaboration working to create the enabling commercial and policy conditions for safe and secure nuclear energy scaling, told me in an email. “Manufacturers and craft labor need to see a sustained order pipeline to invest in capacity, factory expansion, and training.”
Vogtle Unit 4 came online in 2024 roughly 30% cheaper and faster than Vogtle Unit 3, completed a year earlier. Klecha said that’s the minimum cost reduction The Nuclear Company expects for the first two reactors built at Prosperity One.
“The 30%, I would say, is the floor on the savings from the first unit to the second unit,” he said. “How do we capture those lessons? Obviously, our team’s experience. We have a pretty rigorous ‘lessons learned’ document.”
Soon, he hopes, there will be even more lessons learned — in concrete, rather than on paper.


 Seems significant. CGEP