Certainty, certainty, certainty — three things that are of paramount importance for anyone making an investment decision. There’s little of it to be found in the renewable energy business these days.
The main vectors of uncertainty are obvious enough — whipsawing trade policy, protean administrative hostility toward wind, a long-awaited summit with China that appears to have done nothing to resolve the war with Iran. But there’s still one big “known unknown” — rules governing how companies are allowed to interact with “prohibited foreign entities,” which remain unwritten nearly a year after the One Big Beautiful Bill Act slapped them on just about every remaining clean energy tax credit.
The list of countries that qualify as “foreign entities of concern” is short, including Russian, Iran, North Korea, and China. Post-OBBBA, a firm may be treated as a “foreign-influenced entity” if at least 15% of its debt is issued by one of these countries — though in reality, China is the only one that matters. This rule also kicks in when there’s foreign entity authority to appoint executive officers, 25% or greater ownership by a single entity or a combined ownership of at least 40%.
Any company that wants to claim a clean energy tax credit must comply with the FEOC rules. How to calculate those percentages, however, the Trump administration has so far failed to say. This is tricky because clean energy projects seeking tax credits must be placed in service by the end of 2027 or start construction by July 4 of this year, which doesn’t leave them much time left to align themselves with the new rules.
While the Treasury Department published preliminary guidance in February, it largely covered “material assistance,” the system for determining how much of the cost of the project comes from inputs that are linked to those four nations (again, this is really about China). That still leaves the issue of foreign influence and “effective control,” i.e. who is allowed to own or invest in a project and what that means.
This has meant a lot of work for tax lawyers, Heather Cooper, a partner at McDermott Will & Schulte, told me on Friday.
“The FEOC ownership rules are an all or nothing proposition,” she said. “You have to satisfy these rules. It’s not optional. It’s not a matter of you lose some of the credits, but you keep others. There’s no remedy or anything. This is all or nothing.”
That uncertainty has had a chilling effect on the market. In February, Bloomberg reported that Morgan Stanley and JPMorgan had frozen some of their renewables financing work because of uncertainty around these rules, though Cooper told me the market has since thawed somewhat.
“More parties are getting comfortable enough that there are reasonable interpretations of these rules that they can move forward,” she said. “The reality is that, for folks in this industry — not just developers, but investors, tax insurers, and others — their business mandate is they need to be doing these projects.”
Some of the most frequent complaints from advisors and trade groups come around just how deep into a project’s investors you have to look to find undue foreign ownership or investment.
This gets complicated when it comes to the structures involved with clean energy projects that claim tax credits. They often combine developers (who have their own investors), outside investment funds, banks, and large companies that buy the tax credits on the transferability market.
These companies — especially the banks, which fund themselves with debt — “don’t know on any particular date how much of their debt is held by Chinese connected lenders, and therefore they’re not sure how the rules apply, and that’s caused a couple of banks to pull out of the tax equity market,” David Burton, a partner at Norton Rose Fulbright, told me. “It seems pretty crazy that a large international bank that has its debt trading is going to be a specified foreign entity because on some date, a Chinese party decided to take a large position in its debt.”
For those still participating in the market, the lack of guidance on debt and equity provisions has meant that lawyers are having to ascend the ladder of entities involved in a project, from private equity firms who aren’t typically used to disclosing their limited partners to developers, banks, and public companies that buy the tax credits.
“We’re having to go to private equity funds and say, hey, how many of your LPs are Chinese?” David Burton, a partner at Norton Rose Fulbright, told me. This is not information these funds are typically particularly eager to share. If a lawyer “had asked a private equity firm please tell us about your LPs, before One Big Beautiful Bill, they probably would have told us to go jump in the lake,” Burton said.
Still, the deals are still happening, but “the legal fees are more expensive. The underwriting and due diligence time is longer, there are more headaches,” he told me.
Typically these deals involve joint ventures that formed for that specific deal, which can then transfer the tax credits to another entity with more tax liability to offset. The joint venture might be majority owned by a public company, with a large minority position held by a private equity fund, Burton said.
For the public company, Burton said, his team has to ask “Are any of your shareholders large enough that they have to be disclosed to the SEC? Are any of those Chinese?” For the private equity fund, they have to ask where its investors are residents and what countries they’re citizens of. While private equity funds can be “relatively cooperative,” the process is still a “headache.”
“It took time to figure out how to write these certifications and get me comfortable with the certification, my client comfortable with it, the private equity firm comfortable with it, the tax credit buyer comfortable with it,” he told me, referring to the written legal explanation for how companies involved are complying with what their lawyers think the tax rules are.
Players such as the American Council on Renewable Energy hope that guidance will cut down on this certification time by limiting the universe of entities that will have to scrub their rolls of Chinese investors or corporate officers.
“It’d be nice if we knew you only have to apply the test at the entity that’s considered the tax owner of the project,” i.e. just the joint venture that’s formed for a specific project, Cooper told me.
“There’s a pretty reasonable and plain reading of the statute that limits the term ’taxpayer’ to the entity that owns the project when it’s placed in service,” Cooper said.
Many in the industry expect more guidance on the rules by the end of year, though as Burton noted, “this Treasury is hard to predict.”
In the meantime, expect even more work for tax lawyers.
“We’re used to December being super busy,” Burton said. “But it now feels like every month since the One Big Beautiful Bill passed is like December, so we’ve had, like, you know, eight Decembers in a row.”
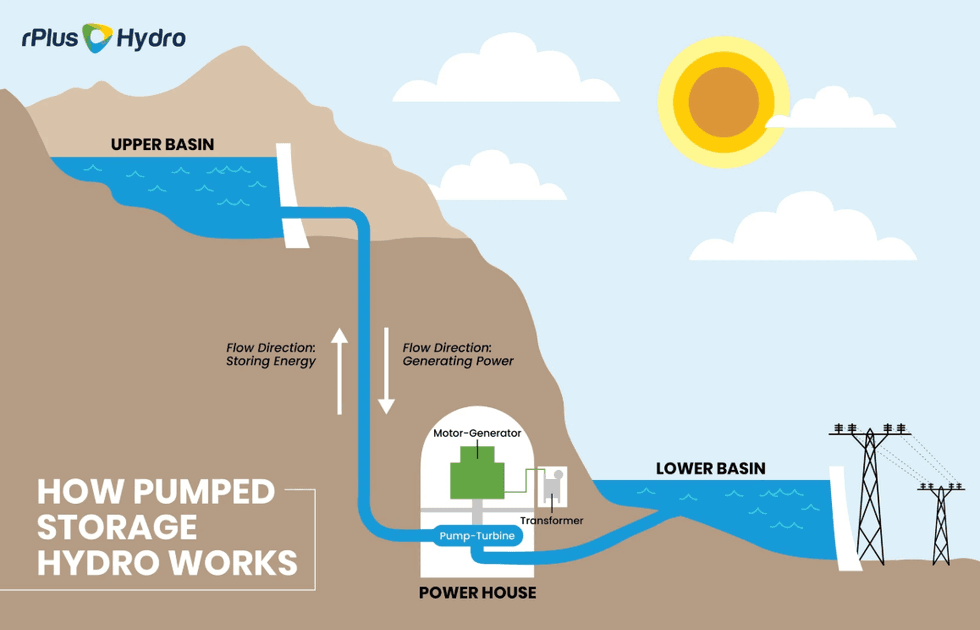 How the Seminoe pumped hydro project would work.rPlus Hydro