Most of the time, the hot, wealthy, coutured-up real estate agents on the hit Netflix series Selling Sunset make selling luxury homes in the Los Angeles hills look like a breeze. The only adversity the Oppenheim Group girls seem to face is inter-office drama over perceived slights, blown out of proportion by savage gossip and likely invented for the cameras.
But in the new season that premiered last week, one of the agents pulled back the veil, just for a moment, on a problem that’s starting to give their high net worth buyers pause: fire insurance.
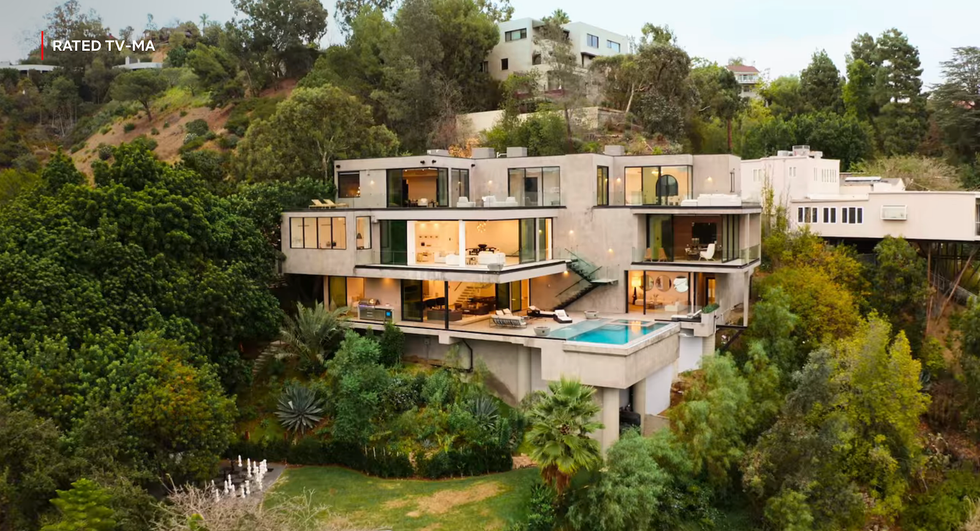
In the first episode, agent Emma Hernan throws an open house for brokers at a palatial, $19 million home in Beverly Hills. The modern, 5-bed, 9-bath, has “unobstructed jetliner views from every room,” a “fingerprint-secured Mezcal/Wine tasting room,” an infinity pool, a Himalayan salt sauna, a Japanese soaking tub, a wet steam room, a poolside cabana, a 20-person theater with a bar, and a tacky-as-hell human-sized chess set.
 Emma Hernan's listing, 9406 Lloydcrest Dr. in Beverly HillsScreenshot/Netflix
But the house, with its opulent amenities and epic vistas, is tucked into a private hillside surrounded by trees. “When you buy a property in this area, the fire insurance and things along those lines can be pricey,” Hernan tells a group of agents gathered on the balcony.
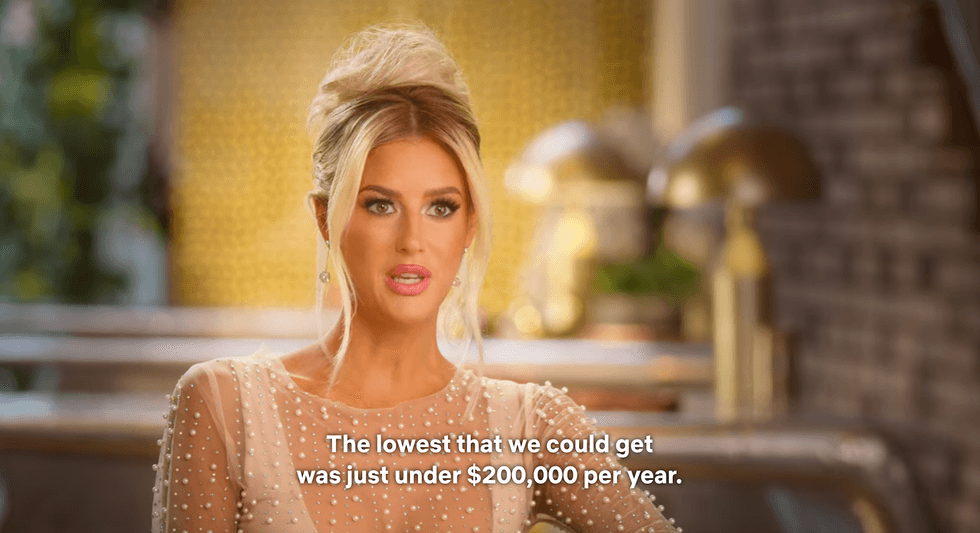
It turns out, Hernan is throwing the event because the original buyer she lined up fell out of escrow after finding out the fire insurance on the house was going to cost an eye-popping $200,000 per year, minimum.
As she tells the other agents the number “isn’t that crazy for a house in the Hills,” they nod knowingly. “But they expected it to be like $40,000, which isn’t going to happen.”
 Screenshot/Netflix
It’s a wild example of what’s going on in the California insurance market right now, where many homeowners are seeing their rates skyrocket, if not getting dropped from their plans altogether, while others can’t find anyone willing to sell them a policy to begin with — no matter how much they are willing to spend.
“There's some people that cannot get it,” Shelton Wilder, a luxury real estate agent in Los Angeles, told me. “And they checked everywhere and so they just don't have insurance on their home.”
This is a pretty recent phenomenon. A 2021 report by the University of California, Berkeley, Center for Community Innovation traces how fire insurance payouts rose dramatically in the last decade due to continued development in high-risk areas and climate change driving more severe burns. It notes that in the latter half of last century, the industry paid an average of $100 million per year in fire insurance claims in the state. But between 2011 and 2018, that number exploded to an average of $4 billion per year. During the particularly bad wildfire seasons of 2017 and 2018, companies paid out two times in incurred losses what they made in earned premiums.
The following year, there was a 31 percent jump in policy non-renewals statewide, mainly in areas with high wildfire risk, according to the California Department of Insurance. Insurers began retreating from some parts of the state altogether. Last week, State Farm, the largest provider of home insurance policies in the country, put a freeze on new applications in the entire state of California.
“It used to be a negligible part of the home purchase process,” another L.A. real estate agent, Brock Harris, told me. “You would just call State Farm and get a policy and whatever, they all kind of cost the same. In a lot of areas it’s suddenly a big part of the analysis of whether the home is affordable. It's kind of crazy.”
Brock’s wife and partner, Lori Harris, had a similar experience to Hernan, the Netflix star. Her client put an offer on a house in Mandeville Canyon, a ritzy hillside neighborhood where Gweneth Paltrow, Dr. Dre, and Lachlan Murdoch have all bought homes. But then she found out the fire insurance was going to be $100,000. “Obviously it was a huge deterrent,” said Harris. “It spooked her. We have clients who won’t look at Mandeville because of the history of evacuations. There’s only one road down so they get freaked out by it.”
It’s not just higher fire risk that’s driving up premiums. Supply chain issues, labor shortages, and inflation are all making the rebuild process a lot more costly.
Many Golden State residents who can’t find insurance on the market are eligible for coverage through a state-mandated program called the California FAIR Plan, but the premiums are on average much higher. The average market insurance in Los Angeles goes for about $1,500 per year, but the FAIR Plan costs an average of $3,200. (FAIR Plan policies only cover up to $3 million.)
Last year, in an attempt to increase access to coverage, the California Department of Insurance issued first-in-the-nation rules requiring insurers to give discounts to property owners that reduce their wildfire risk, like installing a fire-resistant roof or clearing debris around the structure.
As for the house in Beverly Hills? One year later, it’s still on the market. But it got a $6 million price cut — or the equivalent of those fire insurance payments over the course of a 30-year mortgage.


 Emma Hernan's listing, 9406 Lloydcrest Dr. in Beverly HillsScreenshot/Netflix
 Screenshot/Netflix