You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
We’re still coming to terms with Winter Storm Elliot.

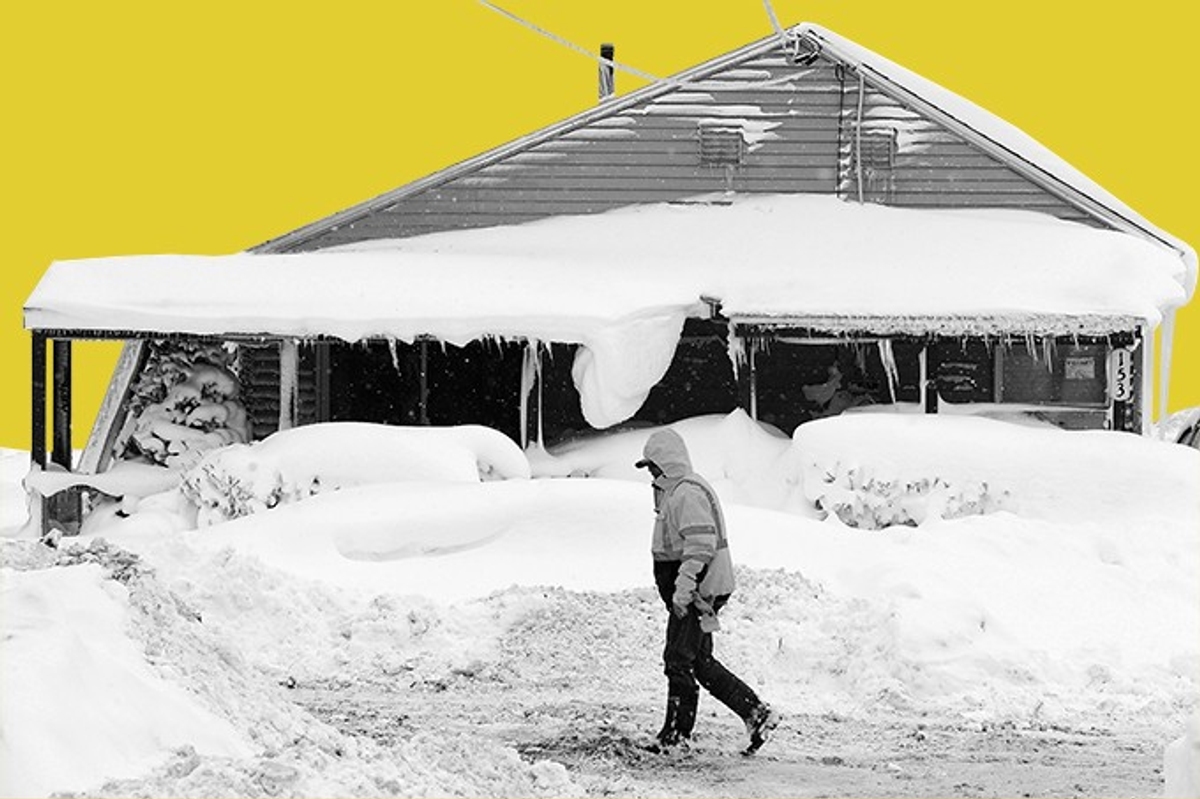
It’s been almost 10 months since deadly Winter Storm Elliot left a deep freeze over much of the country, resulting in widespread blackouts right before Christmas.
And ever since, electricity companies have been squabbling over the fallout with PJM Interconnection, the sprawling electricity market that stretches from the mid-Atlantic coast to the Midwest. About a quarter of the market’s capacity fell offline during the storm, with most of the blame falling on natural gas plants that were unable to deliver power. Penalties that PJM extracted from these plants drove some to bankruptcy while others went to federal energy regulators to say the penalties were too high.
Finally, on Friday, the parties told the Federal Energy Regulatory Commission that they were ready to settle. The settlement, if approved, would reduce the penalties from $1.8 billion to around $1.2 billion, which also means shaving payments to generators who were able to stay online during the storm by about a third.
But it probably won’t be the end of the story. Both the widespread failure during Elliott and the resulting tussle over how to pay for it underline just how hard it is to guarantee reliability, especially as the country becomes more electrified.
Generally, reliability on the electric grid is guaranteed by natural gas plants, which are supposed to be able to easily switch on and off to generate power when they’re needed most. In fact, about 40% of our electricity comes from natural gas. But you see the problem: When the gas system goes down, households lose access to heating, provided by natural gas directly via furnaces or by electricity via heat pumps. In the winter this means people will die.
And natural gas really did fall to pieces during the storm. According to a PJM report, “outages on gas units were primarily attributed to physical plant issues,” both because the cold made power plants inoperable and because the distribution network itself seized up, leaving gas plants unable to access the fuel they needed to produce power. This is similar to what happened during 2021’s Winter Storm Uri, a deep freeze that led to days of power outages in Texas that claimed over 200 lives.
Both situations suggest a few things: First, we need better forecasting. FERC said in its own review of the power outages that forecasts by grip operators underestimated how much electricity would be needed at peak times during the storm, in some cases by more than 10 percent.
Second, natural gas plants might not be as reliable as they’re supposed to be — and it’s unclear where the money will come from to make them more resilient.
And third, that merely incentivizing energy markets and individual generators to get this right only goes so far — huge portions of the generation fleet were unable to cope with the high demand for power, even at the risk of massive (if slightly reduced) penalties.
Electricity markets might need a little more oversight.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
The additional clean capacity would represent nearly 3% of North America’s existing total.
North America has about 37.5 gigawatts of total virtual power plant capacity, according to energy consultancy Wood Mackenzie’s latest estimate, published last year. That capacity is spread across roughly 2,000 VPPs, which aggregate distributed energy resources like batteries, smart thermostats, and heat pumps to cut, shift, or supply electricity when the grid is under strain — effectively turning them into a single, coordinated power plant.
On Thursday, Google and VPP operator Voltus announced plans to add another 1 gigawatt of clean capacity over the next three or four years — or nearly 3% of North America’s existing total. Under Voltus’ “bring your own capacity” model, Google will fund the VPP to help meet its booming data center power needs, while Voltus will enroll businesses and households across the PJM Interconnection, the notoriously overstrained grid region spanning parts of the Midwest and Mid-Atlantic, compensating them for their participation either directly or through electricity bill credits.
The announcement expands on a three-year, 100-megawatt deal the two companies signed in June, extending their commitment through 2040. Voltus CEO Dana Guernsey told me that the smaller deal gave the companies a starting point for a much more ambitious partnership. “It’s a lot easier to explain to people how you’re going to 10x if you’ve already 1x, and so we had to start somewhere,” she said. “We always had our eyes set on bigger things.”
Earlier this month, Voltus closed an oversubscribed $225 million Series D round led by Generation Investment Management to scale its VPP portfolio to 20 gigawatts by 2030. The first phase of the Google partnership is also oversubscribed, Guernsey told me. While that flexible power won’t come online until next year, this means Voltus has already lined up over 100 megawatts of accredited capacity that PJM can count on to deliver when needed, much as it would a natural gas plant or solar-plus-storage installation.
In the meantime, the VPP operator says its broader PJM portfolio has already demonstrated what it can do. Last week, an unseasonably warm stretch of fall weather required PJM to activate its Emergency Load Response Program twice. With 46 gigawatts of generation offline for planned maintenance or construction and another 15 gigawatts unexpectedly unavailable, “distributed resources came through,” Guernsey posted on LinkedIn. “This is how a modern grid should work.” Based on preliminary data, she told me that Voltus delivered about 105% of its committed load reduction during the events.
And VPPs can do more than help avert emergencies. Grid operators are increasingly calling on distributed resources for routine grid management too, such as to ease daily price spikes, reduce emissions when the sun or wind isn’t available, or relieve congestion on a local line. “It’s nearly constant. I think soon we’ll be able to say it’s like every hour,” Guernsey told me.
So far this year, Voltus has reduced electricity demand in PJM by more than 200 gigawatt-hours. Now the company plans to lean more heavily on batteries, particularly at commercial and industrial sites, to accelerate its growth. Guernsey told me that with battery costs falling, electricity prices rising, and fixed payments to participants through 2040, the math now works to deploy batteries at scale, without exposure to unpredictable wholesale electricity prices.
She’s betting that other hyperscalers will see the value in large-scale battery deployments too. Most of the buzz today has revolved around hyperscalers bringing their own generation online — both to secure power faster and head off community opposition by paying their own way. Thus far, Google is the only hyperscaler committed to bringing its own distributed capacity through a VPP. But getting the big players to embrace these new “bring your own capacity” contracts, which Voltus launched last September, is central to its growth strategy.
Guernsey has likened these novel capacity contracts to the corporate renewable power purchase agreements that Google also helped pioneer in the early 2010s. Now she sees a similar opportunity for VPPs to move from a promising concept to a mainstream procurement tool.
“There’s been this notion that we’re coming up on an inflection point for a very long time,” she said of the VPP market. “And I want to be able to say we came up on the inflection point, we went past it, and now we are scaling. And this is an awesome proof point.”
The Federal Reserve raised the federal funds rate by a quarter point, the central bank announced Wednesday afternoon, its first rate change since Chairman Kevin Warsh took his seat in May and its first rate hike in over three years.
The federal funds rate will now sit between 3.75% and 4%. According to projections by regional Federal Reserve presidents and members of the Board of Governors, the central bank expects to hike rates one more time this year.
In its now characteristically brief statements, the Federal Open Market Committee said that the hike “will support a timelier return to the Committee's 2 percent goal” for inflation. Inflation is currently running at 3.4% and has been above the Fed’s 2% target since 2021.
The FOMC’s (brief) statement explaining the hike pointed to “resilient” domestic spending and “robust” capital investment. It characterized the economy as “expanding at a solid pace,” albeit with “elevated” uncertainty due to “geopolitical developments.”
This combination of factors — high oil prices due to the partial shutdown of the Strait of Hormuz and high investment in data centers — have helped push up yields on Treasury bonds, which helped maneuver the Federal Reserve into its rate hike. These rising Treasury yields have made raising capital more difficult for sectors besides artificial intelligence, very much including the capital-intensive renewable and clean energy industries.
Warsh attributed higher Treasury yields to “economic strength, competition for capital, and geopolitics,” in his press conference following the rate announcement. The yield on the 10-year treasury bond, often used as a benchmark for the cost of money throughout the economy, rose to over 5% on the news, the highest level since 2007.
The August Electricity Price Hub data is in.
It’s another hot and expensive summer.
Across the country, average household electricity bills are up 2.7% in the first eight months of the year, according to the latest update to Heatmap and MIT’s Electricity Price Hub, tacking on $4 per month to the typical bill. This level of rise is consistent with the pace set in 2024 and 2025, but faster than 2021 and 2023.
As we’ve discussed before, some of the fastest growth in prices comes either in the Atlantic Seaboard — with Washington, D.C., Virginia, and New Jersey all having year over year growth rates of at least 7.5% — thanks largely to increased demand and capacity payments in the PJM Interconnection marketplace. Another standout so far this year is Hawaii, which is uniquely dependent on imported oil to power its grid and has seen its 12-month trailing average prices rise by over 8% so far this year.
California, which is well known for seeing especially sharp price increases in recent years largely due to wildfire-related costs, has seen somewhat restrained bill growth so far this year across the state, with the 12-month-rolling average bill rising just 3% in the past 12 months and prices going up 4%. (That price level is still quite high, however, at almost 32 cents per kilowatt-hour, compared to a national average of around 19.)
Rates charged by Southern California Edison, one of the state’s big three investor-owned utilities, are up almost 15% in the past year, averaged across its baseline regions. The MIT researchers attribute this increase to two major factors: one, a decrease in the California Climate Credit, which is paid out to electricity customers from the state’s emissions cap-and-invest program. This year, the credit for Southern California Edison ratepayers is $72, applied to bills in July and August in tranches of $36. Last year, by contrast, Southern California Edison handed out $112 in two tranches, April and October.
The second factor in Southern California Edison’s inflated bills is an increase in the fixed charge portion of the bills ratepayers receive. Following changes in California state law designed to distribute the cost of the grid more equitably, SCE revamped its rate structure at the end of last year to include a “Base Services Charge” of $24 per month for customers not enrolled in any special rate program. At the same time, SCE instituted a roughly 10% decrease in its per-kilowatt-hour electricity rate in order to protect lower-income ratepayers (who would pay a fixed charge substantially lower than the baseline $24). PG&E moved to a similar system earlier this year.
When it introduced the new rates in November of last year, SCE said that “medium energy users” would likely see little change in their bills. Price Hub data suggests, however, that the typical household has seen a bill increase from the new service charge of 13%, even before accounting for the smaller climate credit.