You’re out of free articles.
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
To manage the clean energy transition, it may have to get into the leveraged buyout game.

The United States produces more natural gas and crude oil than any other country ― it isn’t even a contest. But these “molecules of U.S. freedom” aren’t free: They’re extracted and transported through a network of rigs, drills, pumps, and pipes that are, increasingly, controlled and operated by myriad private equity companies. As a society, we have a strong interest in winding down these climate-polluting assets in a swift yet orderly fashion. But as businesses, their private equity owners don’t.
Over the past decade, pressure from shareholders and activists has succeeded in pushing many fossil fuel majors to consider how best to reduce their emissions. (Although that, too, has come at a cost.) But rather than winding down or cleaning up their most polluting and least profitable assets, many have instead simply divested. Coal companies in West Virginia have sold off their mines to undercapitalized vulture firms, which rely on continued coal sales to (in theory) pay for expensive environmental remediation costs. The same is happening in the oil and gas industry, where private equity firms have rolled up many of the drilling sites and pipelines, the capillaries and veins of the country’s energy infrastructure.
Shielded from the scrutiny of public markets, private equity funds have thus become some of the country’s top methane emitters by asset ownership in the natural gas sector. These opaque owners, capitalizing on other companies’ disinterest in holding high-emitting assets, are betting that fossil fuel infrastructure will keep paying out for quite some time; recent massive increases in expected energy demand have only juiced this trend toward industry consolidation.
Private equity firms and private debt funds, with their short-term profit horizons, concealed balance sheets, and seeming imperviousness to tighter financial regulation and shareholder activism, work well with fossil fuel assets, particularly those sold at fire-sale prices by publicly traded fossil fuel majors. Despite those assets’ long-term market value instability, their near-term cash flow prospects are what matter.
But what’s been good for fossil fuel majors’ balance sheets has been bad for the planet. Many of these buyout firms — well-capitalized private equity funds and scrappy vulture funds, alike — are not budgeting anywhere near enough for environmental remediation. One company, Diversified Energy Co, has been purchasing the rights to operate almost-depleted natural gas wellheads at scale, extending many of their lifespans by decades; far too few wellheads are closed each year to stem the methane spewing unimpeded into the atmosphere.
Rather than accept a situation where utilities and fossil fuel majors toss their liabilities to unaccountable vulture funds, sustainability-conscious investors and shareholder groups have begun screening transactions for responsible asset phaseout plans. But the lack of a binding set of transition standards has revealed a huge coordination problem: What counts as a responsible phaseout, particularly when private asset owners get to decide? The federal government has put down guidelines, but not its foot. A disorganized drawdown of assets under a patchy regulatory framework, without a doubt, leaves vulnerable communities on the hook for the financial, environmental, and health damages.
Progressive analysts have long argued that nationalizing fossil fuel assets and folding them into a state holding company is the best solution to sidestep this particular problem. The federal government is well staffed with energy and electricity experts who, operating under a public mandate to preserve grid reliability, can phase out fossil fuel assets on a unified, coherent timeline responsive to community needs while continuing to operate those assets as the “peaker” or “reserve” capacity required to ensure grid stability. A series of climate shocks has even convinced conservative leaders in Texas of the importance of public power for grid resilience, achieved through state ownership of “peaker” gas plants. This course of action is far worse than investments in, say, battery capacity ― California, for instance, is now reaping the benefits of massive battery deployment, which reduces the state’s need for gas ― but the logic behind building public reserve capacity is sound.
What advocates of a state holding company-type model do not often discuss is how exactly a government goes about acquiring all these soon-to-be-stranded fossil fuel assets. As just one example, a recent proposal from the Roosevelt Institute suggests that a state holding company should be “free to engage in debt financing, make equity investments, and acquire assets.” Sure, proposals like these are meant to buttress the case for why nationalization is a far better way to achieve a managed phaseout than surrendering that process to yield-seeking investors, not to detail the financial mechanics of a buyout. But still: this is vague!
Actually thinking through the specifics suggests that, interestingly enough, a comprehensive state-led buyout program could work a lot like an existing private equity transaction, for two key reasons.
Before we get there, we should separate private equity’s deserved reputation as an opaque asset owner from the way the industry works. Private equity’s calling card, the “leveraged buyout,” is little more than the act of raising debt to 1) purchase equity in and, therefore, ownership over an asset, and 2) refinance the asset’s liabilities. To do so, private equity funds work with banks or, more commonly these days, private debt or private credit funds, to raise debt that is generally backed by the combined assets of the purchaser firm and purchased asset.
But leveraged buyouts themselves are technically something that any financial institution could do. Take the federal government, the country’s most liquid debt issuer, whose debt anchors the global economy and backstops private financial institutions. It could raise debt (leverage) to finance a buyout of fossil fuel assets at interest rates far lower than private investors could. And because private credit funds, like other institutional investors, already buy loads of government bonds to match their liabilities and hedge their risks, this kind of nationwide leveraged buyout ― which would require substantial new debt issuance ― could actually help stabilize the financial system against potential shocks from within notoriously inscrutable private markets. The government can do exactly what private equity does, only a lot better, and with wider benefits.
The government has already planted the seeds of a leveraged buyout program across the country’s coal ash heaps. The Loan Programs Office, thanks to the Bipartisan Infrastructure Law and the Inflation Reduction Act, now offers far-below-market-rate loan guarantees to developers, including state governments and utility companies, seeking to repurpose fossil fuel assets through its Energy Infrastructure Reinvestment program. This program’s authority allows borrowers to use their financing for “refinancing outstanding indebtedness directly associated with eligible Energy Infrastructure.” All policymakers have to do now is scrap the program’s 2026 end date and, ideally, endow a federal institution with the power to borrow from this authority to purchase and refinance fossil fuel assets, rather than leave that task solely in the hands of state governments and utilities, with their varying capacities for and interest in coordinating a coherent phaseout plan. And now that interest rates are poised to fall, this refinancing becomes much cheaper.
That’s reason number one. Reason number two has to do with private equity funds’ ability to shield the assets in their portfolio from valuation volatility on publicly traded stock markets. Private equity funds need not publicize how much their portfolios are worth, except at infrequent intervals and when they sell assets. But thanks to private equity’s reputation as a high-return investment, fund investors pay a premium for the illiquidity of not always knowing the value of their assets. Purchase assets, juice returns, sell, and repeat ― this is the conventional private equity playbook.
But macroeconomic conditions today are such that private equity companies are now struggling to sell their portfolios. High interest rates have made leveraged buyouts of new assets and refinancing debts on unsold assets much more costly, and have tempered rapid asset value growth. As this once-frenetic industry slows down, funds are anxious to get assets off their books ― hence the recent wave of consolidation.
This is an opportune moment for the Feds to step in. It’s not just that the government’s capacity for undertaking leveraged buyouts is the greatest; more importantly, it never needs to sell. The valuation volatility that first prompts fossil fuel majors to divest from dying, dangerous assets yet incentivizes private equity funds to pump as much as they can out of them to resell them later at a profit is simply not something the federal government needs to worry about. A state holding company can siphon distressed assets off public markets and shut down the “merry-go-round” of asset sales and resales.
Objections to government intervention here are likely premised on the fact that, well, it’s the government. But the government would still be purchasing assets from private owners on financial markets, just like any market actor would. Today’s uncoordinated constellation of private fossil fuel firms and funds, on the other hand, cannot manage a coordinated phaseout, especially not under binding profitability constraints ― which the federal government does not share.
Local communities can’t finance phaseouts or cleanups themselves, and leaving hundreds of billions of dollars worth of stranded assets in the hands of under-regulated private firms will only accelerate climate catastrophe. The government must use the financial techniques that private equity funds have already pioneered to bring them to heel, in service of public goals.

This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
BAAJA would likely help speed up the U.S. transmission buildout, but there’s a chance we’re undercounting the benefits.
This is Heatmap Daily, a weekday digest written by our executive editor. Subscribe here.
As you may have seen, my colleague Emily Pontecorvo and I got the first look at the Rhodium Group’s analysis of what the bipartisan permitting bill will do to emissions.
You can read our story at Heatmap. The upshot is that the bill’s most significant provisions are likely neutral for climate change in a worst-case scenario — and could, in more optimistic scenarios, help reduce emissions. (Those scenarios aren’t about how the bill will be interpreted, to be clear, but about what might happen in the broader energy economy — with economic growth, for instance, or oil prices — that will feed back into the emissions math.)
I won’t give away much more about our story, but there is one irony I want to note about the Rhodium study and the broader morass of American electricity policy. One of the Rhodium study’s big findings is that BAAJA will help expand the transmission system. Power lines are essential for decarbonization because they move electricity from the country’s sunniest and windiest places to its cities, towns, and suburbs.
BAAJA will help transmission both because the law affirmatively expands the power grid and because the bill’s changes to environmental review law could help power lines. Today, for instance, it takes twice as long on average to conduct a federal environmental impact study for transmission lines as it does for pipelines, according to Rhodium data. All in all, the Rhodium analysis estimates BAAJA could increase the amount of new transmission capacity added per year by 167% to 262% nationwide, compared to the average rate over the past decade.
Which is very interesting. But it’s worth noting that the Rhodium analysis may — emphasis on may — undercount the bill’s transmission benefits. This is because the Rhodium authors did not have time to conduct a full network study of the U.S. transmission system, which would take into effect the grid’s physical footprint, power flows, and existing bottlenecks. Instead, they looked at power supply and demand within the context of the broader U.S. energy system.
That’s a reasonable decision; indeed, it was probably the only decision they could make. Because of how energy system models work, a more fulsome analysis might have taken weeks to complete, not to mention a very large amount of money and computational power. When the National Renewable Energy Lab studied how quickly Los Angeles could switch to 100% renewable energy earlier this decade, for instance, it ran such a study, modeling every transmission line and substation in LA. Its supercomputer wound up churning through more than 100 million simulations; the research effort took three years. If the Rhodium analysts had done even a fraction as much work to examine what BAAJA would mean for the country’s power grid, then they would have of course finished their analysis well after the window to vote on BAAJA would have closed.
One of the ironies here is that while the LA 100 study was particularly exhaustive, we actually require clean energy projects to conduct similar studies all the time. Right now, one of the primary reasons it takes so long to hook up a new power plant to the grid is that it has to undergo an interconnection study in many parts of the country. In those regions, a new solar farm or battery project can’t connect to the grid until operators study its effect on grid congestion everywhere else.
As it happens, BAAJA aims to fix this process, allowing power plants to join the grid in batches.
I want to note the irony that a process we mandate for the power sector is actually too slow to deliver speedy policy analysis to legislators. If Rhodium had tried to study BAAJA the way we make power plants study the grid, then it never would have delivered its verdict in time. If you think Congress is slow, in other words, you should meet the electricity sector.
Current conditions: The Pineapple Express, an atmospheric river originating in the Pacific near Hawaii, is arriving in the Southwest laden with heavy rain that’s set to flood the region • Indonesia has the worst air quality in the world as forest fires rage along Sumatra’s southern coast • A cross-country storm will soak much of the United States on Tuesday’s Election Day.
The Senate’s grand compromise to simplify federal permitting on energy projects would likely drop emissions slightly as the benefits to accelerating deployments of clean energy infrastructure outweigh the boost the legislation could give to fossil fuels. Even under the worst-case scenario, emissions remain on the same trajectory as today. That’s according to a hotly anticipated new analysis by the Rhodium Group, the consultancy whose U.S. emissions estimates are among the most widely cited in American politics. The report, shared first with my colleague Emily Pontecorvo, found that provisions in the Bipartisan American Affordability and Jobs Act largely counteract each other on climate. The bill makes building transmission lines much easier, a key step to patching more renewables onto the grid. But it also makes new gas pipelines simpler to permit, clearing the way for a buildout of the infrastructure for the fossil fuel already dominating U.S. electricity and heating systems. Still, under the best-case scenario, the legislation could cut U.S. economy-wide emissions by 5% below where they would otherwise go in 2040. The bill could also slash energy bills by $78 per year and support construction of more than 200 gigawatts of clean energy capacity, as compared to a world where it didn’t pass. The Rhodium report is at least the second analysis yet to find that the bill could modestly lower emissions. The first, as I reported last week, came from the think tank Resources for the Future, which saw a slight drop in power-sector emissions relative to a world without BAAJA.
If overhauling national permitting rules to make building green energy infrastructure easier doesn’t work to lower emissions, traditional negotiations in favor of regulations that can deliver cuts looks no more promising. Two weeks of United Nations-led talks in Armenia ended Saturday without a settled approach to meeting 2030 deadlines for preserving more nature. “We don’t need to spend more to close the biodiversity funding gap, we need to spend better,” Marina Von Weissenberg, a Finnish senior ministerial advisor, said in a statement. “Governments have a real opportunity here to reshape public spending with future generations in mind, but they can’t do it alone. International coordination is key to giving governments the confidence to lead change.”
Last week, my colleague Katie Brigham published a detailed feature highlighting China’s tightening grip over the global supply chain for electrolyzers, the technology that zaps water with electricity to separate the molecule’s hydrogen from its oxygen and harvest the former as fuel. Keen readers of this newsletter recognize the story. Even before the Iran War, China had beefed up its public support for green hydrogen and related technologies. After the conflict constricted the flow of oil through the Strait of Hormuz, the People’s Republic redoubled its efforts. Quite literally. New data from the National Energy Administration shows that investments into the hydrogen industry doubled in the first nine months of this year, according to Hydrogen Insight.
Fermi America went public in a gangbusters initial public offering last year as the company, with a board of directors including former Texas governor and U.S. Secretary of Energy Rick Perry, pledged to build the world’s largest data center and power the facility with gas and four large-scale Westinghouse AP1000 nuclear reactors. In April, the chief executive and chief financial officer quit. The board room drama continued into the next month. The company’s stock recovered somewhat over the summer as investors bet on a turnaround pegged to a series of deals with companies looking to lease space on its future servers. But fresh chaos enveloped the startup Friday when The Texas Tribune reported that Perry had failed to earn enough support from the board of directors to win reelection to his seat.
In a statement posted to X on Friday evening, Fermi said that neither Perry nor investor Jeffrey Stein had been removed from the company’s board. “In fact, both Governor Perry and Jeffrey Stein received a majority of the votes cast by shareholders,” the statement read. “Let’s be clear: Governor Perry and Mr. Stein remain members of Fermi’s Board of Directors and will continue serving until their successors are duly elected. Both remain eligible for reelection.”
Sign up to receive Heatmap AM in your inbox every morning:

If you thought the fine particulate matter from last year’s catastrophic Los Angeles firestorm was bad, you weren’t thinking imaginatively enough about just how dangerous all that airborne material could be. A new study published in the journal Science Advances suggests that upward of 7 million people were exposed to high levels of airborne lead and other toxic metals released when homes and vehicles caught flame. The January 2025 Eaton inferno that destroyed more than 9,400 buildings and killed 19 people spewed 80 times the normal concentration of lead found in the atmosphere through a plume that settled over 70% of the Los Angeles metropolitan area. “I can envision that in the future we have these evacuation zones for smoke exposure as well,” Haroula Baliaka, the study’s lead author, who was a PhD candidate at Caltech last year, told Bloomberg. “Unfortunately, this is not a one-time event. It’s a new reality and we need to adapt to it and we need to do it sooner rather than later.”
The findings come a week after a study published in JAMA Pediatrics showed a link between wildfire smoke exposure during pregnancy and autism diagnoses in children. The research from Rutgers University examined 893,212 mother-child pairs enrolled in Medicaid, with children born between 2007 and 2014. Each increase of 0.75 micrograms per cubic meter in average concentrations of wildfire-related air pollution during pregnancy was associated with a 30% higher risk of a subsequent autism diagnosis. Exposure in the second and third trimesters had the highest risk. “Wildfire smoke can travel far beyond the communities where fires are burning, and exposure may occur even when smoke is not visible,” Stefania Papatheodorou, an epidemiologist at the Rutgers School of Public Health and lead author of the study, said in a press release. “Our findings highlight the importance of awareness of wildfire events and their potential effects on air quality during pregnancy.”
The United Kingdom is building out more than 10 gigawatts of offshore wind as London looks to shore up its electricity supplies amid the global energy shock. But Chancellor of the Exchequer John Healey said he would veto any offshore wind projects that don’t lower bills. While clean power is “how we break the grip of international gas prices on our bills,” he said the infrastructure “has to come at the right pace, in the right places, with the grid to carry it.” The statement fueled what The Guardian called “concerns that the government is moving away from the pro-renewables agenda.”
Meanwhile, the U.S. midterms aren’t the only election this week. In Sunday’s runoff election, Bulgaria’s pro-Russian acting President Iliana Iotova appeared to eke out a victory over the former prime minister Andrei Gyurov, a pro-Western banker. Her win unites the government with her close ally, Prime Minister Rumen Radev, ensuring stronger support for the leader’s two signature energy policies. One, a plan to build a pair of Westinghouse AP1000s at the Kozloduy nuclear plant, is scheduled to advance to the next planning stage next year. The other, the easing of sanctions on Russian uranium to ensure a supply of fuel for the plant’s existing reactors, looks likely to continue under Iotova’s friendly diplomacy with the Kremlin.
William Nordhaus, the pioneering Yale University economist who won the Nobel Prize in 2018 for integrating climate change into macroeconomic analysis, has died at 85 following a battle with an aggressive form of brain cancer. His nephew, Ted Nordhaus of the Breakthrough Institute, referred to his father, Robert Nordhaus, as “the original environmental lawyer and Bill as the original environmental economist,” he wrote in a blog post after his uncle’s passing. “It is safe to say that the Nordhaus brothers were doing environmental law and economics, respectively, long before either label existed. Not bad for two kids who grew up in the intellectual hotbed of Albuquerque, New Mexico, population 40,000, during and after the second world war.” Their legacies are something of the Nordhaus family brand: Pragmatism. May his memory be a blessing.
Even in the worst-case scenario, BAAJA wouldn’t increase emissions, an analysis by the Rhodium Group concludes.
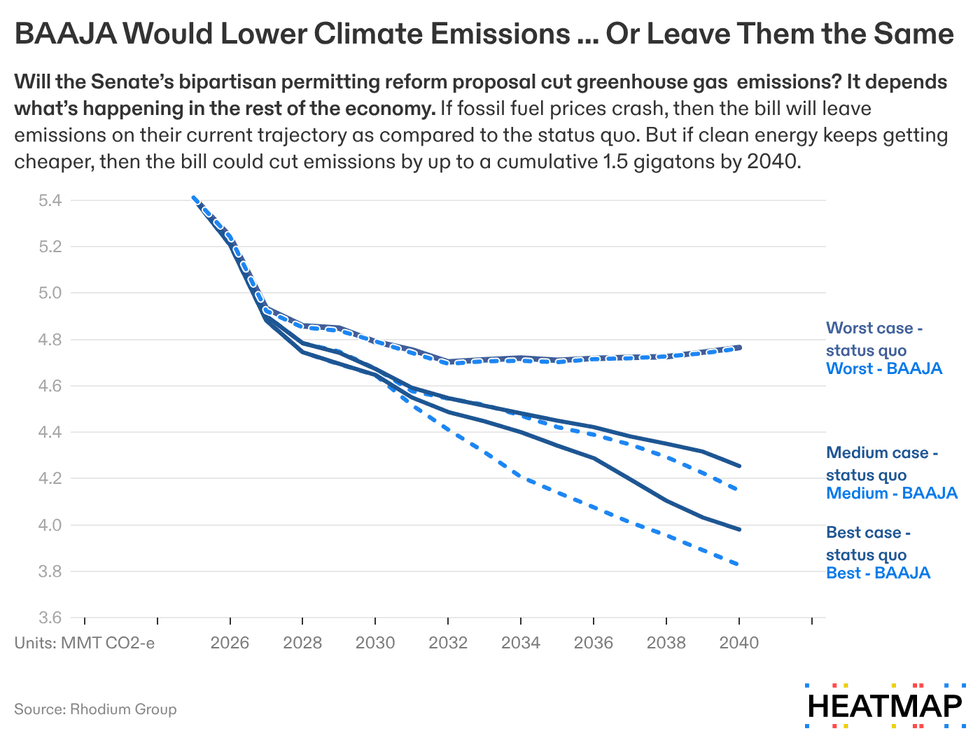
The bipartisan permitting reform bill is likely to slightly cut greenhouse gas emissions and lower electricity bills by 2040 — or at worst leave emissions on the same trajectory that they are on today — as compared to the status quo, according to a new analysis of many of its provisions by the Rhodium Group, an independent research firm.
The analysis examines the policies in the Bipartisan American Affordability and Jobs Act, or BAAJA, that would have the most-clear cut effects on climate pollution and the energy system. It is the most comprehensive account of the bill’s effects on emissions so far, although it does not examine all of its provisions.
The bill is hard to analyze because — unlike recent partisan energy bills, such as the Inflation Reduction Act or President Trump’s tax and spending bill — its effects on the climate are more ambiguous and often seem to counteract each other. BAAJA will make it easier to build not only long-distance transmission lines, which are essential for clean energy, but also natural gas pipelines, which can expand fossil fuel production.
Yet the climate benefits likely outweigh or balance out the harms, at least among the studied policies, the report finds. In the best case scenario, the bill could cut U.S. economy-wide emissions by 4%, reduce energy bills by $78 per year, and drive more than 200 gigawatts of new clean energy capacity by 2040, compared to status quo policy. In a worst case scenario, greenhouse gas emissions would remain unchanged on their current trajectory.
The results should be viewed as more directionally instructive than a precise accounting of the legislation, Ben King, an energy and climate director at Rhodium, told me.
“We don’t see emissions increasing because of the bill,” King said. “This bill should drive some emission reductions, it should drive some more clean energy on the grid, and it should drive electricity bills down. And given the complexity of the bill, that’s what we can say at this point.”
The analysis does not look at the bill’s permitting certainty provisions, which Democrats initially sought to stop President Trump’s war on wind but have become one of its thorniest sections. Rhodium’s modeling is also a crude tool for assessing transmission policy, since the model can look only at economic inputs such as supply and demand, and not the physical reality of the U.S. grid, such as where transmission lines run or where the bottlenecks are.
It is the second analysis to find that the bill could modestly lower carbon pollution. A more limited report focusing only on the power grid, published last week by the think tank Resources for the Future, found the legislation could cut electricity emissions by 6% while reducing electricity system costs by $350 billion through 2050.
The effects of the bill may sound small, but BAAJA is not a climate bill. It’s not engineered to reduce reliance on fossil fuels or boost clean energy technologies. Its overarching purpose is to address various federal bottlenecks that bog down America’s ability to build stuff, whether that’s a pipeline or a highway or a power line or a solar farm. So it’s not entirely surprising that it’s not expected to have a dramatic effect on emissions.
The reason it’s a priority for Senate climate champions is that many of its provisions are important precursors to decarbonizing the U.S. economy more quickly. By enabling faster expansion of the power grid, the bill would put the country in a much better position to transition to clean energy. After Joe Biden’s big climate bill, the Inflation Reduction Act, passed in 2022, Princeton University researchers found that the country’s slow buildout of transmission lines would be a major obstacle to gleaning the law’s benefits. Unless the country more than doubled the rate of transmission expansion, they wrote, more than 80% of the IRA’s emission reduction potential by 2030 would be lost.
BAAJA could nearly triple the build rate of high-voltage transmission, the Rhodium Group found, from an average of about 0.7 terawatt-miles added per year over the past decade to an average annual pace of 1.9 to 2.6 terawatt-miles through 2040. Because Republicans and President Trump have repealed so many of the IRA’s provisions, this won’t drive as much clean energy as the Princeton researchers expected, but Rhodium estimates that by 2040, BAAJA would help between 17 and 249 gigawatts of clean resources get built compared to a world without it.
The growing grid is the main reason why the bill cuts energy costs, because it enables more lower-cost resources to connect to the grid. The bill’s requirement that data centers pay the full cost of connecting to the grid also puts downward pressure on electricity rates.
“If your goal is to do climate policy in the future, this is an important down payment to making progress there,” King said.
The authors studied the bill’s provisions under a range of economic assumptions, including a “best case” scenario in which clean energy gets cheaper and easily outcompetes natural gas, and a “worst case” scenario where natural gas prices collapse and the inexpensive fuel keeps dominating the U.S. energy system.

The authors limited their analysis to the bill’s provisions that speed up transmission line and natural gas pipeline permitting. They assumed that when you make it easier to approve transmission lines, the lines get cheaper to build and get built more quickly. The same goes for gas pipelines. Then they looked at how the energy system would respond. Would we build more power plants? Would there be more natural gas production? Where will that gas go?
The caveats, aside from omitting the bill’s “project certainty” provisions, are that they did not account for policies that support geothermal energy, virtual power plants, advanced transmission technologies, or the ways in which the bill would reduce congestion on the grid — all of which could result in fewer emissions. At the same time, the modeling assumes that all of the data centers that get built between now and 2040 connect to the grid, even though today, many data centers are planning to run on inefficient off-grid natural gas plants. That means this modeling likely underestimates emissions from data centers. (Although the authors did a separate exercise that went deeper into data centers, which I’ll explain shortly.)
The report also limited its analysis to the United States. While the modeling found that liquified natural gas exports would increase by 8% to 15% under BAAJA, the authors did not account for how those exports could affect the energy mix or emissions in the rest of the world.
They found that the bill’s changes to the Clean Water Act and the National Environmental Policy Act would enable more gas pipeline development, which, in isolation, would increase emissions relative to a world without BAAJA. More pipelines means more production of oil and natural gas, which means higher methane and CO2 emissions throughout the fossil supply chain. Under a worst case scenario, they estimate a 4% increase in the amount of new gas capacity, although gas-fired generation as a whole increases by less than 1% in 2040. Even then, emissions would simply be flat compared to current expectations.
“On net, the emissions increases that we see there are outweighed by the emissions benefits that come from the transmission provisions of the bill,” King said.
The report also studied how BAAJA might affect data center emissions. Its “base case” scenario — which includes all the analysis I’ve shared with you so far — assumes data centers will make up about 17% of electricity demand by 2040. That figure already supposes huge growth in data center energy consumption, because data centers only use about 5% of U.S. electricity today.
But what if data center demand grows even faster than that? The authors modeled two additional scenarios to see what would happen if data center electricity demand instead accounted for more than a quarter of U.S. electricity demand in 2040.
While BAAJA would make it easier for data centers to connect to the grid, it also includes ratepayer protection provisions that would make it more expensive to do so — roughly 10% more for a 1 gigawatt data center, Rhodium estimates. Determining whether that will drive developers on-grid or off-grid was beyond the scope of the analysis, so the modelers looked at the two extremes — a world where all additional data center demand hooks up to the grid and one where none of it does.
For the on-grid scenario, whether or not that additional demand is met with mostly gas plants or cleaner sources largely depends on the price of fossil versus clean generation. But even if most of the demand was met by natural gas plants on the grid, emissions would still be 30% lower than if it was met by natural gas plants off the grid, Rhodium found.
Editor’s note: This article originally misstated the scope and timing of electricity systems savings in the Resources for the Future study. It has been corrected in this version.