You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:

Decarbonizing the global economy requires replacing stuff that emits carbon dioxide with stuff that doesn’t. At its heart, this challenge is financial: All these high-emitting assets ― coal plants, gas stoves, airplanes ― were at some point financed into existence by investors seeking returns. Climate policymakers’ greatest challenge is not just figuring out how to phase out existing, dangerous capital investments in fossil fuels, but also how to finance into existence new, climate-stabilizing clean assets.
This is all much easier said than done. Central banks’ high interest rates are strangling clean energy and adaptation infrastructure investments in the United States and abroad. Recent struggles to develop offshore wind and small modular nuclear reactors in the United States exemplify how deeply hesitant private developers are to commit to long-term capital expenditures. Investors view these projects as too risky, their expected profits too low to meet their minimum return thresholds. Absent policies to stabilize supply chains and other factors affecting the financing environment for clean energy, the United States ― to say nothing about the rest of the world ― won’t meet its climate goals.
The Inflation Reduction Act is, to its credit, a paradigm-shifting attempt to finance better, cleaner stuff. One of the most potentially transformative initiatives in the IRA is, in fact, financial: the Greenhouse Gas Reduction Fund offers $27 billion in startup capital to state green banks, community development financial institutions, and nonprofits to lend to decarbonization projects primarily in vulnerable communities.
By any standard, the GGRF is an incredible infusion of cash into nascent sectors that might otherwise be neglected by mainstream investors, including community-scale renewable energy and building weatherization. Most of that cash was awarded in early April, including $14 billion divided among three separate clean energy financing coalitions made up of green banks, impact investors, and CDFIs; and $6 billion divided among various technical assistance providers for project development in low-income areas. GGRF funding recipients can use their awards to finance all kinds of community improvements ― not just through grants, but also through debt and equity. In the process, they will make a market for investments in local climate mitigation and resilience, particularly in vulnerable communities.
The GGRF is about more than simply using this seed funding to make private projects profitable. The truth is, there aren’t that many private investors rushing to structure local decarbonization projects ― not even because they don’t want to enter these market segments, but because they’re really just too busy to try anything unconventional. Some markets, like those for rooftop solar assets, are fairly standardized and liquid, insofar as investors can tranche and trade rooftop solar loans like government bonds or mortgages.
But the nascent markets for many other kinds of mitigation and resilience investments like home retrofits are illiquid. Making them liquid — and getting investors interested — requires GGRF awardees to underwrite, structure, and sequence project development themselves. They must set lending guidelines, standardize financial products, and create architectures for risk management where none exist.
If GGRF recipients build up significant financial and legal capacities to finance community decarbonization, not to mention the technical and regulatory expertise needed to coordinate state and federal funding sources in the process, then they will position themselves to help alleviate significant constraints on the flow of financing toward local decarbonization projects. This is how the IRA promises state and local governments the chance to provide unprecedented liquidity to green investments.
Cities and states currently get the liquidity they need to fund most of our public infrastructure and services through the American municipal bond market. Why not use this market to finance decarbonization, too?
It’s a good idea — except that municipal bond markets are dysfunctional. Cities and states rely heavily on private banks to structure their municipal bonds and sell them to private investors, and on credit rating agencies to certify them; these dependencies have historically forced local governments to tailor their bond issuances to the interests of a few private buyers, which are skewed against spending on longer-term priorities with lower expected returns.
Borrowing big is more often punished than rewarded, especially where governments already have smaller tax bases and less borrowing capacity. In 2018, the rating agency Moody’s downgraded Jackson, Mississippi on account of its “financially stressed” water system and its residents’ low average incomes, raising the city’s future cost of borrowing on bond markets. Last year, its water system spiraled into crisis on account of severe underinvestment, leading to a foregone conclusion: At a time when Jackson, a predominantly black city, needed more low-cost, long-term investment to fix its infrastructure, its government was structurally unable to raise enough of it.
Increasingly frequent climate disasters will set in motion the same process again and again across the country. Greater perceived climate risks are increasing municipal borrowing costs and insurance premiums, thereby driving investment away from vulnerable areas, preventing communities from investing in adaptation and resilience, and increasing their future vulnerability. Proactive disaster prevention policy requires breaking this financial doom loop.
It doesn’t help that municipal bonds are a volatile asset class, seeing sharp price drops and prolonged sell-offs during periods of market uncertainty and, lately, rapid interest rate hikes. Their dependence on risk-averse private buyers is a primary culprit. Indeed, private investors’ muni bond fire sales at the start of the pandemic nearly broke this market. Had it not been for the Federal Reserve’s emergency creation of the Municipal Liquidity Facility, which committed the Fed to buying muni bonds that no other investor wanted to hold, cities and states would not have been able to fund crucial social and community services, pay employees, and undertake necessary capital investments. The mere announcement of this backstop program preserved cities’ ability to raise debt during the first phase of the pandemic, but Congress forced it to wind down at the end of 2020.
That’s a shame: Absent this kind of backstop for public bond markets to stabilize local governments’ long-term borrowing costs, policymakers literally cannot secure the liquidity they need to keep their climate promises. There really is no way to flood-proof New York, storm-proof Miami, summer-proof Amtrak, or manage wildfire out West without the long-term public debt finance that would allow states and cities to spend responsibly and consistently on resilience.
This is a problem not just for long-term adaptation and resilience investments, but also for the mitigation investments the IRA is designed to facilitate. Considering that green banks, state financing authorities, and public-sector power developers will have to issue considerable amounts of debt to accelerate the deployment of renewable energy ― and especially because no comprehensive decarbonization program can neglect public housing or schools, which finance themselves via municipal bonds ― state and federal policymakers should not let their investment priorities fall victim to the whims of our illiquid, volatile public debt markets.
Where climate mitigation is concerned, there are some provisions of the IRA that demonstrate how rewiring the financial system to power decarbonization works in practice. Tax credits that pump a functionally unlimited amount of money into private and public clean energy development allow developers to take on more debt at better terms, facilitating greater investment. (Bonus tax credits for investments in disadvantaged communities should help mitigate against geographic biases, too.) And expanded lending authority at the Department of Energy makes financing higher-risk, longer-term decarbonization investments of all kinds vastly less expensive. The United States has seen over $200 billion in new decarbonization investments in the past year, suggesting that, despite the lack of finalized regulations on tax credit financing and “chaining,” a set of provisions that could allow public and nonprofit entities to engage in tax credit financing of private projects, the Biden administration’s political down payment on decarbonization is already paying off.
Not in every sector, though. Private investors are fickle, risk-averse, and face considerable restrictions on where they can put direct money. The developers they finance, particularly those behind the most ambitious decarbonization projects, are under similar pressures. As Ørsted, the world’s leading offshore wind developer, retreats from projects in the U.S. and elsewhere, its CEO has admitted that “what our investors need” is for Ørsted to “create value.” If expected returns aren’t high enough, then its projects won’t pencil out. Time is of the essence; this outcome shouldn’t be acceptable.
New York’s recently passed Build Public Renewables Act mandates that New York’s public energy authority build renewable energy itself for just this reason — its proponents doubted that relying on private developers made good business sense. But it may not have passed without the IRA’s financial firepower behind it. The IRA allows the public sector to access many of the same decarbonization incentives it gives private firms, balancing the playing field and empowering transformative public sector policymaking.
The public sector can also compete against risk-averse private lenders to finance project development — public financing authorities can lend for longer, on cheaper terms, and with a higher risk tolerance than most private lenders could. By offering cost-share agreements, low-cost construction loans, equity injections to buy out troubled projects, or even by building up critical component stockpiles, the public sector can set the pace of the transition.
To that end, the IRA empowers state and local governments and community lenders to seed ambitious decarbonization projects of all types and sizes where private investors alone might hesitate. This brings us back to the GGRF and all it could do for local decarbonization ― and to carveouts in the Department of Energy’s lending authorities which enable state green banks to pass on extremely low-interest loans to eligible project developers. So long as public and private entities take the effort to access them, these programs create considerable liquidity for ambitious mitigation programs and resilience investments.
But the GGRF does not target larger infrastructure improvements, and the IRA’s other grant programs for adaptation and resilience, however ambitious they may be on the scale of U.S. history, are also wholly inadequate. If policymakers and legislators want to make nationwide climate adaptation feasible, they will still have to fix public debt markets.
Maximizing the potential of the IRA to replace bad assets with better ones requires giving local and state governments the chance to throw money at mitigation and adaptation problems that money can actually solve. Leave the financial system as is, however, and the private investors that mediate it will steer the benefits of decarbonization and adaptation toward the communities wealthy enough to make doing so a good investment. Meanwhile, the communities experiencing climate disasters first and worst ― spread across underinvested rural and urban pockets, here and globally ― will struggle to secure the long-term financing they urgently need both to lessen their contributions to climate change and also to prepare for its inevitable effects.
The financial status quo forces a kind of trickle-down decarbonization that is wholly inadequate to the scale of the climate challenge. Responsible climate policymaking, then, requires the elimination of this liquidity constraint everywhere, to the greatest extent possible, and the creation of coordination mechanisms to ensure that what people need is what gets built. Public liquidity is, without a doubt, a public good.

Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
On Korea’s Westinghouse wishes, a lithium deal, and British heat pumps
Current conditions: New York City’s temperature is set to rise as high as 80 degrees Fahrenheit this week before plunging as the coldest weather so far this season blows into the Northeast • Temperatures in Denver have been above 80 degrees for the past 11 days straight • Nearly 200,000 households, mostly in Florida, are still without electricity after Hurricane Isaias.
In theory, news of President Donald Trump’s deal with Russia to pump millions of tons of diesel into the global market should have eased oil prices. Instead, all three major crude benchmarks spiked Monday by nearly 1.5%. Only West Texas Intermediate, the U.S. metric that has largely evaded the worst knock-on effects of conflict in the Middle East, remained below $100 per barrel. The hike came as the Houthi attacks on Saudi Arabia over the weekend weighed heavily on investors’ minds, eclipsing whatever impact the diesel deal could have had.
Speaking at an industry summit in Riyadh, from which executives from Western oil majors bowed out at the last minute following missile strikes on the airport in the Saudi capital, the head of the country’s state oil company warned that not even Saudi Arabia had the capacity to protect all the supply routes off its coasts for getting hydrocarbons from the region to the world. “No nation, even one as capable and confident as ours, can safeguard them alone,” Aramco CEO Amin Nasser said, according to Arab News.
TotalEnergies took more than $1 billion from the Trump administration to kill off its offshore wind projects. But don’t take that as a sign the French energy behemoth is abandoning American renewables. The company’s joint venture with private equity giant KKR announced a deal to add 700 megawatts of solar to its portfolio of 1.4 gigawatts. The $1.2 billion acquisition includes three utility-scale solar farms in Texas and Ohio that are expected to reach commercial operation in the first quarter of next year.

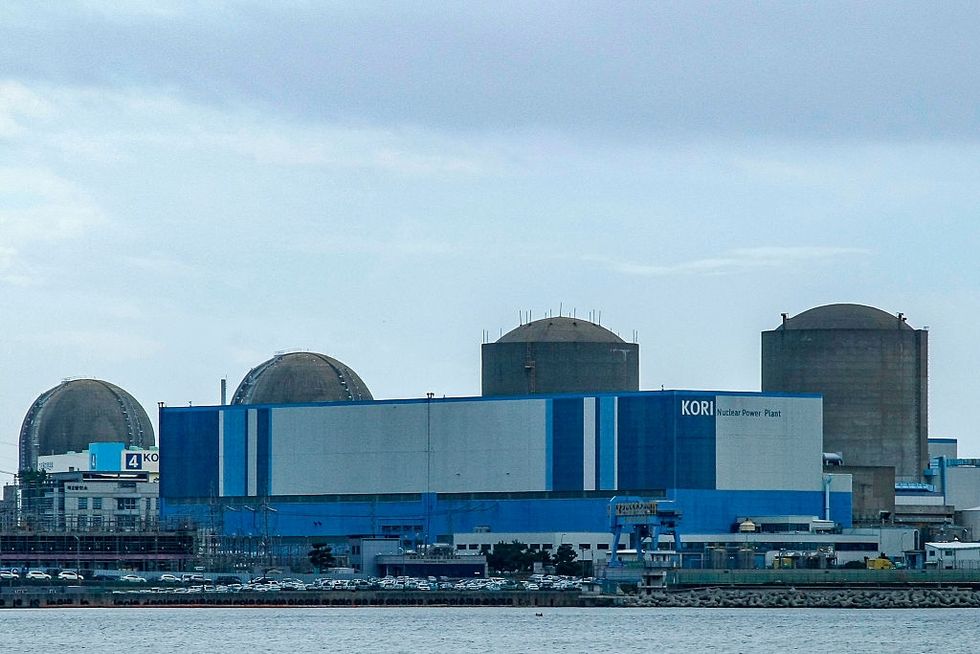
South Korea is in a bind. The Korea Electric Power Corporation, through its subsidiary Korea Hydro & Nuclear Power, represents the most competent financier and builder of nuclear reactors anywhere in the democratic world, having constructed the United Arab Emirates’ debut atomic power stations relatively on time and on budget compared to U.S., French, and British projects. But the leading Korean reactor, the APR1400, allegedly borrowed from the American nuclear champion Westinghouse’s pressurized water reactor design. A yearslong legal feud ended last year with a settlement that bars the Koreans from bidding on projects in Europe or North America. In a deal this month with the Trump administration to stave off tariffs, Seoul has agreed to help finance and construct six Westinghouse AP1000s and two of its own APR1400s in the U.S., giving the Americans a leg up on nuclear construction and the Koreans a foothold in North America.
In South Korea, where the Westinghouse settlement has widely been considered unfair, the government is signaling other plans to gain more leverage. For starters, KEPCO’s chief executive Kim Dong-cheol said the claim that the settlement requires the company to pay Westinghouse $2 billion per nuclear plant to use its technology was misunderstood. “It is true that $2 billion is the ceiling, but it does not mean we will pay all of it,” he said. But the more eyebrow-raising detail in his interview with the financial newspaper Business Korea is that KEPCO is considering a plan to acquire an equity stake of between 5% and 10% in Westinghouse. Rumors of a potential deal to buy part of Westinghouse have been circulating in the Korean press for weeks now. Anything seems to be on the table these days, but when I have asked multiple sources on the U.S. side about it, all of them shrugged off the possibility to me.
Sign up to receive Heatmap AM in your inbox every morning:
When The New York Times ran a glowing profile of the lithium startup EnergyX back in 2021, industry sources at the time mocked the coverage to me as too credulous — a sign of how unsophisticated the popular American press was at writing about critical minerals at the time. The Wall Street Journal glazed the firm’s chief executive, Teague Egan, in its own profile three years later. So it was with light surprise and amusement that I read Reuters reporter Ernest Scheyder’s latest story about the company: EnergyX just signed a $2 billion binding offtake to supply the commodities giant Trafigura with the battery metal from Chile and the U.S. It’s one of the largest deals ever tied to direct lithium extraction, the technology EnergyX is trying to commercialize, which uses less water than standard methods of mining the metal. The 10-year contract comes amid growing demand from the stationary battery storage market as the grid and data centers eat what unsteady sales of electric vehicles has left on the plate.
The British government plans to cut hundreds of millions of dollars from the national program to upgrade boilers in England and Wales, providing £9,000, or nearly $12,000, to finance the switch to heat pumps. The cuts, which the Financial Times reported Monday had drawn a backlash against the ruling Labour Party, are part of a broader bid by Prime Minister Andy Burnham to slash £2 billion in the budget to make way for more military spending. The reductions began in June under former Prime Minister Keir Starmer with a study to identify potential cuts. Starmer singled out the Department of Energy Security and Net Zero, particularly after the agency received a 16% annual increase to fund projects such as the nuclear buildout at Sizewell C, carbon capture infrastructure, and insulation to make homes more energy efficient.
The move is sure to ripple across the climate policy world. Roughly a week ago, Daniel Aldana Cohen, an assistant professor at the University of California at Berkeley, was extolling the benefits of ramping up U.S. production of heat pumps in response to soaring heating prices this winter due to the fossil fuel supply crunch. “Every year that we don’t do a wartime mobilization on heat pumps, we’re ruining people’s lives,” the early advocate of a Green New Deal wrote in a post on X. “Heat pumps will always outperform heating oil, cut costs, add summer AC. And would be fantastic for labor, small businesses, worker co-ops.”
As quickly as a spark of atmospheric electricity strikes, the Ford F-150 Lightning disappeared, with the final model of the all-electric pickup truck rolling off the assembly line last year. Now, Bloomberg reports, “it has become one of the most coveted cars in America and a glowing ember in the red-hot market for used electric vehicles.” The price of a used Lightning is 50% to 60% of the sticker price, which one expert told the newswire “is really a sweet spot.”
What 700 math problems say about the AI economy’s biggest open question
This is Heatmap Daily, an evening news digest written by our executive editor. Subscribe here.
Happy Monday and welcome back.
It’s been a big weekend: I’m fairly certain Saturday Night Live mentioned Heatmap’s data center polling in one of its Weekend Update segments over the weekend. Watch here.
There are 22 days to the midterm elections here in the United States. We’ll soon enter that pre-election wormhole where only national politics can break through. So today I wanted to look at a story that might, on its face, seem like it has nothing to do with climate or energy. And warning: It’s a little bit of a weird one.
Last week, OpenAI released what it described as the solution to more than 700 open problems in mathematics. Many of the problems, such as the Quasi-Riemann hypothesis, had gone unsolved for decades. Some of the solutions came with proofs written in the programming language Lean.
The release made a stir in part because OpenAI had reached the solutions by using an internal model — that is, a version of ChatGPT not yet open to the general public. In a statement, the Association for Human Mathematics lambasted OpenAI for using an internal model to do research, violating what it described as a precept of AI-driven math research. (I’ve since seen speculation that OpenAI may not have even meant to solve the problems, but gave them to the internal model as a test … and then got the answers.) It’s also not clear whether all of OpenAI’s 700 solutions are correct — in many cases the proofs are so intricate that mathematicians are still wrapping their heads around them.
“There are some sad stories related to their users getting scooped [and] conflicts of interest,” Levent Alpöge, a mathematician at Anthropic, posted on X. “It’s obviously the most significant moment in mathematical history.”
On Friday night, the UCLA mathematician Terence Tao gave a pre-planned lecture at Caltech about what he called “Math 2.0”; it considered the revolution the field had seemingly undergone in the previous few days. (He posted the slides to his blog over the weekend, and I’m using them to summarize his talk here.) For most of math’s history, he said, the field operated under “proof scarcity,” in which finding a solution to an open math problem and confirming it as true was “difficult and rare,” requiring “significant human expertise.”
But AI, it has turned out, is well suited to solving math problems. This is partly because math, like the large language models themselves, is entirely conceptual, so confirming a proof as true requires no recourse to the physical. But it’s also because math’s solutions are “objectively verifiable”: “There is broad consensus on what constitutes a correct and complete proof of a given problem,” and thanks to the existence of proof programming languages like Lean, they can even be checked by computer.
The end result is that math is now entering a world of “proof abundance,” he said.
That is, perhaps surprisingly, a problem for math’s practitioners, and it will mandate a new intellectual regime for the discipline. Mathematicians have often used open problems as “lighthouses,” Tao wrote, “not destinations to be reached … but useful guides to explore the mathematical landscape.” Mathematicians often learn more in the solving than in the solution, in other words. But if mathematicians can now generate shortcuts to math problems without knowing how they got there, or even how the problem works, then actual human mathematical understanding will suffer. (One way to understand this is that mathematicians are now dealing with the same problem that math teachers have faced since the invention of the pocket calculator: How do you confirm students actually understand the material? Except the world’s most elite mathematicians themselves are the students in question.)
This disconnect can pose its own AI alignment problems, Tao said, analogizing math to pharmaceuticals. Suppose an advanced AI found what appears to be a cure for cancer that can pass a stage 3 clinical trial: “After a large amount of compute, it produces a cocktail of previously unknown chemicals which it claims, when mixed and injected into a patient, will kill all their cancer cells,” he said. It even generates a programmatic proof of the cocktail’s effectiveness.
“Before injecting this cocktail into your bloodstream,” he asked, “would you find it reassuring to know that there is at least one human cancer expert who understands — even partially — the mechanism behind this cure?” If not, you can see mathematicians’ problem, confronted by a surfeit of proofs that seem to work, but nobody who can explain how or why they do.
Now, Tao’s analogy is somewhat peculiar because something like this actually does happen all the time in medicine: Doctors still don’t fully understand how many drugs work, including acetaminophen, SSRIs, and lithium. (That said, those compounds were identified by trial and error, not by a mechanical superintelligence.) But the broader situation that Tao is painting — as well as the crisis posed by OpenAI’s 700 proofs — get at a significant question with economic importance far beyond just math: Will AI solve the economy’s secular attention shortage or worsen it?
This question has greater import than it may seem — but let me qualify what I mean by “attention shortage.” Writing in 1971, the economist Herber Simon observed the sudden superabundance of information that had exploded in every economic domain. There were more facts, data, news articles, and opportunities than any individual or organization knew what to do with. He pointed out that this newfound “wealth” of information implied an insufficiency of something else: attention.
“What information consumes is rather obvious: it consumes the attention of its recipients,” he wrote in Designing Organizations for an Information-Rich World. “Hence a wealth of information creates a poverty of attention and a need to allocate that attention efficiently among the overabundance of information sources that might consume it.”
He wrote this, of course, well before the advent of internet, smartphones, sensors, or networked cameras — all of which have worsened the problem. But in the ensuing half century, the economy has learned to deal (or at least intermittently manage) this secular scarcity of attention. Much of what we now call knowledge work is devoted to filtering, siphoning, processing, and otherwise attending to the information superabundance.
AI is, in theory, supposed to help address this same set of problems. AI is commodified attention — or, at least, that is its promise. (The most important machine learning paper of the past decade, after all, is entitled “Attention Is All You Need.”) Many AI products, such as Meta’s Muse, now want you to believe that by ceding control of your email, your calendar, your restaurant reservations, and your digital life to AI, you will gain an attentional edge. The AI will do the grunt-work of attending to boring things for you, and you will feel less overwhelmed. If this vision comes true, the economy’s mismatch of information and attention will prove to be a short-lived historical blip.
But the past week of math news and Tao’s “Math 2.0” regime suggest a different scenario is more likely, at least in the immediate near term. By allowing far faster and more automated information production, AI will create a new, more vicious, and even more abstract form of information overload. Every profession and intellectual discipline will be overwhelmed with new papers, ideas, observations, proofs, or choices. Yet the human understanding required to convert this new information into useful action will become even more scarce. In such a world, AI will not solve the economy’s attention shortage, but worsen it.
I’m not sure which world would be worse for humanity, to be candid. One world suggests the eventual automation of all human effort. But in Tao’s world, many of us might still have jobs — they will just involve even more filtering, sorting, and processing of an ever-deepening pile of automated idea generation than we do today.
And what is the connection to climate and energy? One easy connection might be to the permitting process: If you think a new transit line (at the local level) or transmission line (at the state or federal level) could be overwhelmed with procedural concerns 10 years ago, wait until you see what happens when information itself can be mechanically produced. But that is only one example of a more general problem. Soon, if not already, any process of providing input to an important policy question — on energy, decarbonization, or anything else — will be overwhelmed with facially high-quality analysis. It will be left to policy officials and elected leaders to sort through it.
This past weekend’s storms caused flooding and property damage up and down the coast — and it’s going to get worse.
California has around 3,400 miles of shoreline, ranging from the wild, foggy beaches of the North Coast to the sunbather-studded sands of Orange and San Diego counties. That’s a whole lot of border to share with the Pacific Ocean, especially when the water is as hot and tempestuous a neighbor as it is right now.
Just ask the city of Long Beach, which this weekend was on the receiving end of some Super El Niño mischief. Swells from the storm briefly dubbed Hurricane Rachel “annihilated” beachfront mansions and flooded city streets, causing pieces of the local boardwalk to “shred away.” “It’s never happened like this before,” one resident of 64 years told the New York Post.
But while things might look bad in California at the moment, they can still get much worse. One disaster modeler recently estimated the state could see as much as $3 billion in flooding and mudslide-related losses alone this winter — not to mention coastal erosion, king tides, and storm swell. Governor Gavin Newsom declared a state of emergency at the end of September, while many cities, including San Diego, have declared their own local emergencies.
El Niño will likely peak in December, meaning that towns and cities across the state have just a few remaining weeks to finalize projects, whether that means improving drainage in landslide-prone environments such as Rancho Palos Verdes or distributing NOAA weather radios in areas likely to lose power, as emergency managers are in Santa Cruz. The approaching winter storms, combined with El Niño, represent “a humbling reminder of the ongoing effects of climate change and the importance of emergency preparedness,” Laath Martin, the public affairs lead for the city of Long Beach, wrote to me in an email.
El Niño is a cyclical phenomenon, occurring when temperatures in a particular stretch of the Pacific Ocean rise half-a-degree Celsius above the average of the preceding 30 years. But there are signs these natural variations are happening less predictably because of climate change, and we know for sure that a warmer atmosphere makes the baseline for its impacts worse: king tides, Kelvin waves, and storm surge piggyback on top of rising sea levels to result in more severe coastal flooding and erosion. A warmer atmosphere also holds more water, which means more rain — perhaps 200% above normal — which, in turn, results in flooding and mudslides further inland, as well.
“Based on what I am seeing now, I am officially concerned,” Daniel Swain, a climate scientist at the University of California Agriculture and Natural Resources, said last week after reviewing the latest outlook. There’s a reason this year’s El Niño is being called a Godzilla.
In general, the weather pattern causes the jet stream to shift south in the winter, bringing wetter and snowier conditions to the lower U.S. while the northern part of the country stays drier and mild. (It’s also responsible for a weaker Atlantic hurricane season, as we’ve already seen this year.) In addition to El Niño-driven Kelvin waves, warm bulges of water that raise the sea level on the coast by as much as 18 inches, the state of California — and particularly southern California — sits directly in a storm track that will deliver “atmospheric rivers” of heavy rain to a region prone to landslides and flash floods.
In many parts of the state, that rain will test the best-made plans in addition to plans deferred. In Los Angeles, the Department of Sanitation and Environment, or LASAN, has told the City Council it has concerns about the ability of the aging wastewater pipes and plants to handle heavy rainfall associated with a supercharged El Niño. In San Diego, which requires some $3.3 billion to upgrade what is in some places a century-old wastewater system, emergency managers are preparing to work with what they have by clearing debris and brush that could back up in the drains, CalMatters reports. In both cases, the time required for systemwide repairs far exceeds the time remaining before the winter’s supercharged atmospheric rivers are due to arrive. (Rezende told me inland flooding affects more businesses and residents in San Diego than coastal flooding, since the population in the city is set further back from the coastline.)
The city of Roseville, northeast of Sacramento, by contrast, is leaning on decades of flood planning to get through the season. After a series of back-to-back storms in 1986 that killed 13 people and caused $400 million in damage, the city and FEMA invested $39 million to upgrade Roseville’s infrastructure, including widening streams and adding levees and stormwater bypass channels. With more accurate floodplain modeling that has “helped keep new construction at higher elevations,” Helen Dyda, the city manager’s public information officer told me that “less than 7% of the city is within a floodplain” today. Dyda added that the city prepares for winter storms every year — it has some 160 miles of creek shoreline, after all — but that the El Niño-specific preparations are, as a result, more similar to routine maintenance: “clearing more dense vegetation and fallen trees from key creek areas.”
Long Beach is caught somewhere in the middle. After swells from Hurricanes Marie and Polo hammered the city in September, Long Beach hastily developed a seven-point plan to strengthen its peninsula in the near and long term. It will also begin a $11.4 million dredging project this fall that will place 415,000 cubic yards of sand on the beach as a buffer zone. “While this effort will achieve a much-desired result, it will not stop the ocean from pulling sand from the peninsula with every wave, especially during the significant weather systems Long Beach continues to experience,” Martin, the city’s public affairs lead, wrote to me. “Back-passing will need to continue to return sand back to the peninsula each day until more permanent, long-term man-made and environmental solutions can be identified, permitted and implemented.”
In certain cities, preparations for the peak of El Niño overlap with ongoing repairs from the last bad storm season. In Santa Cruz County, the 2016 El Niño caused an estimated $9 million in damage, while many in the community of Pajaro are still recovering from the flood damage caused by a series of severe atmospheric rivers in 2023. “We have a list of hazards that the city is vulnerable to, and we plan for all of them not individually, but all together,” Meredith Albert, Santa Cruz’s emergency management manager, told me. She added that many of the city’s preparedness activities and El Niño initiatives, like urging the community to be prepared to spend 72 hours unsupported, overlap with other disasters it works year-round to prepare for, like earthquakes, landslides, and wildfires.
“El Niño turns up the volume a little bit, but it doesn’t necessarily change our hazard landscape,” is how Albert put it to me.
Santa Cruz has not declared a local state of emergency, and Albert told me they won’t until they “run out of resources.” Other cities, like San Diego, have declared one preemptively. “In the past, you’d have to go through a longer review if you wanted to make some headway on projects, and sometimes that would take many weeks or many months of permitting,” Rezende said. “With a state of emergency, we streamline that process and get projects in the queue.”
Both Rezende and Albert told me the governor's statewide emergency declaration mostly helps state agencies position themselves for a faster response or has implications for higher-level permitting processes. (In Carlsbad, for example, which has seven miles of badly eroding beach, just one mile is controlled by the city; the other six are managed by the State Parks.) The state has also teamed up with ICEYE, a satellite imaging company, to receive information about flooding even in the dark or through rain clouds.
No state of emergency, though, can make it so a city can replace a century-old sewer system by Christmas or reengineer a beach by the time January’s storms begin to make landfall. But if a Godzilla analogy fits the onslaught of a super El Niño, it also offers a classic disaster-movie lesson on how to survive it.
Albert’s advice for how to prepare? Ask a neighbor for a cup of sugar. Take their dog for a walk. Build a relationship that could prevent a tragedy. “We know that our city will be cut off for at least a couple of days,” she told me of a hypothetical major disaster, referring back to Santa Cruz’s experience after the 1989 Loma Prieta earthquake, which cut off the city’s power, communication, and supply lines. “And we also know that we can’t build those relationships during the disaster. We’re trying to build them before.”
The city is doing a lot to prepare for the storm, she said. “But the question is also, what are all of us doing?” Albert went on. “You know better than I do, at the city level, who’s not going to receive that alert,” whether that be an elderly or unhoused neighbor or a nonnative English speaker who might not receive or understand emergency communications.
“Check in on a neighbor” is easier said than done — active engagement and connection to one’s community is trending downward in most parts of the U.S. But the people and places that bounce back from disaster and tragedy are almost uniformly the ones that look after each other. Borrowing a cup of sugar, to this introvert, sounds like a nightmare. But there’s never been a better time than a Godzilla El Niño to bake a poorly resourced cake.