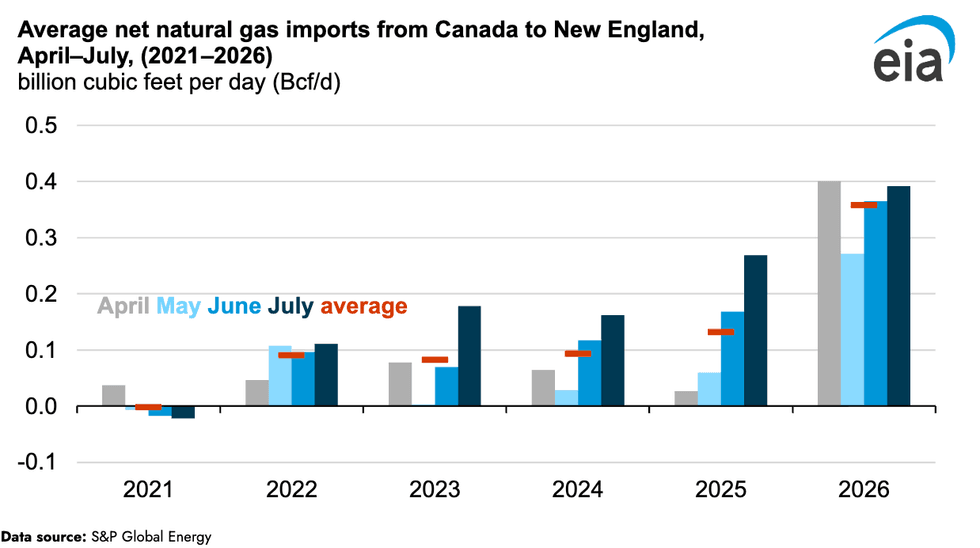You’re out of free articles.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
Fossil fuel plant retirements are slowing down, and projected load growth is to blame.

To fully decarbonize the electricity system will require more than just the rapid deployment of non-carbon-emitting generation capacity, plus the transmission necessary to get that electricity to where it needs to go. It will also require that our existing stock of electricity generation — which is largely natural gas- and coal-powered — get mostly mothballed. So far, this process has been proceeding briskly. Renewable deployment is on the way up and is projected to accelerate, and older electricity generation was sliding quickly but gracefully into retirement — until recently.
Retirements of existing generation have slowed down dramatically in the first half of this year, which is on pace to be the slowest for existing generation retirements since 2011, according to new data from the Energy Information Administration.
In the first half of the year, some 5.1 gigawatts of generating capacity have been retired, and another 2.4 gigawatts are scheduled to be retired by year’s end, for a projected total of 7.5 retired gigawatts. From 2004 to 2023, by contrast, just over 12 gigawatts of capacity were retired each year on average, with almost 15 gigawatts retired per year this decade. Since 2022, according to EIA data, over 90% of retired capacity has been coal or natural gas.
What’s behind the slowdown? “Reliability is threatened because the grid conditions are tightening,” Douglas Giuffre, executive director of gas, power and renewables analysis at S&P Global Commodity Insights, explained in an email. “This is partly due to the recent pace of coal and natural gas retirements in the U.S., which worked off some of the excess capacity in power markets. Now we are seeing tighter reserve margins, and a relatively thin pipeline of new gas-fired projects that can come online quickly.” That’s especially concerning for utilities at a time when projected electricity demand is way, way up.
The wave of retirements was a national phenomenon, often having nothing to do with state-level plans to decarbonize. Coal and gas were being retired so steadily over the past 20 years not just because plants were aging, but also because power use was essentially flat from the early 2000s through, essentially, yesterday. This meant that older plants — especially dirty coal plants — became uneconomic to run, especially as natural gas prices began to fall.
Now, we are in a completely different world. Electricity use is forecast to start growing again, thanks to a buildout of new data centers and manufacturing, plus the ongoing electrification of automobiles and home heating and cooling.
The Southeast offers an example of how these trends have played out on the ground. In December 2020, the Mississippi Public Service Commission determined that the state had “excess reserves … largely due to decreases in projected load” and ordered a 950 megawatt reduction in generating capacity by Mississippi Power by 2027. A consulting firm hired by the commission determined that Plant Daniel, a coal plant, was “relatively inefficient compared to other available resources;” a few months later, the utility said it would decommission Plant Daniel by 2027.
Then Georgia Power, the utility that covers most of the state (and, like Mississippi Power, a subsidiary of Southern Company), rushed out a new three-year plan for its future power usage less than a year after finalizing its old one. Its demand forecast through the end of the decade had jumped from 400 megawatts to 6,600 megawatts, the result of a projected boom in data center construction.
“They came in with a preselected list of ways it wanted to meet that power need,” including buying power from Plant Daniel and new gas, Bob Sherrier, a staff attorney at the Southern Environmental Law Center, told me. Georgia Power told the state’s utility commission that to respond to growing demand it would need to extend contracts with its sister utility in Mississippi — which meant not only that Daniel would remain open for at least another year — and build new new plants that could run on gas or diesel, plans for which regulators approved on Tuesday. The utility also hinted that its existing plans to euthanize, for the most part, its coal-fired generation fleet by the end of 2028 were likely to be revised.
“To meet that projected need, the utilities are reverting to what they know, which is fossil fuels,” Sherrier said.
In vertically integrated markets, where utilities own generating assets and sell power to customers, environmentalists have seen delayed retirements and the building of new fossil plants as examples of utilities slipping into their comfort zone, building and operating expensive projects instead of developing or procuring renewables to handle rising demand.
But it's not just in vertically integrated markets where fossil retirements are being delayed. In Maryland, for instance, Brandon Shores, a coal-fired power plant that was scheduled to close in 2025, is staying open because PJM Interconnection, the regional electricity market, determined that a plan to replace it with battery storage was not a “realistic option at present” nor “technically viable to resolve the reliability violations or avoid the need for an RMR agreement at this time,” PJM president Manu Asthana said in a letter to Paul Pinsky, the director of the Maryland Energy Administration. The transmission investments required to make up the difference, meanwhile, would take several years.
Along with the neighboring Wagner plant, which burns a mix of coal, oil, and natural gas, Brandon Shores will likely stay open more than three years past its planned retirement date thanks to what’s known as a “reliability must run” contract, which “would put Maryland ratepayers on the hook for over $600 million dollars in out-of-market payments,” according to a letter written by several Maryland congressional representatives to PJM.
Environmental advocates have blamed PJM for not doing enough proactive transmission planning to account for predictable and scheduled plant retirements.
The slowing retirements mean that emissions from the electricity sector, which have been falling since the mid-2000s (with occasional bumps up as the economy has recovered from downturns), are expected to plateau over the next year or so. EIA forecasts show carbon dioxide emissions from electricity as essentially flat from 2023 to 2025, with increased natural gas emissions essentially offsetting falling coal emissions.
There is a bright side to the data, however. So far this year, the U.S. has installed just over 20 gigawatts of new generation, 80% of which has been solar and battery storage, including a 600-plus megawatt projects in Nevada and Texas. If added generation comes on in the second half of this year as planned, the EIA projects we’ll have 15 gigawatts of battery storage by year’s end. Along with the large and growing solar generation in states like California, Nevada, and Texas, the U.S. is getting closer to a grid that can, at least, run without carbon emissions day or night.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
On solar manufacturing, New England gas, and Pacific Northwest geothermal
Current conditions: The Pacific just can’t catch a break this hurricane season as forecasters warn that a new tropical development called Invest 96E could form in the next two days off Baja California, right behind Hurricane Lowell • In Indonesia, the wildfires blazing through the peatlands and forests of Borneo and Sumatra are now emitting by far the most carbon dioxide of any blazes in the world • A late-summer heat wave is sending temperatures along the California coastline beyond 100 degrees Fahrenheit this week.
When Alphabet inked its first nuclear deal in 2024, the Google parent company opted to back a next-generation, fluoride salt-cooled reactor startup called Kairos Power. Six months later, the tech behemoth contracted Elementl Power, a nuclear project developer that works with all kinds of reactors, to scout locations for deploying novel atomic technologies. Last October, Google broadened its approach to focus on large-scale reactors that either already existed or were under development. The company eyed financing the construction of the abandoned Westinghouse AP1000s planned for the V.C. Summer plant in South Carolina before the project went under nearly a decade ago. Then Google and NextEra began laying the groundwork to restart the Duane Arnold nuclear station, Iowa’s only such plant, which shut down in 2020. As I told you on Tuesday, that latter deal took a major step forward when the Department of Energy pledged $1.9 billion toward bringing the single 615-megawatt reactor back online.
Now Google is exporting its strategy to Europe. On Wednesday, the giant announced a 22-year power purchase agreement with the Finnish utility Fortum Oyj to extend the life of the Loviisa nuclear station by buying as much as 50% of its electricity from 2030 to 2049. The contract — the first of its kind in Europe to provide for direct power purchases between a specific power plant and a hyperscaler — starts in 2028.
The deal is part of a broader $15.1 billion investment into artificial intelligence infrastructure throughout Finland over the next two years, and will direct roughly $1.1 billion toward the plant’s relicensing. “Long-term partnerships like the one between Fortum and Google are essential to making that happen, especially in today’s uncertain market environment characterized by low visibility and highly volatile electricity prices,” Fortum CEO Markus Rauramo said in a statement. In a text message last night, Emmet Penney, the director of energy and infrastructure at the Foundation for American Innovation, told me it was once “fashionable to say that nuclear was dead in the West, that we could only look on as nuclear slouched toward its demise and irrelevance.” Now, however, “Google is doing the world a favor by showing why and how that view was wrong” by demonstrating willingness to put its money where its mouth is to expand the power supply, he said. “Some things are fads, but nuclear is never out of season.”
Global investments in manufacturing clean technology fell 14% in the first quarter of 2026 and another 7% in the second three-month window, according to an analysis by the Rhodium Group’s Clean Investment Monitor released Thursday of the first half of this year. For the first time, China’s share of green manufacturing investments dipped below a third, marking a significant decline from its peak of over 71% in 2023. A major drop in the expansion of solar panel factories accounted for much of the slowdown. Investments in new factories fell by 83% in the second quarter of 2026 compared to the peak in the last three months of 2023. China accounted for 94% of the decline. But China’s contraction came with expansion elsewhere. India, for example, saw solar factory investments accelerate from 5% to 48%, making it the largest net contributor for the past four quarters. Solar manufacturing is expanding in the U.S., and the Department of Commerce’s new import duties on the polysilicon needed to make most panel components should help that continue. But the overall picture for clean energy investment, as my colleague Emily Pontecorvo described in the spring, is mixed.
There are green shoots, however. While the amount of capital spent on construction of new manufacturing and industrial plants slowed, the value of such investments rose 10% in the first quarter of this year and held steady in the second quarter, breaking a 10-quarter streak of declines in announced investments. The bulk of the deals were in critical minerals, wind, sustainable aviation fuel, batteries, and — yes — solar. But there’s also more coal. On Thursday morning, the International Energy Agency forecast global coal demand to reach a record high of nearly 9 billion metric tons this year.
The U.S. has enough solar panels in operation today to power more than 50 million American homes, representing over a third of households. That’s according to the latest market analysis conducted by the consultancy Wood Mackenzie on behalf of the Solar Energy Industries Association and released early this morning. Solar developers added 11.4 gigawatts of generating capacity in the second quarter of 2026, a 45% increase from the same period last year and 43% increase from the first three months of this year. Most of that new capacity came from utility-scale projects, which added 9.6 gigawatts — a 61% year-over-year leap. “Solar and storage have grown to a scale most Americans have yet to fully realize and we simply can’t meet America’s growing energy needs without these technologies,” Tim Pawlenty, the chief executive of the solar industry’s leading trade group, said in a statement.
It’s a milestone for solar’s expansion, and highlights the competitiveness of the technology despite the Trump administration’s crackdown on renewables it criticizes as too weather dependent. But it’s only a description of capacity. It’s virtually impossible for all the solar panels in the country to produce power at the same time, and the swings in electricity production are ultimately what draw criticism from those who instead push for generating stations that can pump out power at all times of day. That, in my view, makes the most important signal in the report the speed of the growth, demonstrating how quickly solar can come online and serve surging demand.
Sign up to receive Heatmap AM in your inbox every morning:

Yesterday I told you that a federal court overturned the water permits New Jersey issued for construction of a pipeline to carry more natural gas into the Northeast, delivering a blow to the pipeline push the region is gearing up for as winter energy demands increasingly become what my colleague Matthew Zeitlin described bluntly last year as “a problem.” But there’s some good news, via the latest analysis from the U.S. Energy Information Administration. Enough cheap gas is flowing into New England at a moment when consumption is relatively low to push down prices. Natural gas prices at Algonquin Citygate, a trading and pricing hub in Boston that averages out what New England is paying for the fuel, are now trading at a discount compared to the main U.S. benchmark, the Henry Hub. Prices at Algonquin Citygate averaged 43 cents per million British thermal units less than Henry Hub from April through July. Part of the price drop came from a drop in demand as home heating fell off during the summer and solar generation increased during longer sunny days. Increased supply from Appalachia was another factor, as was a spike in imports from Canada.
Emissions of greenhouse gases from fossil fuels and agriculture are widely recognized as the primary drivers behind rising global temperatures. But scientists have long warned that, as the planet grows hotter, natural feedback loops will begin to pump more emissions into the atmosphere, from methane seeping out from decaying ancient material in thawing permafrost or carbon dioxide spewing from infernos like those scorching Indonesia’s biggest islands. A new study suggests that those warming-induced greenhouse gases from natural sources could amplify global warming by 20% to 30% this century, adding as much 0.4 degrees Celsius to the global temperature average. The authors of the study, published early Thursday morning in the journal Environmental Research Letters, billed it as the largest effort to date to quantify the combined impact of carbon dioxide and methane from permafrost thaw, wildfires, wetlands, and inland waterways. Permafrost thaw, however, comprises roughly half the projected emissions. The authors came from Stanford University, Woodwell Climate Research Center, research nonprofit Spark Climate Solutions, and the advocacy group Environmental Defense Fund. Even if emissions from human activities reached net zero, greenhouse gases could create feedback loops that raise global temperatures by at least 0.2 degrees Celsius by 2100. A higher emissions scenario could be twice that much warming.
“The results are a wake-up call, and it’s imperative that they be included in the next generation of climate policies,” Robert Jackson, the Stanford University professor and chair of the Global Carbon Project who co-authored the paper, said in a statement.
The Pacific Northwest is poised for a big geothermal push. Hexagon Energy, an independent energy developer, and timber and wood giant Weyerhaeuser Company just inked a strategic partnership that will clear the way for geothermal projects across the latter company’s vast property portfolio in Oregon and Washington. “Geothermal energy represents an emerging opportunity to provide clean and reliable, around-the-clock power, and our ownership presents a unique platform to evaluate that potential in the Pacific Northwest,” Kendall Fountain, Weyerhaeuser’s vice president of energy and natural resources, said in a statement. Once built, the projects are expected to generate up to 3 gigawatts of power.
A new paper from Energy Innovation and GridLab lays out some options for Governor Gavin Newsom — or whoever comes next.
California’s continued progress on climate change may depend on whether the state can find a way to bring down its high electricity rates, which hurt the economics of cleaner technologies like electric vehicles and heat pumps and make climate action more politically difficult.
Ahead of the upcoming governor’s race, the clean energy research firms Energy Innovation and GridLab convened a group of more than 20 local electricity experts to develop a policy roadmap for the state’s next administration to reduce energy costs. They published the findings on Thursday, describing a number of opportunities for policymakers to better manage utility spending and more fairly allocate costs among utilities, residents, and communities.
“There is so much work to be done to correct for and address the underlying forces that have led to consistent rate increases over the last 25 years,” Mike O’Boyle, the senior director for policy and strategy at Energy Innovation, told me. There are also no quick fixes, he added. Instead, the report offers directional solutions rather than specific policy proposals, recognizing that it will take years of sustained leadership to make progress.
By far the most significant force driving California’s high rates, especially over the past decade, is the cost of responding to and preventing catastrophic wildfires. The state Public Advocate’s office recently found that the wildfire-related share of the average customer’s bill is 14% to 19%, or $21 to $41 per month.
Just before the Labor Day weekend, Governor Gavin Newsom faced a showdown with the legislature over his proposal for how to reallocate wildfire liability. For weeks, Newsom had been pushing lawmakers for a package that would reduce the amount of money utilities would be on the hook for after their equipment sparks a wildfire. One of his priorities was to outlaw subjugation, a mechanism by which insurance companies sue utilities to recover the cost of paying out wildfire claims. Newsom was responding to pleas from utilities warning that their credit would be downgraded unless the state reduced their share of the risk. Lower credit ratings would mean increased borrowing costs and, ultimately, higher electricity rates.
The full details of Newsom’s package were never released to the public, but it saw major pushback from insurance companies and victims groups who framed it as a "utility bailout.” Eventually, with just a few days left on the legislative calendar, the governor and legislature put out a compromise bill. It did nothing on subrogation, but it would have blocked hedge funds from buying up and reaping profits from insurance claims, and blocked bonuses for C-suite utility officers when the company sparks a fire.
Despite the supposed compromise, the bill died on the floor of the Assembly. Speaker Robert Rivas said it “does not yet deliver the relief, accountability or meaningful reform that Californians deserve” and vowed to go back to work to “deliver real results.”
Lawmakers may have been convinced by the market’s quick reaction to the bill. The Monday after it was released, California utility PG&E’s stock dropped 20%, while Edison International, which owns Southern California Edison, saw a drop of 23%. Last Wednesday, after the deal had fallen apart, PG&E announced that it would defer $2 billion in capital spending for the next year. In a pre-recorded video, the company’s CEO Patti Poppe discussed how far the company has come since its 2019 bankruptcy, praising its recent track record of no ignitions and innovative investments in grid modernization, but said it was “unable to fund the continued transformation at our current pace. When risks go up, lenders charge more.”
The issue Newsom was trying to address stems from the fact that California assigns full liability to utilities when their equipment sparks a wildfire, regardless of whether the incident was the result of negligence. That’s only one part of the problem, however. The other is that the state leans heavily on utilities to do the majority of its wildfire prevention work, rather than spreading out the responsibility across a broader array of residents and communities. The liability policy also amplifies the second issue, as it creates a perverse incentive for utilities and their regulators to try to reduce the risk of sparking a fire to as close to zero as possible, no matter the cost.
Electricity ratepayers cover both the liability utilities face after a fire as well as the cost of all of that risk reduction — but they spend far more on the latter. Between 2019 and 2024, utility regulators authorized the state’s three private electric companies to recover $40 billion in wildfire-related costs from its ratepayers. Just a third were liability-related costs, such as insurance premiums and payments into a fund utilities can draw on to cover settlements with victims. The rest was mitigation.
The Energy Innovation and GridLab report puts aside thorny questions about wildfire liability and focuses on addressing this mitigation side of the issue with three overarching recommendations.
First, California needs a better way to evaluate the cost-effectiveness of different types of wildfire mitigation. Part of the issue is that when a utility says it needs to spend $200 million on tree trimming in Lake Tahoe, for example, regulators don’t have the tools to assess whether there’s a more cost effective alternative. Maybe $100 million on tree trimming with another $20 million for other kinds of community hardening would provide the same amount of risk reduction.
Second, the state could better leverage public finance, for example by expanding the use of ratepayer-backed bonds to pay for wildfire mitigation. California started down this path in a big utility package passed last year, authorizing utilities to borrow $6 billion from ratepayers through 2035 — a lower-cost form of finance than investor equity. Utilities are spending $9 billion per year on wildfires, however, so that measure was a drop in the bucket.
Third, the state should more equitably spread the responsibility of mitigating wildfire risks, re-allocating some costs from ratepayers to taxpayers and at-risk communities. Utilities spend $9 billion a year on wildfire-related costs, but the state’s Department of Forestry and Fire Protection’s most recent mitigation budget was just $440 million. “The reality is that the status quo of ratepayers paying for all this is untenable,” O’Boyle said. Utility-led mitigation focuses on preventing ignitions, but it doesn’t address factors unrelated to electric infrastructure that can worsen a blaze, such as overgrown forests, development near wildlands, and brush surrounding homes.
While the fracas around Newsom’s compromise package focused on the liability aspects, the bill would have also taken small steps toward some of these recommendations. It required CalFIRE to develop standards for wildfire risk reporting data and incorporate them into community risk reduction metrics — a move toward better evaluations of the most cost-effective measures.
It also would have required the state’s Natural Resources Agency to create a comprehensive statewide community wildfire preparedness strategy, provide support for counties to develop protection plans that align with the strategy, and base state support on communities’ annual progress updates.
We’ll see if any of that gets salvaged. While the legislative session is officially over, Newsom could still call a special session to get a wildfire bill done this year.
This is what we’re tracking in energy and climate over the next four months — and beyond.
This is an edition of Heatmap Daily, an evening review of the day’s news written by our executive editor. Sign up for it here.
We’re in the last third of 2026. In yesterday’s newsletter, I looked at the biggest planned upcoming events in climate and energy policy that we’re tracking at Heatmap for the rest of this year.
Today, I want to look at some of the biggest questions that I’m pondering for the rest of the year.
What will the AI backlash mean for data centers and energy demand?
In just the past 24 hours, existential concerns about artificial intelligence has gone mainstream. Even though AI engineers have warned that the technology could trigger some kind of mass fatality event — or even human extinction — for years, the resignation of Sam Coxon from Anthropic seems to have broken through into a new tier of public awareness. “We really do earnestly believe AI could kill all humans! I personally think it is >10% within the next decade,” Evan Hubinger, an Anthropic employee, posted on X after Coxon’s resignation broke.
It’s unscientific, but I’ve seen more celebrity Instagram posts, vertical videos, and concerned messages from friends about AI doom in the past day than I have in weeks. Senator Bernie Sanders is now holding a bipartisan meeting next week to discuss the “extraordinary dangers” posed by AI, according to Axios.
We already know that the public detests AI data centers. But so far the data center story has been somewhat severable from the AI story — voters, politicians, and journalists could talk about the AI infrastructure buildout separately from the tales of, say, AI allegedly solving century-old math problems. Will that remain the case? Or will the two stories merge? If that happens, will politicians and AI safety experts start to encourage (or even empower) the data center backlash because it might slow down AI’s overall development? What will that mean for the politics of infrastructure, electrification, and load growth — and will it cut greenhouse gas emissions?
What will happen in Iran, how high can oil go, and what will it mean for the energy system?
President Donald Trump has never been “looking for long term” in Iran, yet his war continues to drag on without an obvious or easy resolution. It has dragged energy prices up with it.
The global crude benchmark has now edged above $100. Gasoline costs more than $4.20 a gallon on average in the United States (and far more in Europe), and diesel is even more expensive. According to an ongoing estimate from Brown University researchers, the war has now cost Americans more than $100 billion due to energy inflation since it began. Hostilities have seemed to intensify in the past few days; Iran fired missiles at U.S. Navy ships and the United States responded by destroying oil tankers.
This has been generally bad for European economies, which are to some degree still recovering from the triple shock of Covid, energy inflation from Russia’s invasion of Ukraine, and China’s ongoing export boom. At the same time, the Iran war has broadly vindicated China’s energy strategy, which has used electrified technology, strategic stockpiling, and a coal, solar, and battery-dependent power grid to reduce economic dependence on seaborne liquid fuels. (China’s greenhouse gas emissions actually fell in the second quarter because of a drop in the country’s oil consumption.)
The most urgent question here, of course, is whether President Trump will find a way to end the war that he began earlier this year — and how expensive oil and liquified natural gas will get in the interim.
But an end to the war will trigger another set of questions about what this energy shock will mean for energy, climate, and industrial policy going forward. Shocks like these tend to dominate national strategy for years or decades after they happen; Thailand’s government announced last month that it’s backing off LNG imports in favor of renewables. Will we start to see a wider set of countries do the same? Will more countries build strategic oil stockpiles, driving up oil demand in the short term? And will more middle- and low-income countries embrace Chinese-made electric cars in the name of boosting energy security and cutting their oil dependence?
Will the U.S. get bipartisan permitting reform?
The most important political question this year — if you are a normal person — is whether Democrats will take over the House of Representatives and even the Senate in the upcoming midterm election. But we aren’t normal people here at Heatmap. And the midterm elections will, for us, only commence the year’s most interesting political moment.
Right now, lawmakers from both parties say they are trying to reach a deal on bipartisan permitting reform. Such a bill would make it easier to build transmission lines, renewable energy, and some fossil fuel infrastructure, as well as presumably restraining the president’s extralegal war on solar and wind. It could even make it easier for the government to build public infrastructure of all sorts.
We haven’t seen the text of such a deal yet — although my Shift Key interview with Daniel Palken, a permitting expert at Arnold Ventures, offers a lot of clues to its potential content. So it remains an open question whether lawmakers can reach a deal in November and shepherd it through a lame-duck Congress before the end of the year.
If they can, it could enable a future president to conduct a faster and more aggressive clean energy or infrastructure buildout than was previously imaginable. If they can’t, then it will be hard to imagine when such a deal might ever come together, as it has failed to congeal under almost every partisan combination of a president and Congress.
Will 2026 be the hottest year ever?
Back in the spring, climate scientists assigned low odds to the probability that 2026 would become the hottest year ever measured. Since then, though, a monstrous El Niño has clawed out of the Pacific Ocean, nudging up global temperatures and contributing to America’s record-breaking summer.
2026 now has a greater than 33% chance of eclipsing 2024’s hottest-year-on-record title, according to a late July estimate from Carbon Brief; the odds have probably risen further since then. Either way, 2026 will probably come in about 1.5 degrees Celsius warmer than the pre-industrial average — and 2027 is very likely to be even hotter.
Are we entering a post-Trump, post-2010s energy and climate era — and what will it look like?
President Donald Trump is about as unpopular as he has ever been, and on a range of issues, he seems to be losing touch with the American public. Simply by dint of being the country’s most prominent political figure for most of the past 10 years, he has become an establishment politician. He now champions AI, data centers, and the Iran War, for instance, while Americans seem skeptical of all three (at best).
In the next several months, these trends are all likely to intensify: Trump is likely to lose control of Congress — at least according to the polls and the betting markets — and a new presidential election will begin, one in which he will probably not be running.
Which isn’t to say that Trump will lose his grip on the Republican Party or its voters — nor that his actions in the coming years will be lawful, or even Constitutional. But nevertheless if you squint, you can begin to imagine what a post-Trump political era might look like, and it is quite different from the epoch that we have just lived through. It is an era where voters will likely be more worried about inflation and the cost of living than unemployment and economic growth. It is an era where Democrats will be looking to play up economic populism and where the federal deficit might matter again. It is an era where Millennials will be in their prime earning years, where politicians will fear a backlash to industrial policy and infrastructure buildout, and where America’s role in the world will remain unsettled.
It is, in short, not at all like the era that gave us the Green New Deal or the other energy and climate policy of the early 2020s; even if a recession hits and employment becomes a major concern once again, then the resulting political environment might look more like 1992 (or even 1937) than 2008. We are, in short, entering a new era — one we’re excited to watch, develop, and cover here at Heatmap.