You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:

Goodhart’s Law tells us that “when a measure becomes a target, it ceases to be a good measure.” The disagreements climate diplomats were having last week highlight why.
Last week, climate negotiators sparred in Bonn, Germany, over a New Collective Quantified Goal on climate finance. The NCQG, as it’s labeled, is a new target for how much money governments must mobilize to meet global climate investment needs consistent with goals set down in the United Nations’ landmark 2015 Paris Agreement. Reaching a consensus on the NCQG is the biggest item on negotiators’ plates between Bonn and COP29, the annual United Nations-led conference on climate change, happening this fall in Baku, Azerbaijan. But, true to Goodhart, the global climate targets negotiators are deadlocked over are not good measurements of progress, let alone ones that developed countries measured up to.
In 2009, at COP15 in Copenhagen, developed countries set a goal of mobilizing $100 billion annually for climate investments in developing countries by 2020. In 2015, as part of the Paris Agreement, the world’s climate diplomats agreed to set an updated goal — the NCQG — before 2025. In the interim, developed countries achieved their original goal, although years later than planned and amidst allegations that some of their grants and loans were merely existing sources of development financing dressed up as climate finance. That there is no fixed definition of the term “climate finance” makes the $100 billion target doubly fuzzy: Upon closer inspection, some spending classified as climate finance doesn’t really seem like it should count, while other spending seems to have circled back to donor country governments, consultants, and nonprofits.
Despite these measurement issues, negotiators at Bonn pressed for an ambitious updated target. There was consensus that the NCQG could not be less than $100 billion annually — but that is where agreement ended. While negotiators from developing countries ― particularly those from African and Asian governments ― called for an NCQG as high as $1.4 trillion annually over the next five years, developed country negotiators refused to commit to a figure, choosing instead to argue over which countries should be expected to pay. Held up over this disagreement, Bonn ended without a resolution even on what a range of possible NCQGs could look like.
Whatever its size, this target means nothing without a plan to deliver it. What’s more, the back-and-forth over the size of the bill and who foots it took up so much time last week that two other long-standing debates were neglected: The first over what type of financing the NCQG should prioritize ― a measurement issue ― and the second about the obstacles (or “disenablers,” as negotiators called them) in the way of achieving that level of financing — a target issue.
As to the type of financing, the share of total official development assistance sent from G7 governments and the European Union to African countries is at its lowest in 50 years, making it possible to conclude, as did an EU negotiator at Bonn, that “public resources alone will not suffice” to meet the NCQG. The growing scale of the climate challenge, weighed against this apparent (if arguably self-imposed) inadequate public spending by developed countries, has prompted policymakers to advocate for greater private-sector involvement in meeting global climate finance targets. The United States in particular has placed heavy emphasis on the need to “mobilize private capital.” This agenda has prompted Global North governments and the World Bank to attract private investors to decarbonization projects in developing countries.
Developing country negotiators and civil society advocates, meanwhile, have long criticized the fact that the majority of the climate financing we know about has come in the form of loans and not grants, and that most of the loans ― some of the ones from the public sector and all of the private loans ― are issued on market-rate rather than “concessional” terms. In other words, all this so-called help places an undue burden on the balance sheets of developing countries, especially as global interest rates stay high.
Some negotiators are looking to incorporate these arguments into the NCQG as a measure of the quality of the financing developing countries receive. And this is where the conversation around the obstacles begins.
One can argue that loans of any kind are better than nothing at all; long-term investments require long-term debt financing. But market-rate loans in the Global South carry prohibitively high interest rates, reflecting the greater risks that private investors think they face when investing. The International Energy Agency confirms that “the cost of capital for a typical solar PV plant in 2021 was between two‐ and three‐times higher in emerging and developing economies than in advanced economies and China.” While policymakers, particularly at the World Bank, are developing tools to “derisk” these investments such that they can be profitable at market interest rates, it’s still not clear that private sector creditors will respond with enthusiasm. Under these conditions, many climate-vulnerable communities are liable to be locked out of capital markets.
Debt, after all, is not inherently bad. High debt-to-GDP ratios don’t mean anything in and of themselves — indeed, taking on debt to finance crucial investments can (and should!) be prosperity-enhancing and increase a country’s future borrowing capacity.
But today’s global economic system is structured in such a way that debt places a needlessly heavy burden on developing countries, contributing to a “crowding out of crucial development spending,” per findings of the UN Development Programme. Almost 40% of developing countries are setting aside over 10% of their governments’ total revenues to cover interest payments; 62% of developing countries’ external public debt is owed to private creditors (again, at market rates). And these figures don’t include the debt that individual firms take on to finance, say, energy infrastructure. Even that requires the governments of developing countries and development banks to derisk low-return projects across much of the Global South, a process which can plant “budgetary time bombs” on those governments’ balance sheets. Where decarbonization is concerned, private balance sheets are also public liabilities.
Developing country governments and firms also face interest rate and foreign exchange shocks, as higher U.S. interest rates and the concomitant threat of currency depreciation strain their abilities to service external debts. The perverse effect is to prioritize hoarding dollars earned through exports as potential shock absorbers rather than channel them toward domestic investment goals. Loans become a millstone around a government’s policy goals, rather than a measurement of its ambitions.
These liquidity risks loom over climate-vulnerable countries. Take Egypt, where this summer is expected to be brutally hot enough to force its government to import more grain and more gas ― putting increased pressure on the already-volatile Egyptian pound ― and to seriously threaten labor productivity. Egypt’s latest Nationally Determined Contribution, its national climate plan, states that it needs approximately $35 billion per year between now and 2030 to meet its climate targets. Yet the International Monetary Fund expects Egypt to spend $50 billion a year on interest payments in that same period, all while Egypt’s recent bailout agreement with the IMF commits to “put debt firmly on a downward path.”
This debt-climate nexus or climate risk doom loop, exemplifies why developing country negotiators and civil society advocates have hesitated to embrace loan-based climate finance. Debt today need not “crowd out” debt-financed climate spending tomorrow. But that’s exactly what’s happening.
So where does that leave us? For all diplomats’ focus on the NCQG target, how they measure it does matter. As it stands, $100 million of climate finance in the form of market-rate loans to developing countries might seriously threaten their debt sustainability. But developed countries, the multilateral development banks, and the International Monetary Fund can change the nature of debt finance. They can commit to making debt easier to bear by offering lower interest rates and extending loan terms. They can issue more of this concessional debt, of course, displacing the panoply of private lenders that currently play in sovereign bond markets. They can reform their lending standards such that they no longer penalize borrowers for carrying high debt-to-GDP ratios when huge debt-financed investment is precisely what staving off climate change requires. And they can set up dollar swap lines to provide developing countries with the resources to manage interest rate and currency value shocks.
These strategies, if fleshed out in practical detail, can sidestep fickle private investors, contribute to an investment-friendly reform of the global macroeconomic architecture, and kickstart a virtuous cycle of green development around the world. That’s the target. Can we measure up to it?

Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
The Iran war has been a gift to the country’s vehicle, solar, and battery business.
This is Heatmap Daily, a weekday evening digest written by our executive editor.
Happy Monday and welcome back. For months now, we’ve been talking about how the U.S. and Israel’s war in Iran has been a boon for electric vehicles, clean energy, and (unfortunately) coal.
But today we got data that confirms: This clean energy export boom is not just a side story. It is one of the brighter spots in the overall Chinese economy, which remains the world’s second largest.
According to economic data released on Monday, China grew 4.5% during the summer quarter as compared to the quarter from a year earlier. That means the country will likely hit its growth target this year, albeit on the low end.
The country’s economic expansion wasn’t driven by domestic consumption, however. Consumer confidence remains low, and residential investment has yet to return after the property crash earlier this decade.
Instead, booming exports are now driving China’s economy. Exports were more than 36% higher in September than a year earlier, driven by chips, ships, electric vehicles, and solar panels and batteries. The country will likely record its biggest trade surplus ever this year.
Some of those categories are clearly flourishing thanks to the global AI boom — think chips and even batteries. But the preponderance of vehicle exports suggests surging oil prices aren’t hurting. Sales of ‘new energy vehicles,’ a category that includes 100% electric vehicles and plug-in hybrids, were up more than 13% on a year-over-year basis in September, according to the Chinese car manufacturer’s trade group. But exports of these vehicles are booming. Battery electric vehicles were up 130% last month compared to the same period in 2025, and plug-in hybrid exports were up more than 200%.
It’s interesting to consider how much the Chinese and U.S. economy are mirroring each other at this moment. Americans are dealing with a remarkable investment boom, which is buoying the labor market and stubbornly maintaining high inflationary pressure. China is struggling with deflation, and exports are its quickest path to growth. (Consumer sentiment in both countries, interestingly, seems to be in the doldrums, even though American consumers appear to be in much better shape.)
When thinking about what artificial intelligence could do for the United States over the next decade, some subject-matter prognosticators (and even some Anthropic employees) imagine a world of 4%, 5%, or even 7% GDP growth. Such a growth rate is difficult even to envision in the modern era, of course, and it seems like it could propel the U.S. economy to staggering prosperity.
I know better than to make a prediction about where we’re headed. But amateur economic commentators should keep China in mind, too: a country that dominates along many technological axes, but where the standard economic math of supply, demand, and consumer sentiment still holds. Except if the United States economy were to stumble, no exterior source of demand will come to our rescue.
Endurance Energy hoped its generator would run for a full year, but the team isn’t afraid of the “error” in “trial and error.”
About 300 miles off the Oregon coast, a mile beneath the ocean’s surface, a startup just drilled the world’s first subsea geothermal well. And for a grand total of exactly 8.7 seconds, its prototype power plant generated about 2 kilowatts of net power. It wasn’t quite the result the Seattle-based Endurance Energy was hoping for — the company’s goal was to run its 100-kilowatt generator for a full year. But it’s not nothing.
“We really proved with this mission that a geothermal well could be drilled and completed on the seafloor, and doing that within 21 months of the company existing I think is really a testament to our pace of progress,” Endurance CEO Andrew Redd told me.
A former SpaceX engineer — as so many climate tech founders seem to be — Redd appears quite comfortable with the rapid trial-and-error cycles that hard tech startups often demand. Or as he stated in the company’s press release, which provides a refreshingly frank account of what this first test did and didn’t accomplish, “We follow the adage ‘make it exist, then make it good.’”
Investors seem to be buying it. In June, the startup raised a $54 million Series A, led by Peter Thiel’s Founders Fund — Endurance’s second funding round in less than two years of existence. Still, the team certainly has their work cut out for them. The ocean is a notoriously difficult operating environment: Saltwater is corrosive and offshore infrastructure is difficult and expensive to build, maintain, and repair.
Indeed, Endurance spent the first 11 days of its three-week stint at sea debugging its drill, which the team had never operated underwater before. But with a vessel chartered and a locked-in deployment date, the company couldn’t afford to wait for everything to work out perfectly. “We were still working on that generator hours before it got on the seafloor,” Redd told me. He’s used to that sort of thing, though, comparing it to making final tweaks to rockets already sitting on the launchpad. “That’s kind of the name of the game,” he said.
The trial took place at Axial Seamount, an active underwater volcano and the only place in the world with a cluster of hydrothermal vents connected to shore by fiber optic cable, which allows the Endurance team to monitor and control its system in real time from Seattle. While this was the company’s fifth deep-sea mission, it was the team’s first attempt to actually drill their own well.
After lowering their drill about a mile below the surface, the team bored two holes and turned the second into a well about 2 inches wide, lining it with pipe and sealing it with cement. But after losing so much time to debugging, the team only managed to drill about 52 feet deep — far short of its original 200-foot target.
Water then flowed up the well at about 260 degrees Celsius (around 500 degrees Fahrenheit), but the narrow borehole proved too restrictive to deliver enough heat for the generator to operate. So the team pivoted, connecting the generator directly to a naturally flowing, hotter hydrothermal vent instead. The generator then ran for a total of 29 seconds, producing about 2 kilowatts of net power for 8.7 seconds. That represents the total electricity the turbine generated, minus the 7 to 8 kilowatts needed to run its supporting components, such as the refrigerant pump and other onboard equipment.
Then a software glitch triggered the onboard battery safety system, which shut down the plant. When the team tried to restart the system, the power cable feeding the refrigerant pump failed, leaving the pump unable to restart. That was the end of the road. The mission wrapped up after three weeks at sea, a far shorter run than the team had hoped.
“The success criteria would be if we had left with the generator still on the seafloor; that would have been an example of sustained net power, and we didn’t get there,” Redd told me. Instead, the team brought the system back to Endurance’s Seattle headquarters, where it’s fixing the software as well as refurbishing and upgrading the hardware — which includes changing how it builds and tests subsea cables — to prepare for another mission sometime this winter. This time, the goal will be to generate sustained power from a much deeper well.
The team will need to demonstrate progress soon to keep its next major milestone on track: a planned 2-megawatt deployment off the coast of Tonga by the end of 2027. The project aims to supply electricity directly to the Tongan grid, which today is heavily dependent on expensive, imported diesel. Redd expects subsea geothermal to be cost-competitive with that fuel in this first pilot.
Getting there, however, is a formidable engineering challenge. While it’s long been a subject of academic curiosity, no one prior to Endurance had ever drilled an offshore geothermal well before, meaning the team can’t simply transplant existing land-based technology to the seafloor. “Every component that you would use terrestrially now needs to be either modified or built completely from scratch,” Redd explained. “And so you multiply that across every component required to make these kinds of infrastructure projects happen, and it’s a lot of work.”
No kidding. But if Endurance can pull it off, Redd sees this resource as “the perfect energy source for the future.” A conference paper presented by the geoscience company Viridien last year estimates that offshore geothermal resources worldwide could yield about 6 terawatts of recoverable electric power — nearly twice the world’s current continuous electricity output.
“We can access terawatts of power. There’s no fuel. We can site next to extremely large cities around the Pacific. We have no surface presence,” Redd said, ticking off the advantages. Plus, the three necessary ingredients for a high-quality geothermal well — permeable rock, high heat, and water — are widely accessible offshore, he added. Eventually, he expects subsea geothermal to undercut natural gas in Endurance’s target markets: electricity grids, industrial facilities, and data centers across the Pacific Islands, the U.S. West Coast, and Northeast Asia, all of which sit along the undersea volcanic zone known as the “Ring of Fire.”
The way Redd sees it, advances in subsea technology pioneered by the offshore wind, oil, and gas industries have cleared much of the technological path to making underwater geothermal a viable clean energy resource. In his view, what’s been missing is simply the ambition to chase the opportunity in the private market. SpaceX, he said, really proved what’s possible for a scrappy startup to achieve.
“It is quite new at industrial scale for a small company with a bunch of fairly young people to go after something like this,” he told me. “Before SpaceX went to launch a rocket as a private company, no one thought you could get to orbit as a private company. And so that has really seeded this ambition.”
On Greenland’s deepsea mining ban, Indonesia floating nuclear, and a solar boom
Current conditions: Hurricane Trudy has weakened from its peak as a Category 2 storm but still threatens up to 8 inches of rain as it swirls off Baja California • A nor’easter is howling through the Mid-Atlantic this week, hammering the coast with winds of up to 70 miles per hour • A humid overcast has settled over Paris this week as French authorities struggle to regain control after protests over living costs gave way to anarchic riots.
At least 47 major data center projects have been delayed, withdrawn, or blocked so far this year, according to data the regulatory intelligence service RegLayer shared with the Financial Times — and that may be a “conservative estimate.” Just 35% of planned data centers are “credible,” analysts told the newspaper, as more than 1,000 communities across the United States now have restrictions on artificial intelligence infrastructure. The data comes as investors look increasingly jittery about AI following ChatGPT-maker OpenAI’s missing a key revenue metric this year.
Those findings stand in contrast with the numbers from our data service, Heatmap Pro. Based on our research, at least 107 projects faced cancellation so far this year, putting 2026 on track to beat last year, which saw 108 proposals nixed.
Unless you’re living off the grid and away from any social media (if so, I’m jealous), then you can probably surmise that not-in-my-backyard opposition prevails in many such cases against proposed data centers. That makes selling would-be neighbors on the projects critical. New polling by the advocacy group GoodPower found that a binding promise to protect local electricity rates boosts support for the projects upward by as much as 14 points. Such a pledge worked primarily on the 78% of voters who distrust data centers. Another potential winner: Pair a data center with renewables. At least 46% of respondents to the poll said their support would increase if a project were powered by renewables. The survey spoke to 2,610 registered voters last month and oversampled in states with at least 200 data centers completed: Arizona, Georgia, Indiana, Pennsylvania, Texas, and Virginia.
Greenland wants to find ways to exploit its mineral riches in hopes of generating enough income from industries other than fishing and tourism to eventually wean off subsidies from the governments of Denmark and the European Union. Earlier this month, as you may recall, the self-governing Danish island gave a project the green light. But the government in Nuuk doesn’t want miners harvesting metals from the seabed surrounding the Arctic island, which are fertile fishing grounds and could, in theory, lead to mineral production without meaningful infrastructure to create jobs for Greenlandic people. Last week, the Greenlandic Parliament adopted a resolution requiring the government to draft legislation banning deep-sea mining. All members present voted to approve the proposal, according to Sermitsiaq, a leading newspaper in Nuuk. The ban would, if adopted, last until the end of 2029, with the possibility of an extension for two years at a time.
Sign up to receive Heatmap AM in your inbox every morning:
Long before the race for small modular reactors kicked off, Russia launched a floating nuclear power station and sailed the vessel up to the Arctic to power a small town. Now, as you may recall, the state-owned Russian nuclear company Rosatom is making plans to build more floating nuclear plants, and it has a major nuclear newcomer nation as an offtaker. Last week, NucNet reported, Rosatom announced a deal with Indonesia’s state-owned PT Pembangkit Listrik Nuklir to supply electricity to northern Indonesia from at least two floating nuclear plants with a capacity of 200 megawatts each.

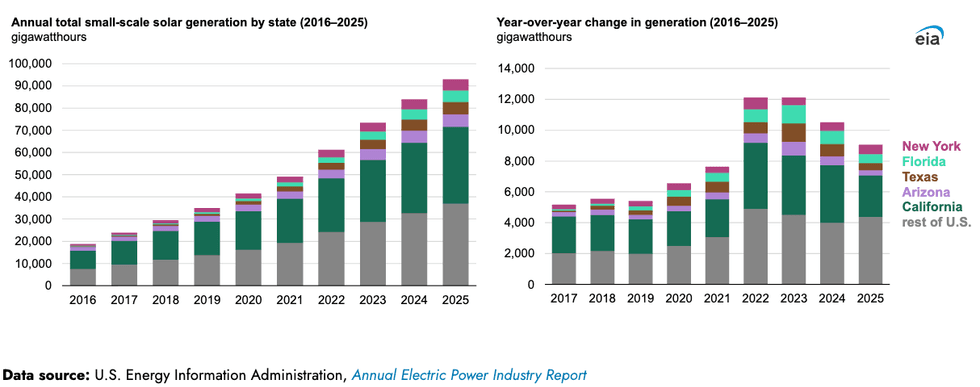
Over the past decade, small-scale and rooftop solar systems increased from 18,812 gigawatt-hours to 92,979 gigawatt-hours, an increase of over 394%. That’s according to a new analysis from the Energy Information Administration, which found that California, Arizona, Texas, Florida are the regions with the most abundant solar resources. Even though the state has worse solar resources in general, New York ranked fifth as a result of growing capacity. Still, the rate of growth in generation has slowed over the past three years. l
The Trump administration is pulling out all the stops for Alaskans who want to drill and transport fossil fuels, mine minerals, and log trees. Now he’s easing rules on hunters. A new final rule from the National Park Service has revived a hunting method the Biden administration banned in 2024: Baiting bears with doughnuts soaked in bacon grease. Hunters use the baits to lure bears to close range before shooting them. “Some hunters prefer to use strong-smelling, high-calorie foods like pastries, doughnuts, meat scraps or fish remains to lure bears from miles away,” The New York Times reported. “But some conservationists say the practice is unethical and risks making the bears accustomed to human food, which could endanger people.”