You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:

Maybe you’ve never heard of it. Maybe you know it too well. But to a certain type of clean energy wonk, it amounts to perhaps the three most dreaded words in climate policy: the interconnection queue.
The queue is the process by which utilities decide which wind and solar farms get to hook up to the power grid in the United States. Across much of the country, it has become so badly broken and clogged that it can take more than a decade for a given project to navigate.
On this week’s episode of Shift Key, Jesse and Rob speak with two experts about how to understand — and how to fix — what is perhaps the biggest obstacle to deploying more renewables on the U.S. power grid. Tyler Norris is a doctoral student at Duke University’s Nicholas School of the Environment. He was formerly vice president of development at Cypress Creek Renewables, and he served on North Carolina Governor Roy Cooper’s Carbon Policy Working Group. Claire Wayner is a senior associate at RMI’s carbon-free electricity program, where she works on the clean and competitive grids team. Shift Key is hosted by Robinson Meyer, the founding executive editor of Heatmap, and Jesse Jenkins, a professor of energy systems engineering at Princeton University.
Subscribe to “Shift Key” and find this episode on Apple Podcasts, Spotify, Amazon, or wherever you get your podcasts.
You can also add the show’s RSS feed to your podcast app to follow us directly.
Here is an excerpt from our conversation:
Robinson Meyer: Can I interject and just ask why, over the past decade, the interconnection queue got much longer — but also over the past decade, 15 years, the U.S. grid did change in character and in fuel type a lot, right? We went from burning a lot of coal to a lot of natural gas. And that transition is often cited as one of the model transitions, one of the few energy transitions to happen globally that happened at the speed with which we would need to decarbonize. Obviously, switching coal to gas is not decarbonizing, but it is a model — it happened fast enough that it is a good model for what decarbonizing would look like in order to meet climate goals.
Evidently, that did not run into these kind of same interconnection queue problems. Why is that? Is that because we were swapping in within individual power plants? We were just changing the furnace from a coal furnace to a gas furnace? Is that because these were larger projects and so it didn’t back up in the queue in the same way that a lot of smaller solar or wind farms do?
Claire Wayner: I would say all the reasons you just gave are valid, yeah. The coal to gas transition involved, likely, a lot of similar geographic locations. With wind and solar, we’re seeing them wanting to build on the grid and in a lot of cases in new, rather remote locations that are going to require new types of grid upgrades that the coal to gas transition just doesn’t have.
Jesse Jenkins: Maybe it is — to use a metaphor here — it’s a little bit like traffic congestion. If you add a generator to the grid, it’s trying to ship its power through the grid, and that decision to add your power mix to the grid combines with everyone else that’s also generating and consuming power to drive traffic jams or congestion in different parts of the grid, just like your decision to hop in the car and drive to work or to go into the city for the weekend to see a show or whatever you’re doing. It’s not just your decision. It’s everyone’s combined decisions that affects travel times on the grid.
Now, the big difference between the grid and travel on roads or most other forms of networks we’re used to is that you don’t get to choose which path to go down. If you’re sending electricity to the grid, electricity flows with physics down the path of least resistance or impedance, which is the alternating current equivalent of resistance. And so it’s a lot more like rivers flowing downhill from gravity, right? You don’t get to choose which branch of the river you go down. It’s just, you know, gravity will take you. And so you adding your power flows to the grid creates complicated flows based on the physics of this mesh network that spans a continent and interacts with everyone else on the grid.
And so when you’re going from probably a few dozen large natural gas generators added that operate very similarly to the plants that they’re replacing to hundreds of gigawatts across thousands of projects scattered all over the grid with very complicated generation profiles because they’re weather-dependent renewables, it’s just a completely different challenge for the utilities.
So the process that the regional grid operators developed in the 2000s, when they were restructuring and taking over that role of regional grid operator, it’s just not fit for purpose at all for what we face today. And I want to highlight another thing you mentioned, which is the software piece of it, too. These processes, they are using software and corporate processes that were also developed 10 or 20 years ago. And we all know that software and computing techniques have gotten quite a bit better over a decade or two. And rarely have utilities and grid operators really kept pace with those capabilities.
Wayner: Can I just say, I’ve heard that in some regions, interconnection consists of still sending back and forth Excel files. To Tyler’s point earlier that we only just now are getting data on the interconnection queue nationwide and how it stands, that’s one challenge that developers are facing is a lack of data transparency and rapid processing from the transmission providers and the grid operators.
And so, to use an analogy that my colleague Sarah Toth uses a lot, which I really love: Imagine if we had a Domino’s pizza tracker for the interconnection queue, and that developers could just log on and see how their projects are doing in many, if not most regions. They don’t even have that visibility. They don’t know when their pizza is going to get delivered, or if it’s in the oven.
This episode of Shift Key is sponsored by …
Watershed’s climate data engine helps companies measure and reduce their emissions, turning the data they already have into an audit-ready carbon footprint backed by the latest climate science. Get the sustainability data you need in weeks, not months. Learn more at watershed.com.
As a global leader in PV and ESS solutions, Sungrow invests heavily in research and development, constantly pushing the boundaries of solar and battery inverter technology. Discover why Sungrow is the essential component of the clean energy transition by visiting sungrowpower.com.
Antenna Group helps you connect with customers, policymakers, investors, and strategic partners to influence markets and accelerate adoption. Visit antennagroup.com to learn more.
Music for Shift Key is by Adam Kromelow.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
‘Our entire company was built for this purpose.’
After decades of stagnation, the nuclear industry has drummed up all kinds of ideas meant to revive the prospects for building reactors in the United States. Make the reactors smaller. Micro, even! Cool them with helium or molten salt instead of water. Invite the Koreans or Canadians to come teach us how to construct atomic power stations again.
Yet the startup bold enough to name itself The Nuclear Company launched in 2024 on a simpler thesis: Just go with the large-scale reactors we have built before, and construct them in bulk to bring down costs.
Essentially, do what the Chinese did.
While the U.S. struggled for 15 years to complete its first two Westinghouse AP1000s, the 1.1-gigawatt units designed at the dawn of this century to be America’s flagship nuclear technology, China built four in the same time period. Beijing then reverse-engineered the technology to make its own version with an entirely domestic supply chain. China now has 10 operating Hualong One reactors and at least 37 more on the way. The U.S. ultimately completed its first two AP1000s at Southern Company’s Alvin W. Vogtle Electric Generating Plant in eastern Georgia right around the same time.
The Nuclear Company was formed by hiring former managers who oversaw the Georgia project. Despite the Trump administration’s pledge to finance construction of at least 10 more large nuclear reactors, the only projects that have broken ground are new, first-of-a-kind small modular reactors that skeptics fear will face the same billion-dollar cost overruns that the AP1000s faced at Plant Vogtle — but without the same output of electricity to balance out the expenses.
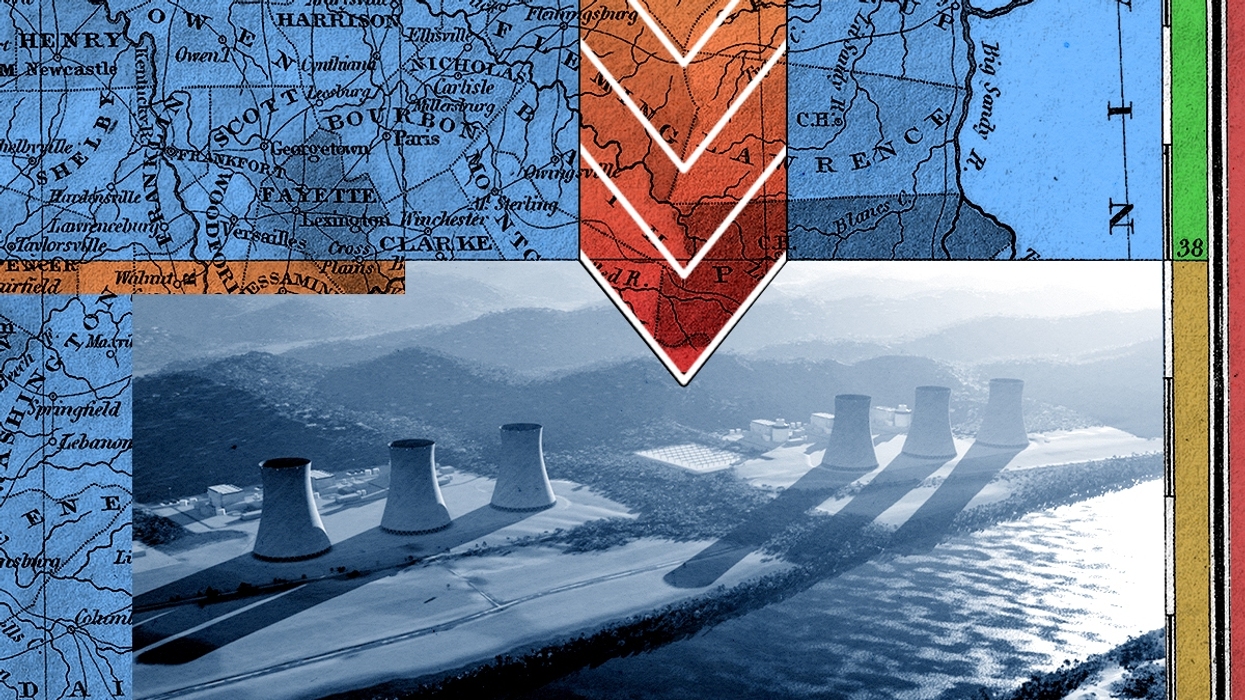
On Wednesday morning, The Nuclear Company announced its most significant attempt at a Chinese-scale buildout yet. The firm unveiled plans to build 6.6 gigawatts of new, large-scale reactors at a greenfield site in Kentucky, along the Ohio River. Dubbed Prosperity One, the project would be located in Lewis County, on property once assembled for a coal-fired station that was later abandoned. The site sits half a mile from a 765-kilovolt transmission line that connects to PJM Interconnection, the nation’s second-largest and arguably most stressed grid system.
“Our entire company was built for this purpose,” Joe Klecha, The Nuclear Company’s chief nuclear officer and a former manager on the Plant Vogtle buildout, told me. “We recognize that this is different and unique in our country. We believe it’s very much needed.”
The project will begin with two reactors at a time; the Kentucky site has room for up to six. The Nuclear Company is already negotiating potential offtake agreements with electricity buyers to help finance construction, and it expects deals by next year. The company told me it has not yet decided whether it will run the Prosperity One as an independent power provider or sell the facility to a utility or another plant operator. “We are preserving all options and will make that decision as we pull the other partners onboard formally,” Klecha said.
Since its inception, The Nuclear Company has focused on the AP1000 as the most promising design in the U.S. That’s particularly true after the Nuclear Regulatory Commission certified the Vogtle Unit 4 design last week as the permanent, settled schematic for future AP1000s.
But Klecha left open the possibility of another technology. “The AP1000 is our basis for the site at this point, but we’ll continue to evaluate other options as we get through the site characterization,” he said. He expects that process to wrap up in “the first half of next year.”
The company’s options are limited, though. Last month, as I reported, South Korea agreed to help the U.S. build up to six new AP1000s at an as-yet-unspecified site in addition to constructing at least two APR1400s — that is, essentially the Korean version of the American technology. In theory, The Nuclear Company could build APR1400s, too. But it’s highly unlikely, since Westinghouse accused the state-owned Korea Electric Power Corporation of ripping off its technology for the APR1400 in 2022. That led to a yearslong lawsuit and settlement that gave the American company the right to demand royalties and keep Seoul out of markets where Westinghouse aims to compete.
The only other viable option is the ABWR. The world’s first so-called advanced reactor, the ABWR was built with General Electric’s boiling water reactor technology, which is used across about a third of the U.S. fleet. It serves as the second-most popular design after Westinghouse’s pressurized water reactor model. Japan successfully built four ABWRs over a decade from 1996 to 2006, and Taiwan nearly completed two before killing the project in a bid to phase out nuclear power altogether. The NRC certified the ABWR for construction in the U.S., but a project in southern Texas that aimed to build the first in the U.S. was scrapped about a decade ago.
“The ABWR has an impressive pedigree of construction success as well as experience being built to U.S. standards that is hard to find outside of the Vogtle project,” Brett Rampal, a veteran nuclear consultant who advises Deloitte and Veriten, told me. Still, he said, the AP1000 is the leading contender for the Kentucky site.
Rampal said Prosperity One represents a welcome break from how large-scale reactors have been planned in recent years. While most of the industry remains focused on small modular reactors, research I covered last month indicates the technologies could face worse cost problems than large-scale units, and the emerging consensus on building AP1000s focuses on expanding existing nuclear plants.
Indeed, The Nuclear Company’s first major deal was to help Brookfield Asset Management, which owns 51% of Westinghouse, complete a thwarted AP1000 project at the V.C. Summer plant in South Carolina. But other potential sites considered for new AP1000s included expansions of Florida Power & Light’s Turkey Point nuclear plant in Florida, the Tennessee Valley Authority’s Bellefonte nuclear station in Alabama, or even adding another two units to Plant Vogtle.
“A lot of the thoughts around AP1000s and large reactors have always been around existing or already-licensed sites,” Rampal said. “It’s very interesting to see TNC’s first project buck the trend of what folks have been talking about around the large reactor story in this country."
At least one thing is certain about The Nuclear Company’s approach: It will settle on one design. The company is animated by the need to avoid one of the U.S. nuclear industry’s biggest financial mistakes, known simply and derisively as “Whoops.” In 1983, the Washington Public Power Supply System — WPPSS — triggered what was then the largest municipal bond default in U.S. history after its buildout of several different reactor designs at once fell apart in a major boondoggle.
Building different reactors at Prosperity One “really goes against our mission, our vision, and our thesis as a company,” Klecha confirmed.
The key is repeating the same design over and over again so the project managers sort out the fastest, most efficient ways to build and workers hone skills in actually constructing the design. “Six AP1000 units on one site creates the scale and repetition needed to drive down costs and sends a strong signal to the supply chain,” Lin Yuan, the senior advisor at the Nuclear Scaling Initiative, a non-profit collaboration working to create the enabling commercial and policy conditions for safe and secure nuclear energy scaling, told me in an email. “Manufacturers and craft labor need to see a sustained order pipeline to invest in capacity, factory expansion, and training.”
Vogtle Unit 4 came online in 2024 roughly 30% cheaper and faster than Vogtle Unit 3, completed a year earlier. Klecha said that’s the minimum cost reduction The Nuclear Company expects for the first two reactors built at Prosperity One.
“The 30%, I would say, is the floor on the savings from the first unit to the second unit,” he said. “How do we capture those lessons? Obviously, our team’s experience. We have a pretty rigorous ‘lessons learned’ document.”
Soon, he hopes, there will be even more lessons learned — in concrete, rather than on paper.