You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:

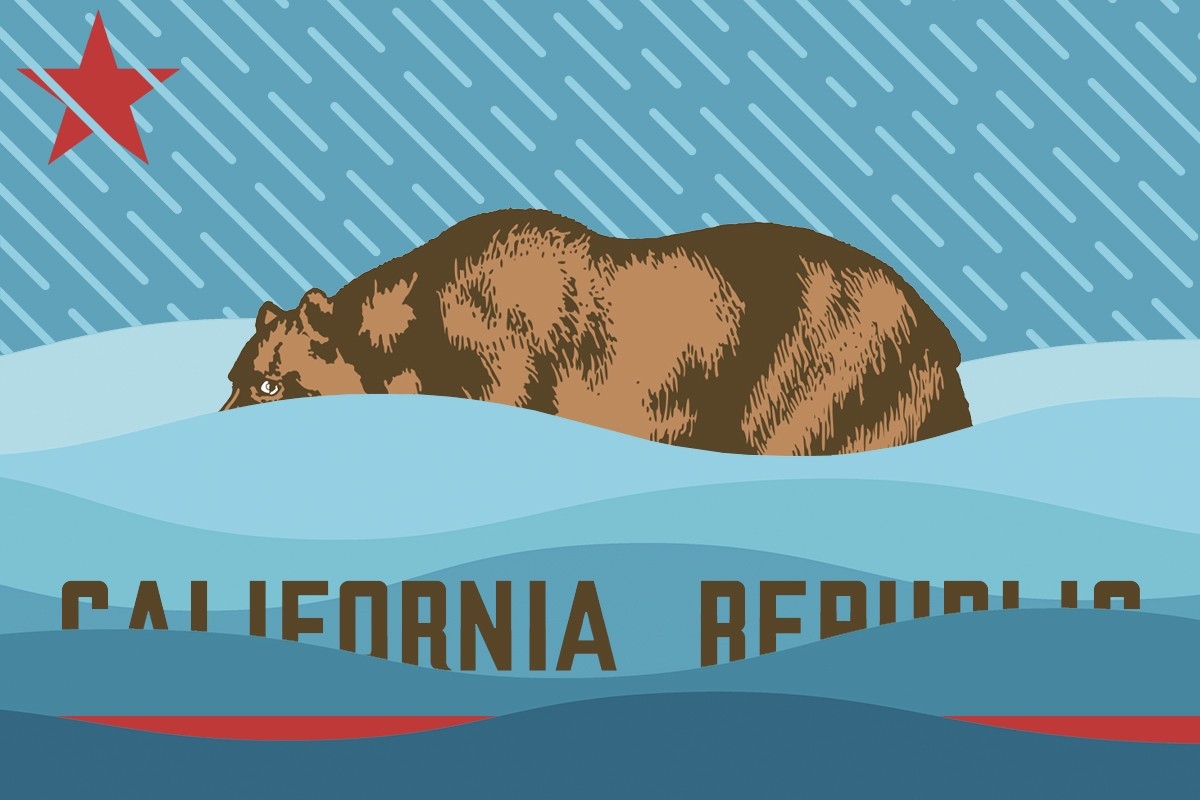
More Californians have searched for news about “floods” in 2023 than “wildfires,” which seems in keeping with this summer’s series of out-of-left-field climate disasters. The worst smoke pollution hit … the East Coast. The deadliest wildfire in modern U.S. history leveled … a former wetland in Hawaii. Naturally a hurriquake in Los Angeles and catastrophic flooding in Palm Springs would come next?
But California’s reputation as the land of drought and fire has obscured the fact that extreme flooding is the other player in the state’s deadly climatological triumvirate. From the atmospheric rivers this winter, which caused some 500 mudslides and inflicted as much as $1 billion in damage, to Hurricane Hilary dumping record-breaking rains over the southwestern United States this weekend, floods are understandably top-of-mind (especially with a relatedly somewhat slow start to the state’s fire season).
Here’s what you need to know about the future of extreme floods in the Golden State:
Former Hurricane Hilary was the first tropical storm to make landfall in California in 84 years, easily snapping the practically nonexistent late August daily rainfall records around L.A. In fact, hurricanes making landfall in the lower lefthand corner of the U.S. is so rare that there isn’t actually much of a data record for scientists to use as a point of comparison, Inside Climate News reports — which makes forming future projections and establishing links to climate change actually rather difficult.
What we do know is this: California has largely avoided hurricanes in the past due to the generally cold waters off its coast, which NBC News describes as acting as a sort of “shield” for the state. Hurricanes get their strength and moisture by forming over warm waters, and the eastern Pacific has historically been as much as 9 degrees cooler than the same latitude in the Gulf of Mexico.
But California’s shield has a crack. July was the hottest recorded month on planet Earth and the waters Hilary passed over on its journey north were 4 degrees warmer than usual, the Los Angeles Times explains. Sure enough, research shows that hurricane landfalls in the eastern Pacific could increase dramatically along with global and oceanic warming — bringing more rain and floods along with them.
There are certain conditions that made Hilary particularly unusual, however: A heat dome that formed over the central United States, for example, helped tug the storm directly over California, as opposed to a more typical path of a hurricane or tropical storm being pushed out to sea by easterly winds off the continent. So while hurricanes might be more intense and wet in the future, they won’t necessarily continue to make it over to California the way Hilary has.
Yes, to some extent. In addition to greenhouse gas emissions making the oceans warmer, the weather pattern called El Niño is likely responsible for some of the warming of the waters off of Baja California, which intensified Hurricane Hilary. But again, there were also unique conditions that contributed to Hilary’s unusual path over the southwestern United States, including the prevailing wind patterns. Strong El Niño years, as a result, don’t necessarily mean more hurricanes for Southern California.
El Niños have tended to bring higher winter rainfalls to Southern California, though that is also not necessarily a guarantee. NOAA’s outlook for the coming winter doesn’t currently show above-average precipitation expected for the state. Some El Niño years are actually drier than average, which goes to show that “El Niño is just one hand on the atmospheric steering wheel,” Weather Underground writes.
California isn’t a land of droughts or floods — it’s a land of both. A better way to think about the future of weather in the state is as one of extremes.
That’s because, “[i]n a seeming paradox, drought and flooding are two sides of one coin,” Governing explains. “A warmer atmosphere can hold more water, and higher temperatures cause more water on the Earth’s surface to evaporate. This can result in bigger rainstorms.”
The good news is, most of California is now free of drought conditions and this year’s fire season has been quieter because of all the wet vegetation. But while Tropical Storm Hilary apparently only inflicted minor damage and no known deaths this weekend, floods have been a devastating fixture of life in the Golden State before and they will be again.
As Yale Climate Solutions warned earlier this year, “Given the increased risk [due to climate change], it is more likely than not that many of you reading this will see a California megaflood costing tens of billions in your lifetime.”
California doesn’t need 40 days and nights of rain to experience its worst-case flood event, researchers have found. If a 30-day rainstorm similar to one that hit the then-unpopulous state in 1862 were to strike again today, it could potentially be a $1 trillion disaster — “larger than any in world history” — UCLA’s “ARkStorm 2.0” scenario modeling found last year.
“Every major population center in California would get hit at once — probably parts of Nevada and other adjacent states, too,” Daniel Swain, a UCLA climate scientist and co-author of the paper, said in a statement at the time.
Unlike a tropical storm, which passes in a number of days, the ARkStorm flood event would last a month in the form of sequential atmospheric rivers, like the kind that battered the state this past winter. The link between climate change and heavy precipitation is well understood, and the researchers found that “climate change has already doubled the likelihood of such an extreme storm scenario,” with “further large increases in ‘megastorm’ risk … likely with each additional degree of global warming this century.”
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
The Senate’s compromise bill enters the chat at a moment when federal land and anti-pipeline advocates are already quite activated.
The AI data center backlash is getting louder in D.C. ahead of the midterms – and it’s poised to collide head-on with the new permitting reform deal being negotiated in Congress.
This week, major environmental advocacy organizations are taking large public steps to lean in on the data center fight. The League of Conservation Voters and Sierra Club, I’ve been told, are imminently announcing a $250,000 ad buy in the Washington, D.C. market focused entirely on decrying fossil fuel-powered data centers and Trump administration policies to speed up their construction. The Wilderness Society, a prominent land conservation organization, announced it now supports a moratorium against data centers on “public lands” focused on the roughly half billion acres under the Interior Department’s stewardship. And Earthjustice on Thursday did a detailed report claiming that 80% of the data centers under development “bringing their own power” are going to rely on gas generation.
“We are trying to reach a D.C. audience and add to the conversation on data centers,” Sara Chieffo, LCV’s head of government affairs, told me of the ad buy. “We’re at a time when there have been no regulations passed at the federal level on Big Tech, or data centers, and we have communities from very many different backgrounds, across the political spectrum, really shouting for enforceable safeguards to be put in place for data center development. For their pocket book, for air and water, and for having a say in what their actual communities look like.”
In a vacuum, all of this action would feel normal – what environmental organization isn’t focused on data centers right now? And if this much fossil fuel is going to be burned in the name of computing, why wouldn’t these groups be focused so intently on the problem?
But there’s another wrinkle: It’s impossible to ignore the elephantesque permitting debate in the room, given any progress on a bill would undoubtedly help data centers with any kind of federal nexus, as well as some of the large fossil power infrastructure they’re demanding.
Last week, we all learned of the Bipartisan American Affordability and Jobs Act, or BAAJA, which would radically change federal permitting for essentially all large infrastructure projects with a federal nexus. The bill, negotiated by top Republicans and Democrats in the U.S. Senate, aims to expedite bureaucratic review processes for industrial projects with any presence on federal lands, water pollution risk covered under the Clean Water Act, and/or potential impacts to federally-protected species habitat and historic sites. Many of these changes, like significantly narrowing claims under the National Environmental Policy Act, could mean quicker permitting decisions from the federal government; other policies in the bill, like a truncated statute of limitations for lawsuits, could mean developers avoid significant and costly litigation risk as they apply for federal permits.
There’s a lot to potentially love in this bill for decarb hawks – transmission reforms and permitting certainty, among other things. But the bill is incredibly divisive, especially amongst those interested in seeing renewable energy boosted without undue compromise for fossil fuel development and preserving the existing legal framework for protecting the environment through litigation. So controversial is this bill that all of the organizations I’ve mentioned – LCV, Sierra Club, NRDC, Wilderness Society, Earthjustice – have so far eschewed explicit formal statements opposing the bill, instead expressing caution about air and water impacts while saying they need more time to review it and speak with lawmakers.
It’s clear though the environmentalist community wants people to think about data centers as debate on the bill approaches. Those who publicly oppose the bill at this moment say its enactment under the current administration would fully unlock federal acreage for the worst incarnation of an unfettered fossil-powered data center boom. “In any permutation, this bill is a good thing for data centers,” said Brett Hartl, director of government affairs for Center for Biological Diversity. After the bill was introduced, an organizing call between environmentalists leaked revealing discussions on how to stop it from gaining traction. One idea raised, per a transcript of the call published by Punchbowl News, was leaning heavily into talking about AI data center permitting.
I asked Chieffo if the LCV ad buy was related to the permitting debate in D.C. She told me it was in the works before senators introduced the bipartisan permitting deal last week. “This is a longstanding focus of ours, to make sure the buildout of data centers do not perpetuate dirty energy or exacerbate the climate crisis,” she told me. Then I asked, if this isn’t about the permitting bill, but it is about federal policy about approving data centers, then how do AI data centers play into the conversation around permitting reform? Do you see the AI data center conversation playing a role in the permitting reform debate?
“The way I would answer that is, well, there are equities and impacts that permitting reform has on the ability to build data centers in this country. And there’s a much larger conversation that should be happening – and isn’t yet happening – around fully holding data centers and Big Tech accountable for their environmental and consumer impacts, safety, and broader regulation. It’s a much bigger conversation than just permitting conversations,” Chieffo told me.
Then she added something else: “The provisions in conversation right now in the Senate do not cover the full suite of what we believe we need to see to hold data centers accountable and address the environmental impacts, let alone the other impacts folks are concerned about with jobs, safety and the rest.”
There’s absolutely a hypothetical risk that enacting such sweeping permitting legislation could enable a faster fossil-powered AI data center buildout, particularly in two ways: federal land development and easier pipeline permits.
We know that President Trump’s executive order encouraging data centers on federal land has led to interest in developing large projects on Interior Department acreage in Arizona, Idaho, Nevada, Oregon, and Utah. How many of these projects are serious is unclear, partially because the federal land permitting process is opaque, and also due to some permitting applications gleaning more early-stage speculation than a commitment (see: Clearway’s reversal on this project). At least some of this development would be powered by gas, as we’ve previously covered.
There’s also the pipelines. We’ve previously covered how the bill’s changes to the Clean Water Act would take away a provision under the law previously cited by Democratic governors to block pipeline expansions, while limiting state and tribe authority under the law to cite impacts other than direct water discharges when rejecting or blocking permits. In the name of project certainty, the bill would also enshrine protections against approval revocation for all kinds of energy facilities, including pipelines. Many of the pipelines under development today are capacity expansions and not explicitly for data centers, and many of them may be approved regardless of whether BAAJA becomes law. But it’s almost impossible to divorce new gas projects from the data center industry’s fortunes, given climbing demand.
Advocates for decarbonizing the U.S. economy who support the bill say the legislation offers a safer trade-off than critics suggest. They put forward that most data center development is not on federal lands, rendering much of the actual AI infrastructure outside the scope of the bill’s impacts. In addition, they argue there are potential upsides, like the bill’s provisions unlocking new transmission development, expediting interconnection queue processing, and making data center developers pay for new energy grid upgrades, all of which could be good for renewable energy development.
Grayson Flood, a senior fellow at Groundwork Collaborative, told me he believes the bill will actually incentivize more data center developers to hook up to the grid and may result in fewer projects relying on off-grid gas plants constructed purely for operating GPUs. Studies have shown building off-grid can be almost twice as expensive. By reducing barriers to connection, and encouraging new transmission that unlocks renewable energy, Flood said one can easily see a pathway to a cleaner data center sector in the future under the bill.
“At the end of the day, if you want these data centers to be powered by clean, firm capacity, anything from solar and storage to wind and storage to nuclear, geothermal, and hydropower, you’re going to need to have a grid that can bring those sources to the data centers, and right now we really don’t have that,” said Flood, who previously worked as legislative director for Rep. Alexandria Ocasio-Cortez. “At a macro level, we need the bulk power system built out to see the power we want to see, and this bill makes data centers pay more than any other piece of proposed federal legislation to make that happen.”
Where does this leave us? Over the next month, we’ll live through a midterms election cycle chock full of ads activating anti-data center sentiments on both sides of the aisle. Then, right afterwards, the energy sector will pivot its attention span back to Congress and fight to pass a permitting bill that will not primarily benefit data centers, but clearly has upsides its opponents will want to call attention to.
Yes, charging when power is cheap will save you money — but not everyone has that luxury.
There’s no escape when gas prices spike. You might know a station across town that’s always a dime cheaper per gallon than everybody else, but that’s about the best a driver can hope for. There’s no service station down the street that sells half-price gas after midnight. No Chevron is changing its gas price moment by moment, its big neon sign flashing like a stock ticker.
That’s exactly what’s possible as the world moves to electric cars, though. Electricity markets are complex and volatile, responding moment by moment to movements in energy supply and demand, weather, and other factors. Cars, when they’re left plugged in all day or overnight, can take advantage, charging whenever electricity gets cheap.
This dynamic environment, offering flexibility in price and in time, opens up money-saving opportunities for EV drivers that were impossible in the one-price-fits-all gasoline days. But it also creates potential drawbacks — at least for those who have fewer choices about when and where they charge.
Andrew Peterman, the director of advanced energy solutions at Rivian, touched on this topic last week during the future of mobility session at Heatmap’s New York Climate Week event. Peterman says Rivian owners do 80% to 90% of their charging at home on level 2 plugs, where the vehicle might remain parked for 14 to 16 hours.
Suppose you live somewhere like California and you come home from work in the evening. Everyone else is returning home just then, too, turning on their home A/C and causing a spike in electricity demand. “If you plug in your vehicle then and start charging immediately, you're adding strain to the grid,” he said. “But you have this really long dwell time where you may only need to charge for a few hours or a couple of hours.”
The solution — scheduling the EV to start charging later — is a core feature that’s available in many electric vehicles. Rivian is working on the step beyond that: partnering with utilities to create smart, demand-responsive charging that defers fueling until the price has fallen below a particular threshold. Given the volatility of energy markets, that’s something best handled autonomously, freeing the car’s owner from having to check on energy prices or guess when they’ll be lowest.
Those smart charging setups will pave the way for the next phase in the smart electric home: the virtual power plant, where a homeowner’s solar panels, EV battery, or home backup storage could feed power onto the grid to help balance the system during stressful times. VPPs represent yet another way the smarter grid could save electric car drivers money — in this case, making some back by letting the grid borrow energy stored in the vehicle.
What these strategies have in common is flexibility — allow the car to sit plugged in all night at home until you leave the next morning, all workday if there are plugs available at the office, or all day long if you don’t need to leave the house that day. It’s a smart approach. Our cars, while made for driving, spend most of their lives sitting around doing nothing. But not everyone has that luxury.
We’ve mentioned the problem before in terms of the convenience tax: For people who can charge at home and don’t have to drive a vast distance every day, EV ownership is more convenient than driving on gas. Say so long to stops at the gas station; just refill your battery every night in your own garage. For people who can’t regularly charge at home, it’s worse. Going to a public DC fast charger for 20 minutes is more annoying than the old-fashioned gas station pump and go.
The same thing holds for money. Those who can charge at home have much more control over the cost than those at the mercy of public charging infrastructure. Some of the Tesla Superchargers near me in the Los Angeles area cost $0.60 per kilowatt-hour in the middle of the day, when people are out and demand is high, but pricing drops to more like $0.35 in the wee hours of the night. If you can wait until midnight to charge, then you can save a huge percentage. Other networks are similar. EVgo charges the highest rates during the 4 to 9 pm period of peak demand and the lower rates during “super off-peak” hours from midnight to 8 am.
Not everyone, though, has the time flexibility to go sit in the dark at a charging station to save a few bucks.
It’s going to get even weirder than that, too. Tesla has begun to employ dynamic pricing that changes not only based on time of day, but also on station business. Prices jump if more of the plugs are in use, a move that could be read, ostensibly, as an attempt to balance charger traffic by creating an incentive to drive to less busy ones. In practice, some users say they’ve started driving to a Supercharger with one promised price and found a higher price when they arrived, just because a few other cars had arrived in the intervening minutes. (Ionna, the fast-growing charging network that represents a collaboration of the major automakers, said in an August blog that it maintains a single price all day long, at all of its stations, so drivers don’t feel like they’re being duped.)
As Peterman said, most EV drivers charge at home, where they have more control over how much they’re going to pay than at either the gas station or a public charger. But as more people think about switching over to electric so they can quit gasoline, they’re going to find the question of how much it costs to drive to work gets a lot more complex than it used to be.
The state’s market is in such disarray, a Democrat actually stands a shot at winning the office.
In the waning weeks of the midterm election cycle, the question of who will serve as Oklahoma’s next insurance commissioner is unlikely to be a topic of intense speculation at dinner tables around the country — or in Oklahoma, for that matter.
For one thing, it’s about as down-ballot a race as you can get, another bubble to be filled in alongside state treasurer and superintendent of public instruction. For another, it’s difficult to imagine it will be much of a competition: It’s been two decades since a Democrat last won statewide office in Oklahoma.
But if there ever were a race for an upset, this would be it. Oklahoma is one of the most expensive places in the country to purchase home insurance, with an average annual premium in 2024 of over $5,819 for $350,000 in dwelling coverage — well above the national average of $3,303 and behind only Florida and Louisiana, per the most recent numbers from the Consumer Federation of America. That’s even more staggering given the local cost of living: Oklahomans spend more of their median household income, $65,039, than residents in any other state on home insurance — almost 9%.
When it comes to arguing for greater industry regulation, Democrats are typically on more comfortable footing against their conservative counterparts. Craig MacIntyre, the Democrat in the Oklahoma insurance commissioner race, has promised to use the state’s new “file and wait” law to review rate increase requests closely before they’re implemented. But in a strange reversal of roles, Republican candidate Bob Sullivan won a four-way primary and subsequent runoff that centered on the conservatives arguing over who would be the toughest industry regulator.
The topsy-turvy politics don’t stop there. Republicans in the state have also called out the impacts of extreme weather on premiums, albeit without going quite so far as to blame climate change. Sullivan unabashedly models himself after Trump (“Make insurance fair again!” “Drain the insurance swamp!”) but also set himself apart from the competition by challenging the narrative that severe weather — not climate change, per se — is the primary explanation for the state’s high rates — putting him more in line with the Democrat, who almost hasn’t mentioned weather at all.
It’s a notable break. Extreme weather has long been the go-to explanation for Republicans about the state’s high homeowners’ premiums. “We get our fair share of weather in Oklahoma,” the state’s outgoing, term-limited insurance commissioner Glen Mulready told me. “We’re right next to Texas and Kansas and Arkansas, so they get the same weather we do — that’s the quote we hear all the time,” he added, “which is just simply not true.”
Oklahoma Watch, a nonprofit investigative newsroom that reports extensively on the state’s insurance crisis, has suggested that the insurance industry and its allies in the state might be using hail in particular “as a scapegoat to justify high rates,” given that other states with high instances of hail pay far less in premiums.
It’s true, though, that Oklahoma seems to be a particularly bad place for hail, which is responsible for an estimated $1 billion in annual property and crop damages in the United States. In most of the state, even at the tiny geographical scale of an individual roof, you have about a one-in-10 chance each year of seeing two-inch or larger hail, Ian Giammanco, a lead research meteorologist at the Insurance Institute for Business & Home Safety, told me. Verisk, a risk assessment firm, also found that over the last four years, nearly 50% of Oklahoma roofs were hit by severe hail — the highest rate nationwide.
"Hail gets overlooked, but it’s a huge contributor to rising insurance costs," Michael DeLong, a researcher at the Consumer Federation of America, told me.
Hail’s climate signal isn’t obvious to researchers yet. “We haven’t seen any observational fingerprints that hail appreciably changes” in a warming world, Giammanco said. But while the number of days with severe hail across the U.S. hasn’t changed much, “there may be an upswing in severity that’s just starting to be able to be observed,” he noted. Warmer air, for example, may raise the potential for “really big hail, while the lower end may actually decline.”
Hail is one piece of Oklahoma’s nasty extreme weather cornucopia. Increasingly frequent wildfires, extreme heat, and severe storms and tornadoes also threaten homes (not to mention seismic activity from injecting fossil fuel wastewater underground). Between 1980 and 2024, the state averaged about 2.6 weather disasters per year that cost more than $1 billion in damages, adjusted for inflation, but in the last five years of that timeframe — 2020 to 2024 — it averaged six, including droughts, tornado outbreaks, and blizzards. (The Trump administration retired the National Centers for Environmental Information’s U.S. Billion-Dollar Weather and Climate Disasters database last year, so there isn’t more recent data.)
But the affordability problems don’t exist in a vacuum, and are compounded by historic infrastructure and materials choices. New home construction, for example, peaked at an average of over 2,800 square feet in 2015, meaning a bigger target for hail. “We have lots of field observations of 300 hailstones in a square foot area,” Giammanco told me; in a given storm, more than 800,000 might pummel a house. And while slate and tile roofs — popular construction before the post-war suburban boom — withstand hail well, they’re also slow and difficult to install. Asphalt shingling, on the other hand, is cheap, easy, and popular — and “highly vulnerable to hail, especially as it ages,” Giammanco added.
Republicans have traditionally argued that relatively little can be done about Oklahoma’s high homeowners’ insurance rates, given the state’s weather and larger nationwide trends in inflation-driven rebuilding costs and reinsurance. Karen Collins of the American Property Casualty Insurance Association, an industry advocacy group, further warned the Oklahoma House of Representatives in a hearing last year that cracking down on the industry could drive insurers out of the state. “We’ve seen … when government regulates directly or indirectly price controls on markets with escalating losses, it does turn those affordability challenges into an availability crisis,” she said.
When I asked the APCIA for comment, Walter Gonzalez, the assistant vice president of state government relations, told me in an email that “the story in Oklahoma today is not accelerating rate increases. It’s decelerating rate increases.” He pointed me to data showing that average rate increases among the state’s largest insurers fell from 16.4% in 2023 to 5.3% by 2025, and they’re at just 2.9% so far in 2026. Still, what homeowners actually pay is a different story: Oklahoma was among six states nationally to see homeowners’ premiums increase by more than 20% in 2025, an Insurify report found.
Gonzalez also pointed out that insurers paid close to or more in losses and expenses than they made in premiums over the past several years. In a blog post last year, Mulready wrote that Oklahoma’s top 20 insurers paid out $129 in claims for every $100 in premium collected in 2023, improving slightly to $97 in claims for every $100 in premiums collected in 2024. Critics of the industry, however, argue that focusing on underwriting losses elides a major source of profit for insurance companies: their investments.
Birny Birnbaum, the executive director of the Center for Economic Justice, a nonprofit that works on insurance advocacy for low-income and minority consumers, agreed that recent years have been challenging, especially after the reinsurance market retrenched and doubled prices following Florida storms in 2021 and 2022. But those rates have since stabilized and even declined, he said, yet “the insurance companies haven’t been reducing their premiums to reflect that.” Birnbaum has also been highly critical of Mulready’s approach — a hands-off, free-market approach to the insurance industry designed to spark competition and drive down prices. The insurance commissioner never denied a home insurance rate increase requested by an insurance company during his eight-year tenure, Mulready confirmed to me. Indeed, state statute barred him from doing so, he said. “There is no excessive rate in a competitive market,” he told me.
Birnbaum is not convinced. “For some reason, in virtually every state, the regulatory model is: If we allow the insurance companies to do whatever they want, that will bring them back into the market,” he said. He likened that argument to someone claiming that if we removed the Affordable Care Act’s preexisting condition protections, we’d ultimately end up with more people insured. If you heard that, “you’d go, ‘That’s the stupidest thing I ever heard in my life,’” he said, minus an expletive.
A loose regulatory environment might also mean that Oklahoma ends up subsidizing insurance in higher-risk, more tightly regulated ones. When national insurers take big losses in states like California that have stricter rules around rates, they may increase costs in states where it’s easier to do so, Ishita Sen, a professor of finance at Harvard Business School, told The New York Times. (Mulready has vehemently denied this on his podcast.)
Whether Oklahoma’s insurance market is truly competitive is even an open question to some. The insurance industry’s stance, like Mulready’s, is that the Oklahoma market is competitive, and “market-share concentration alone is not a measure of whether consumers have meaningful coverage choices.” And yet Allstate and State Farm alone represent a little over 40% of the market in Oklahoma.
Breaking with Mulready and the APCIA, Sullivan, the Republican candidate for commissioner, told E&E News that he plans to declare the state’s insurance market “non-competitive” if elected. (In an odd quirk of state law, there is no benchmark at which a market becomes competitive or not; it is entirely at the insurance commissioner’s discretion to declare it as such, so long as they hold a public hearing first.) MacIntyre, the Democrat dark horse, has described the market the same way.
Mulready told me that doing so would be a “mistake.” “The only data point that anyone ever presented to me only proved a competitive market,” he said, citing both the Herfindahl-Hirschman index and the four-firm concentration ratio, two popular forms of measurement. An investigation by Oklahoma Watch, however, found that the Oklahoma Insurance Department counted companies, not insurance groups, giving it rosier numbers on the HHI and CR4 scales and distorting the picture of a “potential oligopoly.” Birnbaum, the executive director for the Center of Economic Justice, told me that Oklahoma has “a complete seller’s market” and describing it as competitive is “laughable.”
That said, either choice for the office on the ballot in November would be “lightyears ahead of the current commissioner,” Birnbaum added. “The two candidates who are running both have better ideas and better values and better understanding of how insurance markets operate,” he said.
The winner will have his work cut out for him, though. Birnbaum stressed that the state has done little to assist in residential storm-proofing — one of the most important levers for bringing down costs — and the existing grant program for roof replacements is woefully insufficient. “It would take probably 50 years at this current level of funding to reach all these [homes], and none of these programs actually require insurance companies to have any skin in the game,” he told me, pointing to Wisconsin and Louisiana as examples of states that require insurance companies to offer discounts that incentivize loss prevention. (Mulready told me the first-come, first-serve grant program, which draws on unused funds of the Insurance Department, has helped replace around 700 roofs since it began in 2025).
In addition to reviewing rate increase requests and opening investigations into insurance companies’ claims payment processes, DeLong echoed the need for a much larger grant mitigation program. “Admittedly, that’s going to be expensive,” he conceded. “But it will be a lot more expensive if you don’t do anything.”
Mulready, meanwhile, laughed when I asked him for his advice for his successor. “That could be awhile,” he said. But he directed Sullivan or MacIntyre to “make decisions based on the data.” That’s what he did, he said. And the years, he mused, have gone fast.