You’re out of free articles.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:

Unpriced risk undermined the global economy during the financial crisis of 2008. Today, researchers say unpriced physical climate risk will lead to rapid declines in property values — and point out that this is already happening in some Florida markets. They often compare what’s happening now to the run-up to 2008. If the analogy holds, we will likely see disruption in other related financial structures. In particular, as the physical reality of climate change begins to have an effect on the attractiveness of bonds in risky areas, the ability of local governments to raise money to adapt to rapidly changing climate conditions may be undercut.
But comparing the effect of the 2008 unpriced risk on the municipal bond market with the potential effects of physical climate risk shows the suffering will likely be much greater this time. Today, there’s a direct, rather than indirect, connection between risk and public finance markets.
The solution? Last week, Tom Doe, CEO and founder of Municipal Market Analytics, said cities should act now to raise as much money as possible for adaptation before the municipal bond market starts pricing in physical climate risk. It’s only going to get more expensive later, in his view.
During the 2008 collapse, issuers of municipal bonds suffered. According to the final report on the crisis, New York State was stuck making suddenly skyrocketing interest payments to investors — the rate went from about 3.5% to more than 14% — on $4 billion of its debt. The Port Authority of New York and New Jersey’s interest rate went from 4.3% to 20% in a single week. Investors who had bought municipal bonds in auctions suffered too, because the pool of new buyers dried up very quickly in early 2008.
Since then, the muni market has bounced back in a big way, with professional investment managers urging tax-avoidant retail investors to buy individual bonds through separately managed accounts rather than through a mutual bond fund or an exchange-traded fund. Most people think $500 billion in bond issues is likely in 2025, and the group of buyers has a seemingly unending appetite for what they perceive to be safe and highly liquid investments — essentially the equivalent of money market accounts that promise federal tax-free interest payments.
But the risks now posed by physical climate change to municipal bond issuers and investors are different and likely greater than they were in 2008. The last time around, the municipal bond market suffered because of a domino effect — the insurance companies the issuers were using were exposed to mortgage risk.
According to the Financial Crisis Inquiry Report, so-called “monoline” insurers (writing policies for single financial structures rather than a broad array of products) had gotten into the mortgage-backed securities business, issuing a boatload of guarantees covering more than $250 billion of these structured products. The CEO of one of these monoline businesses, Alan Roseman of ACA, said, “We never expected losses. ... We were providing hedges on market volatility to institutional counterparties.” In other words, ACA believed its risk was limited because it wasn’t directly investing in the underlying assets — that its risk was limited to ups and downs in the market value of the mortgage-backed securities. But when the value of huge numbers of mortgage-backed securities plunged as the credit rating agencies woke up and repriced the risk of the subprime mortgages buried within them, ACA and other insurers were faced with stunning losses.
Those same insurers (MBIA, ACA, Ambac) were then substantially downgraded. And they hadn’t been insuring only mortgage-backed securities — they were also insuring municipal bonds and “auction rate securities” based on those bonds, structures that allowed local governments to borrow money at variable interest rates. When the insurance companies froze up because of the sudden repricing of mortgage-backed securities and their guarantees became worthless, the auction markets froze, as well. As a result, issuers of muni bonds (and investors in them) suffered.
In other words, in 2008, it was risk in a different financial arena — mortgage-backed securities guaranteed by insurance companies — that slopped over and caused problems for municipal bonds. By contrast, when it comes to physical climate change today, the municipal bond market is directly exposed to the central risk: Will the communities that effectively guarantee these bonds continue to be viable? Will these communities be insurable? Will community property values and thus property taxes suddenly decline?
Not only that, the 2008 risk was different because it could be eventually unwound. Property markets could get going again, as they have in spades. This time, deterioration of the underlying asset — the communities themselves — will likely be irreversible. Chronic flooding will not cease on any human-relevant time scale.
Issuers are not being penalized — yet — for the physical climate risk facing their communities, according to Tom Doe’s conversation with Will Compernolle on the latter’s Simply Put podcast last week. “This risk is not being priced in,” Doe said. “There’s no evidence of that right now. And in addition, the rating agencies have not reflected [physical risk] in their letter scoring of credit risk … so there is not a ratings penalty right now. There’s not a pricing penalty.”
Doe’s suggestion is that local governments may want to get out there and raise as much money as they can for adaptation. “State and local governments who are in harm’s way that need to do this can go to the market right now, and investors are not penalizing them. The market is not. So this is essentially cheap money if they issue [bonds] for these projects today,” Doe said.
That’s one way of looking at the situation. Public money for adaptation is cheap, there’s a lot of it potentially available, and it is much less expensive to raise that money now than it will be once the credit rating agencies and the investors start pricing in physical risk and demanding higher interest payments in exchange for the use of their cash.
It’s a race against time: Eventually, as in 2008, the mispriced risk will be correctly assessed. This time, unlike the last crisis, the harm to the underlying assets will be permanent.
A version of this article originally appeared in the author’s newsletter, Moving Day, and has been repurposed for Heatmap.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
A new analysis by a one-time atomic energy opponent makes a bull case for big reactors.
If you know anything about the cost of nuclear energy in America, you probably are aware that the most recent reactors built — the only two new ones designed, planned, and constructed since the 1990s — were budget busters. Units 3 and 4 of Southern Company’s Alvin W. Vogtle Generating Station in eastern Georgia were the first of a new generation of reactor technology ever to be deployed in the U.S. Construction delays, changes to the design, and corporate bankruptcies ultimately sent the price of the pair of Westinghouse AP1000s — the Ford Mustang of American nuclear technology, with safety features that essentially make them not just powerful but also meltdown-proof — to nearly $40 billion, or about $16,350 per kilowatt.
But the U.S. once built reactors for half that — and it did so in the chaotic aftermath of the nation’s worst civilian nuclear accident, when mounting regulations made atomic power construction more onerous than ever before.
That’s the landmark finding of a new report by a veteran nuclear researcher, who quantified and broke down the cost of constructing nearly every civilian atomic power station the U.S. built in the 20th century. Adjusting the dollar figures using the Handy-Whitman Index, a specialized formula for calculating inflation in the utility sector’s construction costs, the analysis — shared exclusively with Heatmap — concluded that 47 reactors built in the U.S. between the 1979 partial meltdown at Pennsylvania’s Three Mile Island nuclear plant and the turn of the millennium came in at an average of $8,200 per kilowatt.
“Costs are only going to come down from that,” Charles Komanoff, the economist and energy policy analyst whose consultancy conducted the study on behalf of the Clean Air Task Force, told me.
The paper carves out a pathway down the cost curve that runs counter to the industry’s broader consensus at the moment on the best way to make nuclear less of a luxury choice compared to other generating sources. Billions of dollars have flooded into companies promising to commercialize small modular reactors that generate 300 megawatts or less. The concept is a bet on what Komanoff calls the economies of duplication, meaning that if customers need more individual reactors, developers can ride that repetition to lower prices. But the paper suggests that the way developers have historically reduced nuclear costs — through economies of scale — achieves the same per-kilowatt savings with one gigawatt-sized, water-cooled reactor as 20 smaller reactors would net.
Some small and microreactor developers say that using alternative coolants — molten salt, liquid sodium, high-temperature gases such as helium — could further raise the efficiency of their technologies, allowing them to make up for whatever they lose on economies of scale. But large, traditional reactors such as the AP1000 are “a proven technology” that, unlike next-generation reactors with far less operating experience, won’t have to overcome “teething problems” to reach maximum efficiency levels, Komanoff told me.
There are other options to the AP1000, such as the ABWR that the parent companies of GE Vernova Hitachi Nuclear Energy built in Japan and Taiwan in the 1990s. One was planned for Texas, but abandoned a decade ago amid declining interest in nuclear power post-Fukushima. The technology is approved by the NRC, but GE-Hitachi has since turned its attention to its 300-megawatt BWRX-300. Given that no ABWR was built in the U.S., James Boucher, the former Deloitte nuclear consultant who co-authored the paper, said the AP1000 is the reactor best positioned to replicate the country’s successful buildout of the 1980s.
“We have two AP1000s. They're fully built. They’re operating. They’re doing, as far as I can tell, quite well. And they are like these reactors in our sample,” Boucher told me. “If we wanted to build 20, 30, 50 more AP1000s, I think we’d have a good shot.”
The Nuclear Company, a startup developer that hired much of the team behind the Vogtle buildout in a bid to become the go-to project manager for future AP1000s, called Komanoff’s report “promising because it demonstrates how cost can come down when we don’t focus on building first-of-a-kind projects.”
“There was a 30% overnight capital cost reduction just moving from Unit 3 to Unit 4 on the Vogtle project — there is no reason we can’t continue down the learning curve on the next AP1000s built in this country,” Joe Klecha, The Nuclear Company’s chief nuclear officer and president, told me after reviewing the report I sent him. “Especially with our mix of experience building these reactors and advancements in technology we’re leveraging to scale, achieving below $10,000 per kilowatt is just the beginning for us. We believe we can execute safer, faster, and at lower cost than we’ve achieved in the past.”
Back in the 1980s, the military-like regimentation common at nuclear plants and construction sites wasn’t yet as ingrained in the industry. The Nuclear Regulatory Commission had replaced the Atomic Energy Commission, which was seen as too deferential to the companies it oversaw, and spent the decade tightening rules on constructing and operating nuclear plants. New accident scenarios were being discovered, requiring new plants and existing ones up for relicensing to change operating protocols, upgrade equipment, and conduct additional research.
Komanoff was among those pushing for the changes. In reports he authored on behalf of Greenpeace, an arch opponent of nuclear power, he dissected the fiscal woes atomic energy developers faced, making the economic case for shutting down electrical stations that his fellow activists battled on ecological or moral grounds. Eventually, Komanoff moved on to advocating for a carbon tax as the fairest and clearest way to guide the economy away from fossil fuels and toward decarbonization. While serving as director of the Carbon Tax Center, which he co-founded, he noticed a trend among nuclear plants: They were getting better at operating.
The regulatory changes that followed Three Mile Island succeeded in raising the operating efficiencies of nuclear plants. In the 1970s, reactors had a capacity factor — a measure of how frequently a generating source actually produces electricity — of about 50%. Yet by 1991, that number had risen to 70%, putting atomic energy on par with the most efficient fossil fuel and hydroelectric plants. In 2002, that national average hit 90%. In 2019, it rose to 94%. When the final reactor at Indian Point, the nuclear station that served Komanoff’s native New York City, closed in 2021 due to political opposition to its relicensing, it had just set a world record for an uninterrupted 753-day run of electricity production.
Gradually, Komanoff came to see nuclear power as a vital tool for decarbonization. But, ensconced in the climate movement through his carbon tax advocacy, he found it easier to stay mum on his conversion, lest he ruffle the feathers of fellow activists who remained stalwart anti-nuclearists. After all, he thought, if a carbon tax passes, nuclear plants will benefit, so why bother speaking up specifically for atomic energy? Indian Point’s early shutdown, however, caused Komanoff pangs of regret.
“It just forced me to confront the consequences of not advocating for nuclear power,” he said. “I felt the way I imagined I would feel if a climbing partner — I used to be a sort of mountaineer — had died because of some negligence on my part. I really took personal responsibility because I imagined that — and maybe I’m just in a complete fantasy about my shamanistic power — as someone who had argued 40 years ago for shutting Indian Point, that if I had gone public say ‘Don’t do it,’ that I might have been able to begin turning the tide.”
While $8,200 per kilowatt is half of what Vogtle cost, it’s still nearly four times the cost of building a new natural gas-burning power plant with combined-cycle turbines, which itself rose to $2,157 per kilowatt last year from less than $1,500 in 2023. But the “regulatory churn” that kept the price of nuclear high, Komanoff said, is unlikely to return for new nuclear plants using proven designs such as the AP1000.
“Part of my optimism about nuclear being less subject to regulatory churn going forward is because it’s not a whipping boy,” he said. “It’s really hard to overstate the aura of incompetence that surrounded the nuclear power sector in the United States in the ‘70s into the ‘80s. But when you’ve got plants that are averaging 90% or higher capacity factors, things change.”
Current conditions: Oman’s Ayn Athum Waterfalls burst to life this week as rain battered the Gulf nation’s southwestern Dhofar governorate • Severe monsoon flooding has deluged parts of the American Southwest, including Navajo Nation, where at least three people have died • Tropical Storm Dujuan is barreling toward Japan, where it threatens flooding and landslides in Tokyo and Chiba.
When the Houthis stormed Yemen’s Red Sea coast last week, the Iran-backed rebels gained new ground from which to attack boats passing through the vital shipping lane, extending Tehran’s reach from the Persian Gulf’s hotly contested Strait of Hormuz to the waterway on the opposite side of the Arabian peninsula. In response, oil prices surged. But the price per barrel of crude is slipping again as the United States has rebuked Saudi Arabia’s requests for help routing the militants, instead seeking a deal that keeps the Bab al-Mandab Strait open to American and Israeli ships. Over the weekend, U.S. diplomats met with Houthi officials in neutral Oman, Reuters reported. Following the talks, the Times of Israel reported that Houthis promised not to attack any Israeli or commercial ships of any kind, only those linked to Saudi Arabia, which has funded the Yemeni government’s campaign against the rebels.
Satellite images published by the investigative site Hunterbrook showed workers building a bypass on Saudi Arabia’s East-West Pipeline, its main conduit for circumventing oil exports around the Strait of Hormuz, to get around the pumping station damaged by a Houthi attack. But the promise of free movement through the Red Sea sent the price of oil down by between 1% and 4% on Thursday.
Just yesterday, I told you that the Trump administration had moved to drastically change how the government interprets the Endangered Species Act to only consider deaths of protected animals illegal if the creatures were intentionally targeted. Such a shift would exclude the vast majority of deaths linked to energy companies, such as when birds land in toxic oil ponds or collide with wind turbines. Whether federal enforcement ultimately reflects that interpretation depends on the outcome of a forthcoming lawsuit. Already, Earthjustice has vowed to file litigation challenging the Trump administration’s legal memo directing federal agencies on its new view of the nation’s bedrock conservation law. “The government’s new legal position is a prescription for extinction. It says that as long as you claim you didn’t mean to kill an endangered species, the law can’t and won’t stop you,” Earthjustice attorney Ben Levitan said in a press release. “That’s ridiculous — and a totally illegal, active misreading of the Endangered Species Act. We’ll see the Trump administration in court about this.”
The toll wind turbines take on migratory birds is a favorite talking point of the energy source’s opponents. But relief from the responsibility to avoid killing birds would be cold comfort to the wind industry as developers wait for the Trump administration to follow a court ruling requiring it to continue processing applications for turbines. As my colleague Jael Holzman wrote yesterday, the administration has continued delaying. At least one other legal fight within the offshore wind industry has, meanwhile, come to a conclusion. Vineyard Wind and its turbine supplier GE Vernova, announced an “amicable settlement” this week that resolves “all outstanding litigation,” the New Bedford Light reported. The developer sued the supplier in April, accusing GE Vernova of an $800 million breach of contract following a blade failure in 2024.

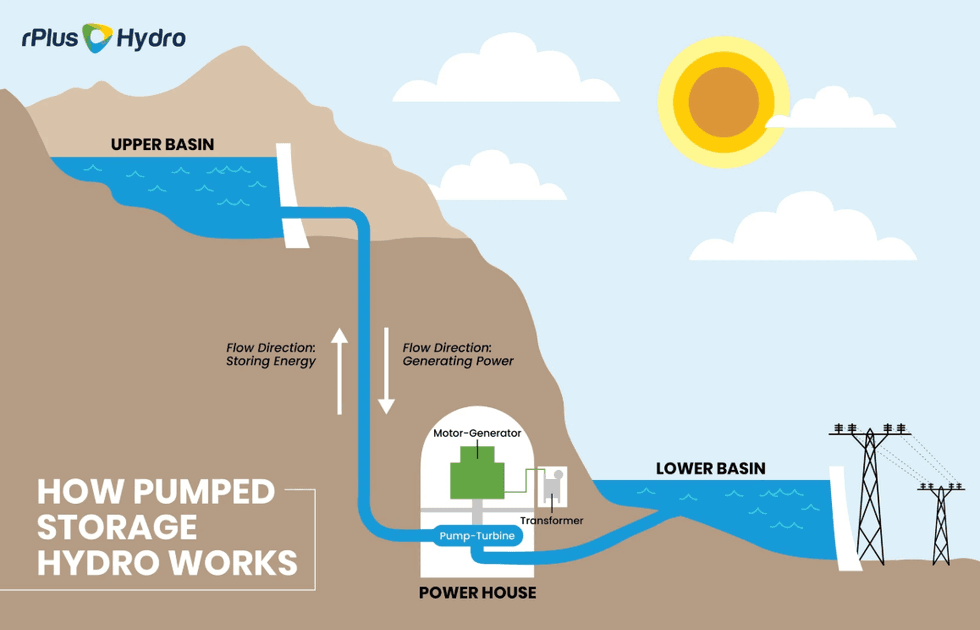
The U.S. needs more long-term energy storage, and few technologies are better tested by time than using excess electricity to pump water into a reservoir, where it can be released downhill and run through turbines to generate huge bursts of power when it’s needed. Back when the U.S. had lots of nuclear power, pumped hydro plants harvested the unused electrons during the night. With solar now producing more electricity during the day in some parts of the country than the grid demands, pumped hydro is seeing a potential renewal. But the U.S. hasn’t built any pumped hydro facilities since the 1990s. A project that looked likely to break that dry spell is now on pause as the Trump administration heeds opponents’ concerns and orders a new study on its environmental impact.
The Federal Energy Regulatory Commission has delayed its decision on whether to license the $3 billion project to add a pumped hydro facility to the Seminoe Reservoir, a lightning bolt-shaped waterway in southern Wyoming. The Bureau of Land Management said it will conduct a supplemental environmental impact statement and open the door to more public comments and input from local officials. “This feels like a small victory,” CiCi Oliver, a fly-fishing shop owner who opposed the project over its potential disruptions to the ecology of the reservoir, told WyoFile this week.
Sign up to receive Heatmap AM in your inbox every morning:
At the start of the Iran War, some interpreters of President Donald Trump’s supposed four-dimensional geopolitical chess moves suggested that shutting down the Strait of Hormuz was an intentional move to show China’s vulnerable underbelly: Beijing’s dependence on oil imports. And yet, China’s vast oil stockpiles and refining capacity, plus its array of alternative energy sources, allowed the country to slash oil purchases by 23% in the first six months of the war compared to the same period last year, according to a New York Times analysis of customs data. “This is a power that nobody thought China had,” said Erica Downs, a senior research scholar at Columbia University’s Center on Global Energy Policy. “Going forward, it’s going to be really interesting to see: What does China do with this newfound power?” The heaviest answer to that question now weighing on Western officials involves China considering the ramifications of a potential invasion of Taiwan to be less worrying than before.
That’s especially true because Taiwan, by contrast, is more vulnerable to losing access to oil and gas imports than ever before. After completing its decades-long mission last year to shut down the nuclear fleet that powered the island’s 20th century transformation into the world’s premiere chipmaker, Taiwan’s ruling Democratic Progressive Party — which advocates for the republic’s continued de facto independence — left the nation dependent on imported liquified natural gas and crude for the vast majority of its energy. Now, according to Nikkei, the government is hastening its efforts to potentially bring at least one nuclear station back online.
Yet another state is considering a moratorium on data centers — one close to the epicenter of the artificial intelligence boom. Maryland, which shares a grid and a border with northern Virginia’s data center megacluster, could see a ban come into effect as early as next year if state legislators pass a bill in the next session. Governor Wes Moore, a Democrat, said he “will absolutely sign” a statewide ban “if it’s coming from local legislators.” Speaking to Punchbowl News, he suggested that any moratorium would come with loopholes for projects that meet high standards. “I believe local jurisdictions should have a say. There are certain local jurisdictions who want it,” he said. “I just need them to understand I have very strict guidelines for what is actually going to get state approval.”
A startup founded by members of the team of U.S. government scientists that first achieved net-energy gain from a fusion reaction has hit a new milestone that should raise the eyebrows of even skeptics of the so-called holy grail of clean power. Less than two months after publicizing its roadmap to commercial fusion, Inertia Enterprises ran a simulation demonstrating that its first commercial plant will be capable of producing 25 times more energy than the laser needed to trigger the reaction, the company told my colleague Katie Brigham in an exclusive.
The company using the only technology proven to achieve breakeven has simulated net energy gain.
Less than two months after publicizing its roadmap to commercial fusion, Inertia Enterprises has checked step one off its list. The startup ran a simulation demonstrating that its first commercial facility will be capable of producing over 25 times more fusion energy than the laser energy put into it, Inertia told Heatmap exclusively.
This is actually the second milestone Inertia has achieved on its 10-point roadmap to building a grid-scale power plant by the mid-2030s — the startup announced last month that it had cut the manufacturing time for its fusion fuel pellets from days to minutes. But for the lay fusion observer, this latest achievement may be the more striking of the two. So far, the only entity to achieve breakeven — the point at which a fusion reaction produces more energy than it consumes — is Lawrence Livermore National Lab’s National Ignition Facility.
Inertia, founded last year by current and former Lawrence Livermore scientists, is now building on that result under a formal research partnership with the lab, using the same technical approach as NIF: firing high-powered lasers at a tiny pellet of fusion fuel, compressing it until the nuclei fuse and release enormous amounts of energy.
The new results, which Inertia said it’s submitting for peer review, demonstrate that the company’s first commercial-scale plant ought to generate over 250 megawatts of electricity for the grid. But because the startup’s machine has yet to be built, the projected energy gain and power output come from a so-called “virtual shot,” a high-fidelity computer simulation that uses the same design codes Lawrence Livermore has used for its own successful ignition experiments, and is thus calibrated and benchmarked against real results.
“We are simulating all the things that we know happen in a fusion experiment, and it’s using the validated models — the best, highest-fidelity physics models that have been validated to NIF ignition experiments — to project where we will be with Inertia,” the startup’s co-founder, Annie Kritcher, told me. The simulation accounts for factors such as “target defects, variations in laser performance, laser delivery, [and] injection tolerances,” she explained.
Even when variables like these fluctuate, Kritcher said, the machine’s energy yield should barely change. That sets Inertia’s system apart from NIF’s, which operates right on the so-called “ignition cliff,” where small imperfections in the fusion fuel target or slight variations in laser performance can determine whether the system achieves ignition at all. But because Inertia designed its system to operate far above that threshold, minor flaws should translate only to modest dips in performance.
Other fusion startups have run simulations demonstrating the validity of their underlying physics and — in industry leader Commonwealth Fusion Systems’ case — even projecting their ability to exceed breakeven. But Kritcher argues that Inertia’s “virtual shot” is a more meaningful achievement because the startup’s plant design replicates the underlying physics validated by NIF, the only fusion experiment yet to cross breakeven in the real world. “The extrapolation risk for the other validation simulations is much, much, much higher,” she told me.
Kritcher has experienced this risk firsthand during her many years running experiments at NIF. When the facility fired its first real shots at ignition in 2011, she was working as a post-doctoral researcher at the national lab, and sincerely believed these early experiments would be a success. But the shots turned out to be “orders of magnitude off” from achieving their goal, thanks to the “unknown unknowns and the physics that weren’t included” in the team’s initial modeling.
Other companies that haven’t yet proven their physics on a real-world machine still face those “unknown unknowns,” she explained, whereas Inertia has been able to unveil and eliminate as many as anyone has yet found. The startup’s plant design is by no means an exact replica of NIF, however. For starters, its fusion targets will be twice as large, and its lasers roughly five times as powerful. The facility will also fire 10 shots per second, compared with NIF’s roughly one shot per week, using thousands of individually adjustable laser beams rather than NIF’s fixed 192. So as is nearly always the case when scaling up, some unknown unknowns likely remain.
But Kritcher is confident that the virtual shot will translate to real world performance — a level of certainty she admittedly hasn’t always had in her decades of nuclear engineering research and practice. In addition to her role at Inertia, Kritcher remains a senior scientist at Lawrence Livermore, where she has led the physics design for NIF’s fusion energy experiments since 2019.
A few years before the lab ultimately achieved breakeven in 2022 — more than a decade after its first attempts — Kritcher was beginning to doubt that they would ever get there. Then, in 2021, NIF reached a breakthrough that went largely unnoticed outside the ranks of dedicated fusion observers: It fired a shot that produced 70% as much fusion energy as the reaction consumed, bringing the facility within striking distance of net energy gain. And while it didn’t reach that threshold, the scientists said the experiment demonstrated ignition — a self-sustaining fusion burn.
The result gave Kritcher assurance that the lab was on the cusp of energy gain. Now, she feels a similar level of confidence that Inertia can translate its simulated 25x energy gain into a real world commercial facility. “The change that we made going from that first ignition result — the 0.7x gain to the [net energy] gain result — that’s the kind of change I feel like we’re making here,” she told me. “It’s working now, and we’re just making it bigger and better.”