You’re out of free articles.
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:

This transcript has been automatically generated.
Subscribe to “Shift Key” and find this episode on Apple Podcasts, Spotify, Amazon, or wherever you get your podcasts.
You can also add the show’s RSS feed to your podcast app to follow us directly.
Robinson Meyer:
Hello, it is Wednesday, June 24, and the Iran war has entered a new phase. The United States and Iran are reportedly conducting talks in Switzerland. We’re now in this period of so-called technical negotiations that are supposed to resolve the permanent status of the Strait of Hormuz and Iran’s nuclear program. So that’s, you know, small stuff, and I’m sure we’ll work it out. I want to talk in this episode, though, about what just happened. The past 110 days, give or take, of war between the U.S. and Iran, and the most important thing that I think we learned during that war. This show is about a phenomenon that I think has not gotten enough play compared to its enormous importance. And that is that China helped save the world from economic calamity. China, as you’ll hear in this episode, primarily buffeted the world from the economic impacts of Trump’s war of choice in Iran.
Robinson Meyer:
And the implications of that are really massive. So you’ll remember at the beginning of the war, a lot of energy experts, including those we had here on Shift Key, talked about how oil was going to hit $150 or $200 a barrel. Iran had just closed the Strait of Hormuz. It was the biggest supply shock to the oil market in history, and everyone expected the biggest price shock in the oil market in history to follow. But then it didn’t happen. Brent, the global oil benchmark, peaked around $115 a barrel on May 4. And of course, it shot up right after Iran closed the Strait of Hormuz, but it was very volatile. And it never hit $140 or $150 or $160 a barrel, which people were predicting. Gas prices obviously went up here in the U.S., but we never got $7 or $8 gas in most of the country. Europe was at one point forecast to run out of jet fuel. It never actually did that. So why? Why did we have this huge supply crisis in the oil market, but no comparative price crisis? Well, we know it has something to do with China. We know that starting around the same time that Iran closed the Strait of Hormuz, China significantly cut down its oil imports by something like 3 million to 5 million barrels a day. That is, for context, a huge amount of oil. It’s about three to five percent of global oil demand.
Robinson Meyer:
But we also know during this period, China didn’t seem to use less oil. And that means China was releasing oil. It was making 3 million to 5 million barrels a day of oil appear from somewhere. Where? How did it do that? Well, you’ll hear in this show, at least you’ll hear as best as we can figure it out. But the results mean a lot for the future of everything, actually. They mean a lot for the future of climate change and climate policy, for the future of the energy industry and oil in particular, for the future of the global economy and the modern geopolitical order. The ramifications of what China did are so massive that they’re mind-boggling to think about.
Robinson Meyer:
And luckily, we have a great guest to think about them with. Rory Johnston is an oil market researcher in Canada and the author of the Commodity Context newsletter. He’s someone who, as you know, we often have on the show to talk about changes in the oil market. And today on this show, we’re going to talk about what might have just happened, why it may have happened and what it means for the future. I’m going to ask you to stick with us because the beginning of this show is a little wonky. We talk about satellite data, we count some barrels, we talk about like, why we know how anything that’s happening in the global economy is actually happening. But at the end, we get somewhere really interesting and really important, I think, if you’re someone who works in the energy industry or cares about the energy industry or thinks about the future of climate policy and decarbonization and carbon emissions. So I’m Robinson Meyer, the founding executive editor of Heatmap News, and all that and more, it’s all coming up on Shift Key.
Robinson Meyer:
Roy Johnston, welcome to Shift Key.
Rory Johnston:
Thanks for having me back.
Robinson Meyer:
It’s great to have you back. I feel like you’re becoming our, I don’t know, is resident barrel counter like a flattering or offensive thing to say? Is that what you?
Rory Johnston:
So a lot of people say it pejoratively. I take barrel counter as like a mark of honor. Yeah, I can be actually the resident fossil guy on Shift Key.
Robinson Meyer:
I just appreciate, you know, always with the quantitative data, which speaking of which. So the Iran war began. Iran closed the Strait of Hormuz. We had you on the show back then, I believe. And you, like many energy analysts and us, we’re freaking out. Yep. Because the world lost access to, what, 10%, 30%?
Rory Johnston:
So to the barrel counter name, let’s count the barrels. So of the total initial hit of 20 million barrels a day, which is roughly 20% of global supply, we knew at the gate that we weren’t going to lose all of it. And I think as we talked about the podcast at the time, we had known offset capability. or a rerouting capability, the Saudi East-West pipeline, this Emirati pipeline to the Gulf of Oman that terminates at the port of Fujairah. And over that period, for much of it, we still had Iranian exports kind of chugging through the strait given the recent sanctions relief. But overall, the net impact that had durably impacted the market for the duration of this crisis was a 13 million barrel a day production shut up. So this is all the barrels that weren’t able to get rerouted, and they weren’t able to get exported out of the Gulf, so they were basically forcibly shut in. So the gross hit to the global supply was roughly 13 million barrels a day, give or take, which is by far the largest single shock on supply in the history of the market.
Robinson Meyer:
And so we all expected oil to go to approximately a bajillion dollars, give or take a bajillion dollars. And it didn’t. It peaked, what, in the $130s? And one of the big reasons for this is that China significantly cut its imports. In fact, I think the sense is the primary reason that oil was able, the oil, global oil market was able to weather such a huge supply shock is a number of countries tapped their strategic oil reserves, including the United States. It was the largest synchronized release of oil from IEA.
Rory Johnston:
Yeah, from the IEA member states, roughly 400 million barrels.
Robinson Meyer:
Yes, exactly. So there was this huge release of oil from the IEA kind of combined member states oil reserves. But China, which is not an IEA member state, also significantly reduced its oil imports and specifically reduced them from 11 million barrels a day as a kind of antebellum status quo ante to 7.8 million barrels a day in May. And so China was able to vaporize 3 million barrels a day of oil demand. I want to hear your take. But insofar as I understand it, this is the primary reason that oil never went to $200 or $300 or a bajillion dollars, was that China was able to go in and release not only crude, but presumably some refined fuels, too, from its strategic petroleum reserve and also do some magic on demand destruction. China was able to destroy a huge amount of its demand for oil. And this act of economic policymaking from China basically saved the world. And I would add Donald Trump from the biggest oil price shock ever, given that we were dealing with the biggest oil supply shock ever. And my question to you, Rory, is how did they do this?
Rory Johnston:
Yeah. And let’s just back up one second and kind of say, like, the reason we thought we were going to get the bajillion dollars, the $150 or I said, $200 a barrel we could get through this if it was sustained.
Robinson Meyer:
And I was at Sierra Week and I remember someone saying to me, gas in the U.S. could hit $7 a gallon, $8 a gallon. And once that happens, anything is possible politically.
Rory Johnston:
Exactly. And I think the reason we were worried about those levels and I thought we could get there is that if we’re drawing down by that, say, 13 million barrels, even netting for the fact that we had a surplus going into this, you were going to so rapidly approach tank bottoms of inventory that you’re going to need to forcibly destroy demand. What China did, and this is where we get to China, China was by far the single largest swing in that global balance. So, you know, of the IEA release of that 400 million barrels, really only what we’re counting is the actual pace of releases between the United States and Japan and a few others. Those only really ever reached, say, three-ish million barrels a day of total outflow at their peak. China’s implied swing is upwards of five million barrels a day. And just to give you a sense, so the numbers that you quote were from the official from the national, basically Chinese Customs Bureau. We’re watching more of the kind of satellite and tanker tracking data, which for the three months prior to the war, they were importing roughly 11.5 million barrels a day of crude.
Rory Johnston:
Via seaborne means. So doesn’t count the pipelines and everything else. So that could be a little wishy-washy there as well. But just to what we can see there, and that has fallen to, on average through June, 6 million barrels a day. So over 5 million barrels a day of delta there. Massive, massive, massive swing. And by far larger than any of the other, basically the equivalent of the entire shift of the Saudi East-West pipeline, China did through import demand destruction alone. I want to stress here, import demand destruction, because demand destruction, I think when people think about it, they think people aren’t driving, people aren’t flying, etc. And the strange thing about this is that as far as we can see, Chinese consumers are still driving. Trucks are still on the roads. Airplanes are still in the sky. All of these things that we would have normally associated with a demand contraction of the scale aren’t occurring. So let’s kind of go through the various steps here, because we’ve seen this kind of, let’s just say for round numbers, five million barrel a day contraction in from pre-war levels. We’ve seen refining run rates fall by, let’s say, three to three and a half million.
Robinson Meyer:
Is this in China?
Rory Johnston:
We’ve seen this in China. Yeah, everything. What we’ll talk about the next little while is just China. Refining run rates in China fell by 3 million, 3.5 million barrels a day. Over this period, right now, Chinese visible crude inventories continue to build for the first half of the crisis and have only now started coming down a little bit. The ones we can see, and this is an important distinction, the ones we can see, are roughly today standing where they were at the beginning of March. But the implied difference between the run rate change and the implied change in the imports is 1.5 million to 2 million barrels a day. So where did those other barrels come from?
Robinson Meyer:
In other words, the visible Chinese supply is where it was in March today.
Rory Johnston:
Yeah, the visible Chinese stocks. So these are the inventories. And I think let’s just dwell for a second what we mean by visible and why that’s important in this context. So China, unlike the United States, unlike Canada, and like most other kind of advanced Western countries, does not publish official data on, importantly in this context, either inventories or domestic demand.
Rory Johnston:
So with both of those, we are left to kind of infer from shadows and estimates to what’s actually going on inside China. So when we talk about visible crude stocks, what we’re talking about is the stockpiles of oil that are held in above ground storage tanks with floating roofs. And the floating roofs are important because we can use satellite imagery to infer how full those tanks are. Whether optically via like the size of the shadow, the lower they are, the bigger the shadow cast across the top of the tank, which is very cool stuff. And even more cool recently, you have like SAR satellites that can measure very specifically the difference in the kind of radar pinging off the top of the roof and the radar pinging off the top of basically the catwalk that goes around the top of the roof. So you can measure the distance between that. So of a total Chinese crude storage that we know of of say 1.1 billion barrels, give or take, those held in strategic underground stocks that we know of, very important here, are roughly 131 million barrels across six underground sites. Now, by definition, we cannot see these underground sites. They do not have floating roofs. The implication here is that if we know that supply is coming from somewhere else in the system, but we’re not drawing, or by we, I mean, China here is not drawing down visible commercial crude stocks, the kind of Occam’s Razor is that they’re drawing down by stocks we can’t see. These are the underground stocks.
Rory Johnston:
But the draws don’t end there. I mentioned China also doesn’t have official demand data.
Rory Johnston:
So what we are left with is deriving apparent demand data for China, which is essentially a domestic disappearance calculation. They do report, for instance, refining production. They report refining runs. They report refining production of, say, gasoline, diesel, jet fuel, etc. And you can net those refinery outputs with trade to get basically how much there should be in the economy that’s disappearing. Net it, of course, for those inventories we can’t see. Now, those run rates and those outputs, the biggest factor by far in the calculation of these apparent demand, those are down 3 million to 3.5 million barrels a day.
Rory Johnston:
That implies a demand-destructive event in China at the scale of what we saw at the beginning of 2020 during COVID Zero. That’s the scale of what we’re seeing. It would be equivalent to the largest contraction in Chinese history, at least modern history that we’re aware of. But strangely, if you, you know, obviously we knew about COVID Zero. There, you know, there were endless stories about COVID Zero at the time. We knew that they were like literally spraying bleach on the roads and like no one was going anywhere. And they’re like robots that tracked you and kept you in your house. Like, this isn’t happening now. So the assumption is that it’s just price alone that’s driving this kind of demand destruction. But here again is where it gets weird because Chinese domestic policy and regulations for fuel prices have capped or basically throttled the rate at which domestic petrol prices can rise. So while global gasoline diesel prices effectively doubled through this crisis.
Rory Johnston:
Prices of petrol in Beijing are only up by, at their peak, 30%. So it would be very strange to get a COVID Zero demand destructive event driven by only a 30% increase in prices. It doesn’t make sense. What it does make sense of those domestic product prices do drive the reduction in refining runs because all of a sudden your crude feedstock’s really expensive and your domestic market is really, really cheap. So your effective refining margin, your profitability has collapsed into deeply negative territory. Now, it’s important before I get too kind of heavy hand on the numbers to kind of say that there are little bits that we can theorize that they could actually destroy demand from a kind of a top-down approach. You know, a lot of Chinese oil demand is in the petrochemical sector.
Rory Johnston:
And you’ve seen some degree of capacity to either say, let’s throttle down Petchem run rates and just run off of inventories of intermediates, It’s still an inventory draw, but it’s not a strictly oil inventory draw. So sure, maybe you can also have feedstock diversification that you’ve seen natural gas feedstocks filling in potentially for oil feedstock.
Robinson Meyer:
So the whole story here is that they could take instead of taking oil or crude oil and turning it into plastics or other forms of chemicals, pharmaceuticals, they could be, first of all, just throttling the amount of chemicals they’re making, period. Or they could be taking natural gas or they could be taking, maybe this is where you’re going. But we also know that they’ve built up a really big coal to chemical sector. And they’ve been using that too.
Rory Johnston:
Exactly. And really at the end of the day, whether it’s oil, gas, coal, all fundamentally the same chemistry, just in different kind of physical forms. It’s all hydrocarbons all the way, you know, it’s all hydrocarbons all the way down, right? And I think that that does allow some flux, particularly in the chemical space where it’s like, it’s really, it’s trickier to say, make diesel out of coal. But various chemical precursors, yeah, I think that’s very, very plausible. Again, though, I think it’s unlikely that it’s five million barrels a day worth like that. We’re talking like that’s that’s more demand than Canada and Mexico combined as like a red off the top. Like we’re talking huge volumes.
Robinson Meyer:
Is it five or three that we’re trying to explain?
Rory Johnston:
I would say five because I would say from again, this the data we have in China so far only goes through May. And again, I tend to prefer independent references. So that’s where I go. I’m using Kpler data. It’s a tanker tracking company. They show that crude imports have fallen. Again, average of December, January, February was about 11.5 million barrels a day. And as of June, month date average, we’re down to 6.07. So almost halved. Yeah, there’s some wiggle room here. Maybe they were building some stocks prior. Like, again, there’s so much that we don’t know about China. There’s wiggle room around here. But I think the important thing is the scale cannot be explained. So something has to be releasing somewhere along the way. And people are like, well, Rory, haven’t you been following, and I’m sure you guys on Shift Key have been following this, that China has more than 50% sales penetration in new energy vehicles? Or we’ve seen EVs and natural gas-powered vehicles penetrating deeper into the truck fleet.
Robinson Meyer:
We talk about demand destruction, But there’s really two kinds of demand destruction, right? There’s at least I think of it this way in my head. Maybe these are not industry terms, but there’s like temporary demand destruction, which are all the things people do when gas gets expensive, which is you fly less, you carpool, you, you know, put different trips together on one time when you leave the house, right? There’s like temporary demand destruction where you are as consumers or as a country or as a government trying to reduce your short term purchases of liquid fuels. And then there’s permanent demand destruction, which is like you get really tired of having to think about all of that and manage it in your head. So you buy a Prius or a Tesla or an Ioniq and you switch to an EV or you as a Chinese consumer decide that instead of flying home to see your parents, you are going to take a slightly longer set of high-speed rail trips, right? And so anyway, this is just to say that there is this temporary versus permanent demand destruction dynamic. And indeed, one of the questions here, which I think you’re just about to answer for us, is like China has this incredibly successful electrified vehicle sector. How much of that can explain this 5 million barrel a day discrepancy?
Rory Johnston:
And the answer is maybe a little bit, but by far not all of it. Because the implication is, right, sales penetration doesn’t consume fuel. Vehicle stocks, the fleet composition consumes fuel. So yes, we have seen a massive penetration of EVs in China leading the world. But in terms of the overall total fleet on the ground, you’re still something in the realm of 10 to 1 internal combustion engines to new energy vehicles. So unless Beijing was hiding 400 million EVs in a warehouse somewhere, and they just were like, oh, Hormuz is closed. Release the EVs. Said in the Oprah release the bees voice for all that are curious.
Robinson Meyer:
Yes, everyone reached under there.
Rory Johnston:
But I think that unless that happened, and again, no one reported on it. I would expect Heatmap would have been reporting on the massive fleet of secret Chinese EVs that entered the system all of a sudden.
Robinson Meyer:
And I think one of the dynamics here, right, is that it’s not even like it was during COVID. During COVID, this was feasible, too. Like, we can talk to people in China. We know what the consumer gasoline price is in Beijing. We know how much people are on the roads. And so we know from talking to people in China, from the fact that you can fly to China, enter China, and leave China during the past 107, 108 days that the war happened. We know from all of that, that like there is not a COVID Zero level demand destruction event happening, nor has there been some massive demand change to the daily rhythms of life or some massive release of EVs, for instance, that would affect oil demand on the scale of 5 million barrels a day.
Rory Johnston:
Exactly. And again, I think so much of this is plausible over years, but not in two months. Right. I think that’s it’s a scale in the pace of change that would have absolutely been apparent in so many ways. Now, we do see some signs of what you’re talking about. We have seen, And for instance, through May, we did see a decrease from, you know, a year ago and particularly earlier this year, levels of flights in China. And we knew this was going to come because even outside of just spending and elasticity of demand, we saw that through April and early, you know, March and April, there was the concern about the actual shortage of jet fuel, and Chinese carriers canceled various routes and various flights. So that is just a kind of a wholesale kind of reduction there. And you did see a commensurate increase in, say, rail transit. So some of what you’re talking about did happen. But again, that’s only like a tiny piece of a tiny sector of the overall kind of base we’re talking about here.
Robinson Meyer:
Do we have any numerical estimates of how much behavioral change could have shaved off oil demand? In China?
Rory Johnston:
You know, it’s hard. I mean, it’s like, we can guess, but maybe the behavioral change was 25%, maybe. But I think that might even be too charitable. Because again, if you’re thinking about behavioral change, what drives behavioral change? Prices. And prices, as we were saying earlier, weren’t that much higher. Like there was a comment for a while that like maybe some Chinese households have an EV and internal combustion engine and higher prices mean they drive the EV more than the internal combustion engine. Okay, plausible. But again, is it enough of a price incentive to vastly kind of see a sea change in that relative usage, it just doesn’t seem likely. You have to assume a much higher demand of price elasticity in China than we’ve seen ever demonstrated before. So I think all of this is just, you know, there’s just a huge amount of oil here we’re talking about. I mean, just to give you a sense, running this estimate earlier just today before I jump from the call to give you a nice round number in terms of we’re using that 11 and a half million barrels a day and the three months pre-war as our average baseline, The reduction across months was 1.3 million barrels a day reduced in March, 3.3 million barrels a day reduced in April, then 4.7 million in May, and then 5.4 in June. And again, this is all based on Seabourn tanker imports.
Rory Johnston:
In total over that period, the cumulative total is somewhere in the ballpark of like 400 to 500 million barrels. That’s a lot of oil that you have to kind of make up for through this system. And that’s where we kind of come back to this assumption that like the Occam’s Razor here is that inventories have been drawn down, particularly on the product side.
Robinson Meyer:
So just to make sure I understand it, China, from very early March when the Strait of Hormuz is closed to sometime last week, eliminates in total an implied 400 million to 500 million barrels of oil demand. That is actually on the same order of magnitude as the IEA-organized release of... Oil from strategic petroleum reserves across 32 countries, including the U.S. So it’s very, very, very big. It’s like the same size as the largest supply intervention from Western governments ever in the oil market.
Rory Johnston:
And I should also say it’s actually larger than what we’ve seen released by the IA countries and collective because that was the total announced release. And that included some really weird stuff like Canada had a contribution to that. Canada does not have a strategic petroleum reserve. We have the oil sands. So what they ought to pledge was like, Oh, there will be some like heavier maintenance in the oil sands. I haven’t seen it. So like all of these numbers, it’s a little bit of like hand waviness. We’ve definitely seen a massive drawdown from the U.S. And we’ve definitely seen the largest ever drawdown from Japan. But European as well, we’ve seen maybe some, but like European SPRs are not, like the big pool of government out of oil that you’d expect stateside. They’re more like commercial stocks where the government tells you, you have to hold a certain amount in reserve for strategic purposes. And when they release it, they just say, you don’t need to hold that oil anymore. But theoretically, it’s many industry participants. They’re going to want to hold it in a period of scarcity. They just don’t have to hold it anymore. So it’s this weirdness where so I would actually say net net China has contributed more of a demand solve or more of a supply solve in this sense. If we assume it’s all SPR, more of a supply solve in the entirety of the Western nations combined.
Robinson Meyer:
And I want to add one more piece of context here, which is U.S. Authorized capacity for the American Strategic Petroleum Reserve. And this means as big as it could possibly, as big as Congress has said it could go. Who knows if, you know, the DOD or DOE has kind of some extra salt caves we haven’t heard about. But as big as the publicly disclosed authorized capacity for the U.S. Strategic Petroleum Reserve is 714 million barrels. And so the Chinese release, it’s basically if they had, it’s on the scale of if the U.S. released its entire Strategic Petroleum Reserve, more or less, you know, give or take a hundred or two million barrels. So what this means, right, is that China had a — and I want to talk about in a second whether we knew this was here, whether we knew they could do this. But first, I just want to make sure we actually put a button on this. China has strategic petroleum reserves, undisclosed, on the scale of at least half a billion barrels, or 400 million to 500 million barrels. These reserves presumably encompass both unrefined crude and products, and it has an ability to release them without, you know, kind of public fanfare, let’s say. It can tap these without making them visible.
Rory Johnston:
Bragging about it. I mean, they’re not bragging about it. Yes.
Robinson Meyer:
Yes. It could just quietly tap its half a billion barrel strategic petroleum reserve, which encompasses both refined products and crude, we guess, right? Because it has to, because otherwise, how can you explain the fact that refinery activity has gone down?
Rory Johnston:
Yep.
Robinson Meyer:
And it just quietly started doing this, and then it continued to do it for the past 107 days, 110 days. Is that the right lesson to draw from this?
Rory Johnston:
Yes. Okay. And I think there’s a couple things, right? Everything mechanically is exactly how it went down. One big question. So we’ve talked about how. And we’ll talk about in a second what it means. We haven’t really talked about why yet. And I think this is another massive question. Because when we talked months ago, and you would ask, did we know China had all this oil? The answer is generally yes. We didn’t know the exact composition. We didn’t know exactly where it was. We didn’t know the breakdown or whatever. But for instance, we knew that China had over a billion barrels of visible crude inventories?
Robinson Meyer:
Well, I was going to ask this because basically one of the plot lines in the oil market over the past like two years has been that China, but basically there was some quantum of oil on the global market that was clearly being purchased in China that was not in the Chinese public data that sure looked like a strategic petroleum ramp up, right, that they were stockpiling oil. And you could see this in like the global supply and demand data, it actually kind of kept global oil prices a little elevated. It was good for producers, so to speak. But there were two assumptions here. I mean, I think the two assumptions were like, either one, they are building up fuel so that they have enough domestic fuel reserves so that they could invade Taiwan. Number two, that if they did invade Taiwan or if there was some crisis over Taiwan in the future, number two would be the less bellicose assumption or the less hawkish assumption. If China, there was some crisis over Taiwan status with the United States and the U.S. navy basically cut China off from seaborne fuel imports, then China was stockpiling these liquid fuels so that if that eventuality were to occur, it would have some strategic options and would be able to sustain its economy for some period of time with its domestic reserves. We knew that there was this buildup. Did we know the buildup was this big?
Rory Johnston:
No, not really. So we knew that there was a buildup in crude. We suspected there was a buildup in products. And back in 2023, I wrote a piece called “Chinese Oil Demand Doubts.” And in 2023, coming out of COVID Zero in the prior year in 2022, China posted the strongest year on year demand growth of any country in the oil market’s history. I believe it was about 1.7 million barrels a day year on year growth in Chinese demand, again, from a weak base. But that was 2022 was the first annual average demand contraction on record in China, basically in 30-plus years, modern China. And the following year was the largest growth ever. At the time, the rest of the Chinese economy didn’t look that hot. I mean, the same way that we’re tracking mobility now, like it just didn’t seem that good coming out of COVID Zero at the beginning. So not good enough to post all time high demand. But what I said at the time was when we were talking about how we create, how we estimate apparent demand, a big assumption there is that net-net, there is no material kind of bias in terms of stock building or stock drawing. That net-net, because we can’t see them, those net out. But given that we can’t see it, strategic stock building of gasoline, diesel, jet fuel would show up in these calculations as demand.
Rory Johnston:
Now, in 2023, I wrote exactly what you said, which is the assumption here is, one, China loves stockpiling raw commodities, period, end of sentence. Prior to oil, I covered a lot of metals markets. And you have the Strategic Metals Bureau in China that basically, you know, the State Metals Bureau, they do the same thing. They will just go in and swing copper or zinc or nickel supply by like multiple percentage points in the global market. This is the first time we’ve seen that level of swing in oil. And I think that’s a big conclusion that we can take from this. But yeah, so that basically the assumption was that it would be some, you know, either that kind of propensity towards stock building, and trying to secure up and shore up domestic supplies or explicitly as a kind of build up hedge for an invasion of Taiwan and the more hawkish interpretation. And at that time as well, it’s important to remember that that was when we saw Beijing increasingly saber rattling towards Taiwan. We saw, you know, them buzzing Taiwanese airspace. We saw, you know, Chinese naval drills off the coast of Taiwan. There was a lot of people talking about like, is this the moment? Is it actually going to happen? And I mean, there was even I think there was an Economist article at the time talking about how China was stockpiling all this stuff. What are they doing with it?
Robinson Meyer:
Around when Nancy Pelosi visited Taiwan. Yes, it was. And there was a sense that, you know, if the U.S. mishandled this moment, that the two countries were as close to war over Taiwan status as they’ve been in a long time.
Rory Johnston:
Yeah, exactly. So I think that that was the initial thought. Now, why are they doing it now? Because obviously they’re not harassing Taiwan at the moment. The world has much bigger problems. So I think that with the Strait of Hormuz closed, the assumption was that, Okay, I thought that Beijing would not help. I thought that particularly coming out of that fairly, you know, cold, let’s call it, visit between the Trump administration and China a couple months ago, it did not seem especially successful. It did not seem like Beijing was going to help actively resolve what was going on in the Strait of Hormuz. So we kind of thought that they were not going to do this because doing this helps the Trump administration. It released massive pressure on the Trump administration.
Robinson Meyer:
Basically, right. What it means is that China absorbed with its strategic stock. In some ways, it’s the biggest what it means of all. China absorbed with its strategic stockpiles the primary hit to the global economy caused by Trump’s war of choice on Iran.
Rory Johnston:
Correct. And if we go back a couple of minutes ago to where we’re talking about the reason they built this up in the first place, because they are paranoid about energy security. So the question is, why would they single handedly take the bullet for all of Asia, Europe, everywhere else in the world?
Rory Johnston:
While diminishing and eroding that energy security blanket that they had so dutifully built up over years.
Rory Johnston:
It doesn’t make a lot of sense. So I think there’s two explanations that I’m working with. There’s three explanations. There’s the completely, you know, innocuous, like kind of like business as usual. So let’s go for that one first. Let’s assume that everything we’ve talked about, I’m wrong on the specifics and that you actually did have that much potential flexibility in the Chinese petrochemical space, that there were, you know, every one of those things I mentioned as potential offsets did happen and were about double as large as like, as I kind of bank them to be. Maybe, maybe. But I think the more likely is one of these more active choices I’ll mention. Now, the one is like, kind of, call it kind of like Beijing altruism. And then there’s like a very hawkish one. So the Beijing altruism one is.
Rory Johnston:
Okay, we know that Beijing is looking to diversify away from the United States, to pivot away from the U.S.-China relationship, to try and buttress economic trade linkages with everywhere else. The two other areas that are most obvious, East Asia and Europe, but the two areas that are going to hit hardest by the Hormuz shock. So in one telling, there’s an argument that China, it was not in Beijing’s interests to let, all the rest of the global economy falter so acutely at a moment when, as we’ve discussed, North America was going to be the most secure region given, shale production, given Canadian oil sands, given all this stuff. We were going to feel prices, but we were not going to feel the shortages in the same way. So again, the altruistic argument is that Beijing looks around the world and says.
Rory Johnston:
Trump has abandoned you. You know, Big Brother Beijing is here to help. So we’re going to backstop it all. The challenge with this argument is going back to they haven’t said anything about it. So you would, again, if they were doing this, if they were trying to make a point of offsetting, you know, the consequences of reckless American, you know, adventurism in the strait, they’d probably say something pretty sassily at that. But they didn’t. So then let’s move to the kind of more like, I’ll put my tinfoil hat on for a second And this is like the hawkish, like more concerning one, which is I mentioned this trip that the Trump administration took to Beijing. All external signs, all reporting indicate that it was not a particularly successful trip. Nothing blockbuster. Maybe it was like, you know, smiles and like waves, you know, waves at the crowd, but nothing, no trade breakthroughs, no breakthroughs on, you know, Beijing sending the Navy in to help reopen Hormuz. But maybe on the sidelines, they agreed to something else. They agreed to some kind of arrangement where Beijing stepped in to help the Trump administration with its gargantuan oil reserves. And again, we know that they theoretically have in stock, but this is the way we knew they were going to work or not. We knew that they had a lot of oil and they weren’t, releasing it immediately.
Rory Johnston:
So why would they do that? Why would Beijing help America in this case? And then we go back to kind of our interpretations of like the Donroe Doctrine, which is the idea that Trump was looking to withdraw from global kind of hegemonic, you know, oversight. And it was going to seed the world into these basically tranches controlled by regional powers that the United States had the Americas, Russia had Eurasia and Europe, and China had all of Asia. So what else was happening during this time? Well, there was a lot of military equipment destroyed in the Middle East during this period by Iranian attacks. And what we saw was that the U.S. military was pulling out a lot of heavy military kit that has historically resided in Asia to, say, buttress Taiwanese defenses. And they’re pulling them back over to the Middle East. I think the most concerning interpretation is that they basically trade Hormuz for, you know, Asian oversight and kind of attempted influence. I think that’s a very concerning potential.
Robinson Meyer:
Wouldn’t we see more signs of that publicly other than this kind of quiet, unheralded strategic petroleum release? Like, wouldn’t China be in this moment kind of notifying the other governments in Asia that they were now under its hegemonic authority as opposed to the United States?
Rory Johnston:
Out of the three options I discussed, the one where you would be least likely to talk about it publicly, I think, is this more clandestine. Because, again, the crisis is still ongoing. We still don’t know how long Beijing is going to keep this up. And I think this is this question of like, again, I don’t think any of these perfectly fit, which is why I think it remains a mystery as to why China did this. I’m mostly in kind of camp, you know, two or three that this it’s either trying to save the regional market or it’s something more nefarious. Because, again, I think that all the other explanations just don’t account for the scale and pace of the change we saw. It feels more discretionary policy than it feels like a natural market reaction.
Robinson Meyer:
Do we know how long they could have done this? Because crucially, as part of this dynamic, you know, if China was drawing down unseen strategic product reserves, Those reserves physically exist somewhere on the earth. They cannot be drawn down forever. And although we experience their being brought onto the global market as this kind of lack of price action, that has a duration. So, like, do we know how long they could have done this? Because looking at other global petroleum reserves, indeed, what seems to have driven part of the Trump administration’s decision making is that everyone’s stockpiles were getting drawn down, including like visible commercial, public data, non-strategic, just corporate stockpiles were like at very low levels. Everyone was kind of about to hit the bottom of their tank. If that had happened, maybe oil would have gone haywire globally or in certain regions. Was China like also close and we don’t know?
Rory Johnston:
It could have been, I think. And just to kind of reflect on the specific comment you’re talking about. So at the G7 and all of these speeches as Trump was kind of like.
Rory Johnston:
You know, championing this MOU, he’s like, well, there would have been bedlam. You don’t understand. Like we were four weeks away from hitting like tank bottoms. That would have been really bad. So one in the current system, yeah, four more weeks would have brought us even lower on commercial stocks. The U.S. SPR could have gone for 40 more weeks at that current pace. Like, I mean, this reference to reserves, I think a lot of people were thinking strategic. Those could have kept going. What was absolutely going to happen had this gone, as this continues to go longer, is we continue to draw down commercial stocks, you know, by the fastest pace on record. And we started this at very, very high levels. And now we are at very, very low levels and we’re still drawing at record pace. So yeah, I think the kind, the charitable interpretation is that the Trump administration actually has decent advisors in the space. And they were like, enough’s enough. Don’t pay attention to the price. We’re literally about to run out of oil. Maybe the other, I know going into the kind of tinfoil hatty thing here, and again, it’s the best we have, is like maybe Beijing gave him a bit of a timer on how long they would do this. I was surprised. I wasn’t surprised that this is how we got to an MOU. This is basically the MOU I thought he would sign. But this is the MOU I thought he would sign with crude at $150, not with crude at 80. It felt much more forced. He felt like he was under much more duress than markets were putting him in, much more pressure than they were putting on him. So there has to be something else that drove him because over the last two and a half weeks.
Rory Johnston:
The pace of the abrupt change in the way he was talking about it was like palpable. Like there was a very, very stark shift. It went from we’re fine, we’re fine, don’t worry, just trust us, to if we didn’t stop this, there would have been economic cataclysm. That’s a pretty, you know, wild swing in the span of like two weeks. It’s hard to make sense of any of the principal’s behavior in this crisis because, again, he was talking, the tone was like it was $150 crude. But we were we were sub 90 at that stage.
Robinson Meyer:
Right. I mean, what’s hard here is that the decision to go to war hasn’t made sense. The decision to end the war hasn’t made sense. We’re ending a dumb war of choice, basically on Iran’s terms. I mean, the whole thing is with none of the main issues that allegedly began the war resolved. In fact, all of them, you know, kick to this 60-day technical negotiation, technical, quote unquote. But let me ask an interpretive question here, which is like, isn’t there a non-nefarious, non-altruistic answer here for this kind of behavior, which is that we know the Chinese economy is doing fine. It’s not doing great. It’s consumer sentiment is pretty weak. Many households are still basically climbing their way out of having to write down their real estate investments from a few years ago. And we know that Chinese policymakers at this point have internalized that the problems with their economy are around this question of consumer demand versus investment. And isn’t it possible that Chinese policymakers just saw this massive energy supply shock coming down the turnpike and said, Our economy is not strong enough to deal with this. We know that they value energy security. They also value economic stability. And we don’t know, but it does seem like maybe they’ve shifted.
Robinson Meyer:
They feel like they can cut some kind of deal with the Trump administration. They like the way the Trump administration is referring to them as a peer. It does seem like their strategy on Taiwan has shifted a little bit from extremely bellicose to continue salami slicing Taiwan status and get some concessions out of the Trump administration about what the U.S. would do. Like, which to be clear, Donald Trump has partially already given them by referring to Taiwan status in ways that I think previous American presidents haven’t. Isn’t it possible that they just said, we simply don’t want this economic bomb to hit our economy and we’re going to do what we can to preserve our own economic stability. We don’t really care about what this signaled the sense of the rest of the world. We care about our consumers and preserving the strength of our economy. The feeling internally is that we’re not going to, there’s probably not going to be a war, inshallah, in the next year. And so we can just twist the knobs on this thing and prevent our own country from, you know, getting fed into the economic chipper, so to speak.
Rory Johnston:
Potentially. But let me problematize that in a couple of different ways. Because I think, while that could have been true when prices were skyrocketing through March and April, It certainly didn’t feel true as prices were collapsing into May and June. And during that period, Chinese imports continued to fall deeper at the period when it wasn’t happening. And I also think that you had this moment again of if that was the case. So here’s something that’s interesting. So the import collapse that I mentioned and the refining run collapse that I mentioned was... China seems to be holding refining runs higher than they would otherwise economically be otherwise, because if refining runs were deeply negative because of this policy change, why are Chinese imports not down 80 percent? Why aren’t they down more? Like, there’s also this question of, like, something’s telling these refiners to keep operating at some level because they have to keep going, maybe because they can’t draw down that entire pace of products on the other side. And again, we come back to one of pace of if that was the case, I think we would have seen more signs that you saw a kind of a heavy top down change because you would have seen more behavior change in that case. I think you would have seen way less, you know, transit. You’ve seen that China is very capable of locking down the economy.
Robinson Meyer:
Is China’s control over its tools of economic policy making like that fine tuned? Because I think like during COVID, right, there’s one story where it’s like we know China can shut down. You know, the country in COVID, we saw it. But the other story of COVID is that China basically has this market economy that operates on through this combination of provincial competition and top-down signals. And the top-down signals tend to get interpreted in this like very absolute way. So it’s like, we know that the economic policymakers can twist from two to 11, but they can’t really, they don’t like always know where seven is. I guess I’m trying to extend some faith here but like is it possible that they just like meant to twist to 7 and it got stuck in 11 and the signal is like damn the torpedoes full speed ahead, and they just start holding it there?
Rory Johnston:
Maybe. And I should say, this is a mystery to me. So I’m very open to other interpretations. I think, though, if that was the case, I think we would have seen buying return faster. I think that we’ve seen China building stocks at prices higher than they are right now. And they’re not even going back to pre-war norms of runways. We’ve also seen very, very early signs that Chinese import buying is picking up now that we’re starting to see more ships going through Hormuz. Now particularly seeing more Iranian ships going through Hormuz, which again speaks to a level of kind of waiting for the moment, which feels more, fine-tuned and discretionary than like a big kind of heavy mallet of, you know, that it’s stuck at 11.
Rory Johnston:
One thing I think we should talk about is what it means for the future.
Rory Johnston:
Because there are pretty massive consequences inherent in what we’re talking about. Bears the fact that, one, likely the implications that Chinese oil demand was weaker going into this than we had appreciated. So that means the glut surplus supply going into this was larger than we had appreciated. That’s point one. Point two is that we now see that China can swing massively and in rapid fashion, in the case of a massive spike. So it has the capacity and much more apparent willingness and execution ability than the West to stave off crises of fossil fuel prices. if, say, this happens again or it doesn’t end or whatever. And I think in anyone’s view of the oil market, part of your distribution is like a fat tail of like a $150, $200 oil price spike. And if all of a sudden that’s been like tamped down, That changes the kind of, you know, average of that distribution pretty notably.
Robinson Meyer:
We have this concept in oil of swing producers, right? The reason that OPEC Plus and Saudi and the UAE to a lesser extent can shift the global price of oil is because they have these very swingy production apparatuses, right? Very swingy reserves where they can rapidly scale up or rapidly scale down the amount of oil they’re sending into global markets. And because they have such power over the margin, they have a lot of control over the global price of oil. One thing we see in mineral markets, though, is that swing consumption really matters, is that China for the past 20 years has been able to set global commodity prices by the fact that it’s buying a lot or not buying a lot of a mineral. Do we need to start thinking in the global oil market in terms of China has an ability to set oil demand at the margin, perhaps already has been setting oil demand at the margin and therefore has a degree of market power that is? I don’t know, maybe isn’t equivalent to Saudi or the Permian, if we ever wanted to use the Permian in that way, but is like a very potent force in global economic policymaking.
Rory Johnston:
I’d go even further than that. I would say in terms of like the type of swing we’re talking about, we’re talking like even like five million barrels a day. That’s the collective cut of OPEC plus that it was unwinding over the course of the past couple of years. We’re talking not just Saudi, we’re talking like it can have the same swing demand impulse as all of OPEC together, which is like staggering and certainly more than has been demonstrated the capacity of the Western nations. So then we start talking about, yes, the state mails bureau was doing this with various commodities before there. It seems like they’re now doing that with oil as well. I am sure you guys talk all the time on this podcast about how China has worked to dominate critical minerals, you know, energy transition industries, et cetera, et cetera. In some ways, you know, people were like, well, at least they don’t control the fossil fuel sector. And I was like, well, maybe they actually do have a lot more influence in this sector than we had appreciated. And again, even comparing to the Permian or whatever, what makes OPEC so powerful is that it’s not necessarily a market driven thing. It’s discretionary. It’s a policy choice.
Rory Johnston:
Trump, as we have clearly seen, cannot make the Permian drill baby drill. Only economics and market incentives are going to do that. This, again, as far as we can see, the Occam’s razor is that this was a policy choice, to decrease import demand rather than a purely market one. And I think that, again, is like a very, very powerful thing if taken to its like logical extreme.
Robinson Meyer:
Is this the most important thing we learned in the Iran war?
Rory Johnston:
Yes, by far. I think that I think there’s other things like, for instance, I think that we’ve proven that the Trump administration and Trump himself can have a call it a soft manipulative capacity with jawboning, with spiking volatility and pushing people out of the market. China alone wouldn’t have stopped, I don’t think, the melt up that we saw through or rested the melt up we saw through March and April. But I don’t think the jawboning alone would have worked to do that without the slack that China injected. I think together it proved to be an extraordinarily potent combination. And then all of a sudden, just to tack this on to the end, we also have the fact that the IEA is now forecasting that once this thing ends, we’re going back to the world of mega glut. So maybe our historical references for how the market interprets low stocks or low inventories is also different in this moment because of that upcoming glut.
Robinson Meyer:
If Chinese, let’s say, real demand, I don’t know what the terms to use here are, but let’s say that real Chinese demand was even lower over the past few years than we thought it was because China was building up these massive strategic stockpiles. Does that mean that the real peak of liquid fuel consumption in the global economy has already happened?
Rory Johnston:
I don’t know if it’s already happened because I think that China is not the only source of demand growth we’ve seen over the past couple of years. It’s obviously a massive piece of that. But you’ve actually seen through COVID, Chinese demand has been really flattish since this period. So maybe Chinese liquid demand has peaked earlier, but I don’t know if yet. I think it might be too hard to say overall demand has peaked yet. But I do think, you know, absolutely, this is proof that you have a lot more swing in Chinese demand. And I would differentiate by demand is consumption plus strategic stock building. But to your point, I think consumption is almost certainly lower than we had thought going into this. So overall, we now know that Chinese consumption was likely lower and China’s swing demand is much higher. Or the capacity for swing demand is much higher than we would have appreciated.
Robinson Meyer:
It’s so interesting because it basically means that under a flat demand signal, consumption has risen and fallen. And we don’t know exactly when it happened, but we know it happened under there, which would be very good news to bring it back to the topic of shift key for the climate. The issue is if the other big lesson of this crisis for China, and by the way, for India, for the rest of Asia, is that it’s really good to be able to switch fuels in your petrochemical sector and you want to build out a lot of coal to chemical plants, that would be very, very bad for the climate because while you can change whether you make chemicals from oil or natural gas or coal and it doesn’t really matter for the end product, it actually does matter a lot for the climate whether you’re making chemicals with oil or gas or coal. And so anyway, lots to think about. Rory Johnson, it’s so great to have you here. This was a great conversation. Thanks so much for joining us as always. I learned so much.
Rory Johnston:
Thanks for having me, Rob.
Robinson Meyer:
And that will do it for us today. Thank you so much for sticking around till the end. Before we get to the credits, I just want to say, I don’t know if you subscribe to Heatmap Daily. It’s Heatmap’s newsletter. It goes out every afternoon or evening, Eastern U.S. time. But lately, we’ve been having some fun with it. I have been writing that newsletter every day. And it really is me, by the way. I’ve added a lot of writing to my weekly workload. And in that newsletter, I share an observation or a piece of analysis or some recent reporting that I’ve been thinking about. It’s like an email from me to you every evening. I really enjoy writing it. It’s frankly been a blast and it’s kind of the peer to Heatmap’s morning newsletter, Heatmap AM, which is written by my colleague Alexander Kaufman. So what I want you to do is if you don’t subscribe to Heatmap Daily, but you do listen to this show, and in particular, if you’ve listened to this show all the way to the end, you should go subscribe to Heatmap Daily. Like I am writing this thing for people like you and I would like you to subscribe to this newsletter. We will stick the link in the show notes. You can also find it at heatmap.news. But please, please do come and subscribe. It’s really fun. It’s free, by the way. You don’t have to be a Heatmap paid subscriber to read the newsletter. But I think you’ll enjoy it. I encourage you. In fact, I ask you to subscribe.
Robinson Meyer:
We will be back next week. I’m relatively sure with a new episode of Shift Key. We might, might have something on Friday, but I think it’s going to be next week. Until then, Shift Key is a production of Heatmap News. Our editors are Jillian Goodman and Nico Lauricella. Multimedia editing and audio engineering is by Jacob Lambert and by Nick Woodbury. Our music is by Adam Kromelow. Thanks so much for listening, we will see you next week.
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Current conditions: A Pineapple Express — the powerful atmospheric river that hits the West Coast, not the marijuana strain — could pummel the Southwest with heavy rain on Halloween • The remnants of Typhoon Champi are driving a severe storm in the Bering Sea, with four-foot waves lapping on Alaska’s shore • Despite India’s evacuation of nearly 200,000 people, Cyclone Arnab killed at least nine and destroyed tens of thousands of acres of crops in Andhra Pradesh.
The Federal Reserve voted Wednesday to keep benchmark interest rates steady despite last month’s spike in inflation statistics. In a post-meeting statement, the Federal Open Market Committee said it had decided to keep the federal funds target range between 3.75% and 4%, maintaining the central bank’s quarter percentage-point hike from last month. “Inflation remains elevated,” the statement cautioned. “The accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee’s 2% goal.”
For clean energy developers, whose projects’ upfront costs make them sensitive to the price of borrowing money, a hold is better than a hike. But a reduction is better than a hold.
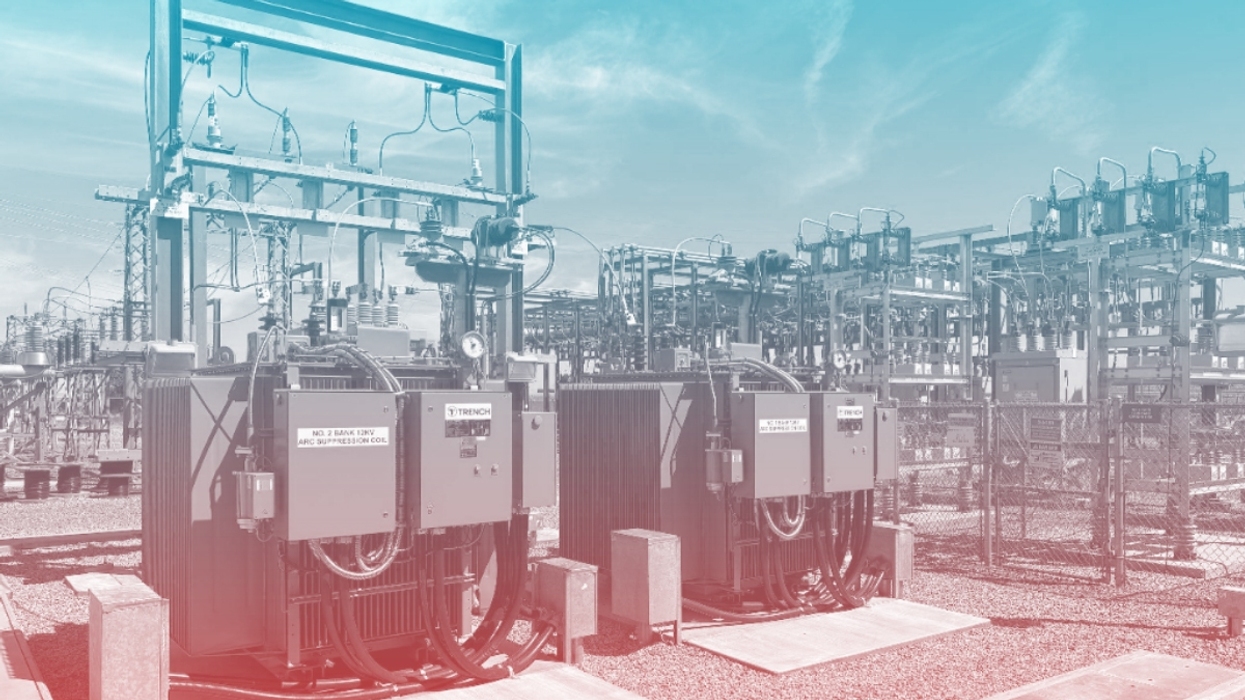
GE Vernova’s gas turbine business is going gangbusters as data centers drive demand for new generators. Its nuclear-focused joint venture with the Japanese industrial giant Hitachi, meanwhile, is making real progress toward building out an order book for its 300-megawatt small modular reactor, the BWRX-300. Now the General Electric spinout is making a big bet on the future of the transmission buildout. On Wednesday, the company announced a deal to pay $9 billion for Trench Group, a global manufacturer of high-voltage transmission equipment and grid components. The deal is expected to close at the end of next year. “Trench’s differentiated high-voltage grid technology, strong execution, and deep customer relationships are key enablers of the modernized, resilient grid required to keep pace with the electricity supercycle,” GE Vernova CEO Scott Strazik said in a press release.
It’s far from the only company betting on future grid construction. Hitachi announced a $1 billion investment into a U.S. transformer factory last year. Meanwhile, a former Tesla executive just launched a startup called Heron Power aiming to make transformers specifically designed to patch more data centers and renewables onto the grid. There’s plenty of money to go around: As you may recall, the Department of Energy has in recent weeks pumped billions of dollars into upgrading the U.S. power grid.
More than 40 clean tech startups urged both parties in Congress to pass permitting reform legislation before the session ends. In a letter published Thursday morning and shared exclusively with me for this newsletter, the companies said the Bipartisan American Affordability and Jobs Act “helps innovators spend more time building and less time waiting.” Signatories included geothermal heavyweights Fervo Energy, Quaise, and Zanskar; carbon removal company Heirloom, and fusion giants Commonwealth Fusion Systems and Realta. The bill, they continued, “restores confidence that American projects can move from concept to construction on predictable timelines.”
The National Association for the Advancement of Colored People, on the other hand, came out with its own statement warning lawmakers against the bill. In its view, BAAJA would “lock in dirty energy for decades” and make it “harder for people to show they are harmed by pollution.” The group will undoubtedly find sympathetic audiences at the upper rungs of the Democratic Party. In remarks my colleague Jael Holzman obtained, John Podesta, the Biden White House’s senior climate policy advisor, said at a conference last week that he worried the bill could hand Trump “a loaded Howitzer.”
Sign up to receive Heatmap AM in your inbox every morning:
Man bites dog: New York City might just have something to learn from Connecticut. In 2011, New York’s neighbor established the nation’s first green bank. As of this year, the agency has directed more than $3 billion toward things like developing solar and storage systems on public housing. “What we saw in Connecticut was a way to get community-scale renewable projects built that markets alone were not delivering,” Jason Kowalski, the executive director of the Public Renewables Project, told me. “With New York City, similarly, we’re looking to fill market gaps.” In a new report released Wednesday, his group — along with fellow left-leaning energy policy advocates Public Power NY and the Climate & Community Institute — proposed that New York City create its own green bank, modeled on Connecticut’s experiment. “We’re not thinking about public versus private,” Kowalski added. “We’re thinking of public versus nothing. We’re targeting places where nothing is getting built. This is a mechanism for building revenue-positive projects that are not being built because of the transaction costs or because there is no planning function that’s brought in to plan at any scale.” The proposal could find sympathetic eyes in Mayor Zohran Mamdani’s administration. The democratic socialist has embraced venturing where, since the 1990s, government has rarely gone. City Hall brokered a deal two weeks ago to chip in $30 million for New York University’s next-generation computing lab in exchange for 15% of the proceeds from any technology the facility develops and sells. As you may recall, I called the agreement “New Dealism for quantum computing.”
Public financiers could also come in handy as cities undertake the costly renovations and infrastructure upgrades needed to survive in a hotter, more meteorologically chaotic world. The European Commission this week unveiled new climate rules requiring governments to establish who is responsible for protecting citizens from climate disasters, Euronews reported. Brussels wants major cities to prepare for as much as 3 degrees Celsius of warming above pre-industrial norms. That’s more than double the warming we are already getting a taste of from El Niño.
Cement produces roughly 8% of global emissions of heat-trapping carbon dioxide — four times the output of airplanes. Cutting emissions across the wider economy requires building a lot of stuff. Paradoxically, that means using a lot more cement, adding to emissions. But a growing suite of startups is rolling out new technological approaches to make low-carbon cement. One of them just announced a major deal with Meta. The Facebook owner agreed to buy 200,000 tons of San Jose-based Fortera’s low-carbon cement. “Agreements of this scale and duration are what unlock financing and move projects from plans to production,” Fortera CEO Ryan Gilliam said in a statement. “They also show the market that low-carbon cement is a product that buyers are serious about and planning around for years to come.” The clean cement sector has been, as my colleague Katie Brigham wrote, riding the artificial intelligence wave.

Antimony is a lustrous, silvery-gray metalloid. It’s needed for solar panel glass and all kinds of batteries. And the U.S. overwhelmingly relies on imports of it from China and Tajikistan. Maybe not for long, Mining Technology hinted. On Wednesday, Alaska’s Department of Natural Resource gave its final approvals to the startup Nova Minerals. The project, funded with nearly $45 million from the Department of Defense, aims to begin production next year.
This transcript has been automatically generated.
Subscribe to “Shift Key” and find this episode on Apple Podcasts, Spotify, Amazon, YouTube, or wherever you get your podcasts.
You can also add the show’s RSS feed to your podcast app to follow us directly.
Robinson Meyer:
Hello, it's Thursday, October 29. And as you know, the biggest story in U.S. Energy policy right now, at least other than the upcoming midterm elections, is that Congress will take up bipartisan permitting reform next month. This was a legislative proposal advanced in September by four senators called the Bipartisan American Affordability and Jobs Act. And if you read Heatmap or you look at social media, or even sometimes if you look at Instagram Reels, you will see that this package is very controversial. American environmentalists, climate activists, clean energy folks, they have been arguing about this bill essentially constantly since it came out. That's partially because it would just do a lot of different things: It would encourage the expansion of the power grid. It would change environmental review laws. It would make it easier to build clean energy and also pipelines. And it would make it harder for presidents to revoke permits from some energy projects. There's a lot of different views about those provisions and how they would all work together.
But just about everyone involved agrees the bill's power grid policies are really, really good. The Natural Resources Defense Council described this section as one of the bill's, quote, “green flags,” as opposed to what it saw as its red flags. And even John Podesta, the former Biden climate advisor who's been more critical of the proposal, said the grid section was, quote, “pretty strong,” unquote, and told our reporter that this section was actually worth passing the bill over if negotiators could fix some of his other criticisms.
All of this has had an interesting effect on what we cover, both at Heatmap and I think more broadly. And that's because the media — we love to cover conflict. That's not just because conflict or disagreement is more interesting, although I think often it is, but also because it lets us as journalists be useful. It can actually be helpful for reporters or an informed person to poke around a disputed question, try to learn new information, and then try to figure out what's true. That's really one of our jobs as journalists. What all of that means, though, is that when there's less conflict over something, we don't cover it as much, even when it's really, really important.
And that's happening, I think, with this power grid section, which will be one of the most important parts of the law if it passes — but which nobody has really talked about because nobody disagrees about it very much. So today I want to talk to someone who knows a lot about this package, knows a lot about this particular area of the law, and is really jazzed about the changes that this bill would make.
David Pomerantz is executive director of the Energy and Policy Institute, a watchdog and research group that investigates fossil fuel and monopoly utility lobbying. He's been at the Institute for more than 10 years, but his background is in climate activism. He was previously at Greenpeace for eight years, where he rose to be a senior climate campaigner. Dave and I discuss what this bill would do and how it would take on the power of monopoly utilities. We talk about why a bill like this could only really pass now in recent U.S. political history. And we also discuss why utilities are, at least in Dave's view, one of the biggest enemies of the energy transition, even though utilities are in charge of the electricity system and at least in theory generating more electricity is what we want to do if we want to decarbonize the economy. It was a really interesting conversation. I learned a lot.
I'm Robinson Meyer, the founding executive editor of Heatmap News, and it's all coming up on ShiftKey. David Pomerantz, welcome to Shift Key.
David Pomerantz:
Thanks so much for having me.
Robinson Meyer:
It's funny. I mean, we were talking about this right before we started, but we have known each other for a long time. I feel like I read Energy and Policy Institute work all the time, but we've never had you on the show. So it's very exciting to have you finally here on Shift Key.
David Pomerantz:
Well, I'm very grateful for the invitation. I am an avid listener and so honored to be here with you. Thanks, Robinson.
Robinson Meyer:
I think for those of us who do anything around electricity, the Energy and Policy Institute is a very familiar name. But it might not be a name that everyone in Climate World, so to speak, or climate and energy world is familiar with. Could you just give us a brief intro to your work and what the Institute's work does?
David Pomerantz:
Yes, happily. So the Energy and Policy Institute, or EPI, is a utility watchdog organization. So we do a mixture of investigative work and analysis and communications. What we're investigating and trying to document is the harms posed by monopoly utility companies to ratepayers and to the transition from fossil fuels to clean energy. So most of the people, my colleagues who I work with, are kind of climate people. We are motivated by trying to hasten the transition away from fossil fuels. With that said, as we've been doing this work, or at least I've been doing it for the last decade, and getting more and more exposure to how utilities are set up and organized and what incentives they have and how they behave, I think our purview has gotten a bit broader than that. And nowadays, we're sort of — as much as we are interested in utility reform in so much as it affects the transition to clean energy, we're also just generally interested in how utilities act toward their customers and what can be done about that.
Robinson Meyer:
I feel like this is not an atypical pattern, where people get into a policy area because they care about decarbonization and climate change. And then once they get into it, they're like, oh, my gosh, this thing is really screwed up. I feel like this has happened to me to some degree with manufacturing and industrial policy in the U.S. I'm like, oh, my gosh, we've got to get a handle on this kind of for decarbonization reasons. But also just generally, often when you look closer at something that you care about for some other reason, you discover that actually there's a ton of work to be done there, regardless of the importance of decarbonization.
David Pomerantz:
That's definitely been my experience and journey about utilities. I mean, I got into this stuff a little over a decade ago. And even then, I think in the climate community, this sort of two-part equation that people are so familiar with now, which is moving the electric sector to clean sources of energy that don't emit carbon, and then electrifying everything else that we can. That was well in place when I started working on utilities and so, if that's the equation you're thinking about, electric utilities kind of are right at the center of all that. So it made a lot of sense for me from a climate perspective as I've gone — and coming from a place of humility, like really not being a technical expert in electricity and learning a lot as I've gone along the way, you realize from all these other perspectives sort of a general good government and campaign finance and concentration of power in the economy and just generally —I mean, the cost of electricity is kind of the base input for so many parts of the economy. If it's even a little bit higher than it needs to be, the spillover effects of that on everything are really big. So, yeah, that's certainly been my experience as I've gone along, is like, utilities are so important for climate and also so important for just about everything else.
Robinson Meyer:
You described this two-step plan to decarbonize the economy. The first is you clean up the electricity system. You shift as much demand as possible to zero carbon and clean fuels. And then you expand the electricity system. You try to electrify everything you can. And the way that the technologies that we want to electrify work is that you can do this a little bit out of order. If you're also gradually decarbonizing the electricity system, it's better to have more EVs, even if you power them with natural gas in the short term, because then you lock in the EV infrastructure and then you can gradually clean up the grid. It's like a two-part race and you can kind of run both at the same time.
David Pomerantz:
Totally in parallel.
Robinson Meyer:
OK. But when people hear this game plan, I think there's a sense that the utilities will be on board with it or certainly that the utilities will not oppose it. What has your experience been of how utilities feel about this plan? I mean, are they a fan of expansion and not as much a fan of decarbonization? Or are their incentives so misaligned, let's say, that they don't even necessarily care about the kind of expansion in terms of kilowatt hours that we all care about? And what they're really focused on is just building a lot of infrastructure of any kind that then they can make their customers pay for.
David Pomerantz:
I'd say a few things. So one thing — this is such a boring disclaimer that everybody gives when they talk about utilities, but it's true and worth making the caveat up front: they're not all the same. Putting aside the big differences within the sector, right? So you have about two-thirds of America served by investor-owned electric utilities. So these are corporations owned by investors on Wall Street. And then the other third is split between, you know, different versions of public power entities, either cooperative utilities, mostly in rural parts of America, or municipal utilities. Those are all very different.
But even if you just look within the investor-owned utilities, which I think is mostly what we're going to talk about, they're not all the same. So for instance, one important distinction for this question about their posture toward decarbonization and electrification, there are some utilities that all they do is electricity, right? Like they sell electricity, they distribute electricity. There are others who also own gas utilities. This has become more common as the industry has concentrated and as a function of mergers and acquisitions over the last couple of decades, really conglomerated a lot. And so if you're a utility holding company that owns multiple utilities.
Robinson Meyer:
Like Berkshire Hathaway Energy.
David Pomerantz:
Sure, that's a good example, right? So taking Berkshire Hathaway Energy, they own electric utilities. Berkshire Hathaway, their pipeline group, runs about 20,000 miles of pipe and moves about 15% of the gas consumed in the U.S. in 2024. So they have a different set of incentives. The people who run their electric utilities might be relatively positively inclined toward electrification, but the people who run their gas pipeline certainly aren't. They own a majority stake of a LNG terminal, Cove Point. So even within a single corporate utility, you might have pretty mixed incentives towards something like electrification. I think one very broad way to answer this is I think most electric utilities, just looking at the electric part of the sector, they're going to be relatively positively inclined toward electrification, mixed on decarbonization.
But actually, I think this is one of those cases where everybody who is really interested in climate change, and I certainly put myself in that category, even people who are really opposed to climate action, say from the political right, are way overindexed on how and whether that is a defining principle of how utilities make decisions. The way utilities make decisions, the most important thing to them, the most valuable commodity to them by far has nothing to do with, like, is it solar or gas or wind or coal? It's their monopolies. That is the crown jewel of how a utility makes money. And that leads to some situations where, like, you've had utilities in blue states who will accept government policy to speed up transition to renewable energy, but they'll try to get their pound of flesh as part of that acceptance. And usually that pound of flesh is a retrenchment or reification of their monopoly. So they'll say, like, “Yeah, we can dance with decarbonization a little bit, but we want to increase our ownership share of that new clean energy system of assets that we're going to build.” And you've actually seen that literal tradeoff happen in states where you've had really politically powerful utilities and democratic policymakers who don't want to fight with them, but want to get climate policy to happen. So it's like, everything in service to the monopoly.
Robinson Meyer:
And the monopoly here, this is a type of corporate — I'm not even sure what to call it, that exists in very rare places in American law. Or doesn't exist that often in American law, right? It emerges from this correct observation, especially correct in the early 20th century, but I would argue still holds in many respects to this day, that the electricity grid is a natural monopoly. We would rather have one provider of the electricity grid to everyone's homes because we don't want lots of duplicative infrastructure. You don't want, like, your neighbor in your apartment building or your neighbor in your street to have a different set of wires going to their house than go to yours. So we need a ton more extra wires then.
So it all dates from when electricity and distributed electricity was a new technology form in the early 20th century. And different entrepreneurs were racing to get electric light and different wires strung up. And there are some early stories from that period where, like, as new companies were competing to distribute electricity, there would be parts of New York City, for instance, where there's enough wire getting strung up where, you know, you can’t see the sky — that kind of thing. I don't know how apocryphal that might have been. But at that time, certainly, it made sense to have a monopoly on electric distribution.
Robinson Meyer:
And the monopoly here is like a true jurisdiction, right? It's basically saying, “In this geographic area, only one company can provide electricity service. No other company can do it.” And that kind of corporate right exists only for this small set of regulated monopolies in the country. I mean, we have it for water and electricity and natural gas distribution. And that's kind of it, I think.
David Pomerantz:
It's very, very rare in our economy. And I think there's an interesting conversation happening right now, sort of on the sidelines of all this stuff among a small handful of antitrust lawyers of like, how much should that still be the case? Like, maybe in the early 20th century, utilities did have a sort of, quote unquote, “natural monopoly,” where increasing scale and reserving it to one company would make all this cheaper. Now it's certainly true that to the extent there are natural monopolies in this industry, they cover a much smaller part of the electricity value chain than they once did, so like, maybe electric utilities should still be entitled to monopolies over the distribution wires, is that true for electric generation or transmission or even, billing and the customer relationship? All those are areas where in different parts of the country, to varying degrees, competition's been introduced and often to really good effect.
Robinson Meyer:
Well, let's talk about the bill. I want to get back to these questions, but let's start by talking about the bill. So I think the bill's biggest effect on the power grid are these transmission provisions. And I've been covering a lot over the past several years about how important transmission is for decarbonization. What does the bill do on transmission? How do you think about this bill overall and its effect that it would have on the energy system?
David Pomerantz:
Yeah, so the bill I'd say is pretty ambitious when it comes to reforming how transmission is planned and permitted and paid for, and also who gets to control it. So maybe just in terms of the status quo, the short version is, for the kinds of transmission that we're going to be talking about here, this distinction is pretty crucial — like, longer lines, higher voltage lines, the ones that connect different regions of the country to each other that are critical for the energy transition, and also, candidly, would be quite critical even without it, right? Like, just for cost and reliability. Those lines we are not building. We're just building very few of them. Some parts of the country are doing a little bit better, but that's clearing the very low bar of doing almost nothing. Building regional or interregional transmission has basically ground to a halt in America.
So the bill, I think, seeks to address that problem. And it does a few things. So starting with the big stuff, probably the centerpiece of transmission, the first reform listed in the transmission section of the bill is around permitting. So currently, if a transmission line — one of these long lines that I'm talking about, that has to cross multiple states — it has to be permitted by each state it crosses. The bill says that if a single state says no on one of these high voltage lines or is just taking too long to decide, federal regulators can step in and approve the line if they find that it benefits the public. They can't do it capriciously, but if they find that it benefits the public, they can step in and approve that line. And if they're even higher voltage lines — so lines of 345 KV or more — those lines can actually file at FERC in parallel at the same time as they're filing for permissions at the state. And so it should make getting those lines permitted much easier.
So that's one change.
Another really big one is around planning. So right now there are different transmission organizations in different parts of the country. So I think most of your listeners will be familiar with some of these even though most Americans probably are not, but some of these are called RTOs or regional transmission organizations. Those are formal organizations, there's one called PJM that covers kind of the mid-Atlantic states, in the eastern part of the Midwest there's MISO, in the sort of more Great Plainsy part of the midwest extending kind of in a big vertical strip down the middle of the country, They all plan transmission differently, right?
And if that sounds a little bit nutty, I think everybody would probably agree that if you were building this system from scratch, we wouldn't have it that way. And this is really important. The system wasn't built from scratch. So we didn't have regional transmission organizations up until reforms that started in the late 1990s. So for the entirety of the 20th century, utilities basically did this on their own. Like, they decided if they needed a transmission line and that was kind of it. So one way to look at this is, like, we've been on this long journey toward trying to take control of the transmission system away from individual utility companies and sort of put it more in the public sphere. Developing regional transmission organizations was a part of that, but it's been an incomplete journey, I would say. And so one of the things that BAAJA does is this kind of consolidated planning. It gets the country's various grid regions to plan in congruent ways. And I said we're not building much regional transmission earlier. In terms of inter-regional transmission, so transmission that actually crosses between regions, like crosses from PJM to MISO, we're building basically none of that. So that kind of consolidated planning should help with that.
Robinson Meyer:
So there's one set of changes in the bill, as you were saying — I mean, we talk about this, we've talked about this before, written about it, which is basically like: if you wanna build a natural gas pipeline, you go to the government and if the federal government says, yes, you can build it. Like, they have a checklist of things that they have to do to see if your pipeline's in the national interest and they check, check. “Okay, it's in the national interest. Here's your permit, you can go build.” This, I believe, would not quite do that for transmission lines, but it basically creates a federal backstop authority where FERC can do it. And I believe it even says, like, with pipelines, FERC basically is told, “Look, if this transmission line meets this criteria and that criteria, you will find it in the national interest.” This isn't just a “you may.” This is like, “You must actually go and find this thing in the national interest if it meets certain certain guidelines.”
David Pomerantz:
That's right. The way I would describe this is the reforms in the bill for transmission permitting probably don't make it quite as easy to permit a transmission line, interstate transmission line, as it currently is to get permitted an interstate gas pipeline. But it's a lot closer to that, whereas under the status quo, this is all fragmented. It's really hard. And in the best case, it's taking you years and years.
Robinson Meyer:
We can get into why it is so easy to build a natural gas pipeline while it's still not easy to build a transmission line. And my sense is, yes, it's that the whole system is built to service the needs of fossil fuel companies and not as much electricity. But it's also just — number one, it is an open question to me of whether even if you were the most powerful set of organizations in the world you could get Congress to pass a law that gives any kind of linear infrastructure private developer the kind of authority that natural gas developers have under the law right now. And that's because the law that gives them all that authority was written in the 1930s. It's very old. It's just like an old New Deal-era law.
David Pomerantz:
I'd agree with that. I mean, you're not going to get me to disagree with the fact that much of the federal government's decision-making is sort of — there are a lot of incumbency biases that fossil fuels have. I think the fundamental thing happening there is that the Natural Gas Act was passed a long time ago and it would be probably harder to pass it that way now, so what's good about the the current transmission permitting legislation on the table is it certainly gets closer to that point, where it would be easier to permit transmission now.
Look, not everybody's going to be in favor of that, it's probably worth noting. Building long transmission lines does often generate a lot of discontent from landowners. So there's no point dismissing that. That becomes a value judgment for people who are landowners who oppose a transmission line. I don't think there's anything in the bill that takes away their ability to file comment, to say they want the line moved. I don't believe the permitting reforms in here are like railroading people in that way. But there's going to be people who are unhappy with anything that gets transmission lines built faster.
I am of the opinion personally that as a country, both for energy transition reasons and also to have a better functioning electric system and ultimately lower rates, that the balance is off right now. And we have to be able to build more of this. And I think, like, this maybe gets into some of the broader questions in the bill about permitting and how hard it should be to build energy infrastructure, I think, is a question that's sort of laced through the entire legislation.
Without getting into all that, I'll just say it's worth keeping in perspective, like, a transmission line versus other things. So one of the arguments I've tried to make to people, at least privately, who are understandably sympathetic to, like, landowners or conservation interests or tribes who are opposed to a transmission line is, for the most part, their opposition is around the viewshed. Basically, they don't want to look at it. And I'm not saying that in a pejorative way. I think there are a lot of cases where those concerns are very real and deeply felt. I do compare that to, however, like if building more transmission lines, more regional transmission lines allows coal plants to shut down, which it would in the long run, because it would undercut their value, when we're talking about the effects of those plants, we're not talking about somebody's view, right? We're talking about people's lungs. And so the bill will make it easier to build transmission lines and there will be people who don't like that. But I think that comparison's pretty important to keep in mind when we're talking about that.
This is all sort of in the “making it easier to build transmission” category. The next one is like, Who gets to control it and are we building the right type, and is it a good value for customers? So we can talk about that next, but in the “making it easier to build” category, a couple of other things. These are more discreet, but important. So one section of the bill basically says that if a transmission owner wants to reconduct to their line — so I'm probably going to sort of do violence to the technological nuance here, but for normal people, you could think of it as, like, basically string-up better wires, wires made out of better materials that can carry more electricity. It exempts the transmission owner from having to go through NEPA review for that if it's in an existing right of way. So I think that makes a lot of sense. Like, they've already presumably gotten that line permitted. They don't need a new review for stringing up new wires.
And then the other thing that it does that's in this sort of encouraging-new-technology vein is that it requires that investors and utilities use what the bill calls advanced transmission technologies on all new lines, including the best available conductor technology. And actually to look at existing lines and say, if the benefits of upgrading the line outweigh the costs, they need to do that too. And it assumes that it's prudent, which means that that actually is a thing that will help the utilities do that. It's really good for customers. There's a lot to be gained from just upgrading the lines that we have. There's been lots of studies on this. We can really increase the capacity of the system that way. It's probably being underused right now because, from a utilities perspective, the cheaper solution isn't always the best one.
Robinson Meyer:
I mean, we've talked about this in previous shows, but this is because utilities turn a profit and in fact, make all their profit off of building big permanent infrastructure that they can quote unquote “rate base,” which means that they then take that infrastructure, break it up into 30 year payments, add a guaranteed profit on top of it. Often now in the 8 to 12% range, I mean, it's much higher than you could get from say, putting your money in treasury bonds and then just charging it to electricity to their captive customers on top of whatever their operational expenses from generating the electricity that they need to generate are that month, right? Is that a fair description?
David Pomerantz:
That's exactly right. That's exactly right. Utilities make money from the equity share of their capital investments at a rate of return that is administratively set by regulators. So most businesses who sell stuff, they want to have the lowest costs and the highest revenues. For utilities, actually for their capital expenses, the building stuff, they want higher costs, at least insofar as they're funding it with their investors' money because that's what they earn a profit off of.
Robinson Meyer:
The transmission section is the, I don't know that this is the right framing, but it's often framed as climate advocates as like the good part of the bill. This is like all the things that people want to see happen in the electricity system, or certain environmental groups have framed it as the good part of the bill, and they've contrasted it with other changes that the bill makes to say longstanding environmental review laws. They say, “Oh, we love the transmission section. We love the transmission planning section. This is the good part of the bill.” But it does sound ultimately like a planning process, and not that we're mandating everyone build more transmission lines. And so why do we think that this planning process will ultimately produce more transmission or that the bill as a whole will ultimately produce more transmission lines across the country?
David Pomerantz:
Well, those are fair questions. I think a couple of things. One is in the cases where regional transmission organizations have basically gotten their act together and come up with a plan to sort of value and figure out the cost allocation and who's going to pay for what and plan out a lot of transmission. They actually have done that. The examples are just far too few and far between. But MISO is probably the best case study of this. Starting, I think, in 2011, they had their MVP process to plan regional transmission, and it's all happening too slowly, but it is happening. Like, they sort of got on the same page as an RTO about how to do planning, and you're starting to see lines being developed. Now, they're not building lines yet in the southern part of their region, which I think you can draw a line directly tracing that failure to the resistance of an investor-owned utility, Entergy. And they're not building lines yet between MISO North. So this is like Minnesota and the Dakotas and those areas, and MISO South, like Arkansas and Louisiana. There's a big physical bottleneck there.
And everybody recognizes they need to build more north-south transmission in the middle of the country to bring cheap wind from the Dakotas and Minnesota down to the Arkansas, Louisiana regions and Mississippi. And the company that has been sort of at the center of blocking that has been Entergy. So, like, I think what we know from just observing the way the RTOs are working now is if they're prodded and pushed and given standards and sort of clearing out a lot of the bureaucratic process and fighting, they can plan regional transmission.
A lot of the components of the bill, some of which we haven't talked about yet but should, I think are designed to subdue some of that utility opposition to building more regional and inter-regional transmission as well. But it's a totally fair question. I mean, like what the planning and permitting reforms in the bill do is, they do this very carefully, but they take some power away from local interests like utilities and RTOs and they give it to FERC. They do that, I think, thoughtfully, which you would expect with Republican co-sponsors who care about federalism. So it's not like just totally throwing those interests by the wayside and giving the federal government all planning authority as much as some people would probably really like that. You know, seeking to create a more robust, empowered FERC when it comes to transmission planning.
David Pomerantz:
A fully reasonable question is, will FERC use those new powers effectively and responsibly? And that is probably a threat to the bill's efficacy looking forward. At the same time, the status quo is not working. And actually, I think this is an issue where FERC has shown an appetite for action and even some bipartisan action in recent years. So there's some reason for optimism that FERC will step up and use its new powers in an effective way.
Robinson Meyer:
My understanding is also that part of what happens as part of these planning processes and part of what happened in a grid-planning process is that if a need for a line is shown, then a third-party kind of outside transmission developers can step in and build that line and they get faster permitting and they get all these authorities involved. That right now they would never have. And so to some degree, there's a bit of a backstop here, which is like if an RTO through this process under FERC's oversight determines it needs a line and then the line like the utility doesn't build the line or the opposition to the line, like someone else can step in and build this line. And it's like you get all your papers stamped really quickly if the line is found to be beneficial.
David Pomerantz:
That's true. I mean, I would broadly characterize the transmission reforms in this legislation as being very pro-competition right now. And I think one of the sort of sticks in the bill is saying that if an RTO and the incumbent utilities don't step up to build these lines and competitive developers can, then there's a pathway for that to happen. There are a bunch of other ways that the bill encourages competition that I think are really important. And really, I think why they're so important is because, maybe to zoom out and say, because I'm not sure we've answered this question yet: Why haven't we built transmission? If it's so needed and it would lower rates and it's good for the energy transition, all these things, why have we not done this? And a lot of the debate around permitting has actually focused on the wrong factors here because it fits into other bigger political conversations around permitting reform. There's been a lot of talk around, landowner or conservation or tribal resistance. Those things are real. And as we discussed, there's titles in the bill to address some of that. But I would argue that the big reason we haven't built regional and inter-regional transmission in the last couple of decades has actually been utility resistance. And so maybe to come back to a question you asked earlier, like why would they resist? Like they build the transmission, right? I think the key thing here for people to understand is the reason transmission has so much value, like the reason it's good that it would lower rates to build interregional transmission lines, is because you're importing electricity from a place where it's cheaper to a place where it's more expensive. Well, that's great for ratepayers. But what about the company that owns that expensive electric generation? They stand to lose. Like that's undermining their assets.
Robinson Meyer:
And their monopoly, really, too, right?
David Pomerantz:
Yes, it's 100% undermining their monopoly. So, like, if I can, let me just give one or two examples of how utilities have responded to this threat because I think it speaks to what the bill is trying to solve. Next Era, ironically, a company that builds plenty of transmission, but I think that's kind of part of the point; they show how even utilities who build transmission can oppose lines if it threatens their own assets. So Next Era contributed over $20 million to a group called Mainers for Local Power. That was most of the money that group spent in support of a ballot referendum in 2021 to ban a transmission line to carry hydropower from Canada to New England. That initiative won. Courts later overruled it and the line went forward. But Next Era did more than that. That spending was public. Previously to that, they privately spent covert money on groups to route money to the Democratic Party in Maine and others to try to stop the line. Why'd they do that? Well, they own nuclear- and gas-generating assets in New England that would be undercut by that cheaper power. And then I mentioned Entergy before. Entergy is probably the poster child for this. So Entergy serves customers in Louisiana, Arkansas, and parts of Texas. And other utilities in the Southeast are actually not part of an RTO. They're probably the fiercest opponents to regional transmission.
Robinson Meyer:
The Southern Company and Georgia Powers of the world?
David Pomerantz:
Yes. Yes, that's right. Southern Company, Duke Energy, those companies. So Entergy was very happy not being in an RTO like at Southern Piers, they actually committed to join an RTO at the point of a gun. So they were facing a DOJ antitrust investigation into alleged anti-competitive transmission practices. This kind of gets back to your question, Rob, about whether they're natural monopolies or what. Well, the DOJ at this time felt that energy was surpassing its monopoly privileges, at least in the realm of transmission. So it made an interesting choice to join MISO, the mid-continent RTO team. And they joined Entergy to join MISO in 2013. There's actually really good data on what happened next. So MISO tracks its planning hours, like the hours it spends to plan transmission. And they went at the time of MISO joining in 2014 from 1,000 hours to, by 2018, almost 6,000 hours. So basically Entergy's role in MISO is to gum up the works. I mentioned earlier, MISO approved over $20 billion in regional lines in 2024. All of those lines went into the Midwest. None of them went into the South, where they might out-compete Entergy's plants.
There's a really good paper on this from an economist named Catherine Hausman that asked the question of, like, how much would transmission lines cost Entergy if they were built? And she found, I believe it was $850 million in net revenues that the company would lose out on if cheaper electricity were imported into its region. So that's what they stood to lose. And they did all kinds of kooky things to protect that monopoly. So Entergy actually had kind of like an undercover former executive attend MISO meetings without disclosing that they were working on behalf of Entergy, they co-opted their state regulators. So my colleagues at EPI did some great reporting on this, showing that Entergy coordinated with the Mississippi PSC staff and the PSC's outside consultants to push back on MISO's long-range planning. When NextEra was actually trying to build a line in East Texas that would have connected ERCOT to the rest of the grid, Entergy backed a law in the legislature that would block anybody but Entergy from building a line like that. And MISO later canceled the line. So companies like Entergy, NextEra, Southern Company has been probably the worst offender on this. They've all sought to undermine transmission development and kind of like an endless parade of chicanery. And even when it's not like undercover, hiring undercover consultants, Southern Company has like a decade-long record of just advocating to FERC that there's no new value from electric transmission, regional transmission to the Southeast. They've got it covered and there's no reason for reform at all.
Robinson Meyer:
I want to hit a few more things quickly. You mentioned basically Southern Company has opposed transmission lines repeatedly. And Southern Company, the Southeast, unlike other parts of the country, where, you know, in the Mid-Atlantic, we have PJM and New York and New England and the Midwest and Texas and California. There are electricity markets in Colorado. There's electricity markets and the electricity markets function and there's independent power producers. And there's still local utilities and the local utilities have a lot of monopoly power. But there's been successive efforts over time to reform the electricity provisioning structure that exists in those regions of the country. That is not true in the southeast. In the southeast, there are still monopoly utilities. And those monopoly utilities are Southern Company. There's George Power. There's a handful of others. They own all the power plants that produce electricity. They own the transmission lines that get the electricity to customers, and then they own the line that runs from the local substation into the customers' homes. There are exceptions to all of this, but in general, these are still old-fashioned, vertically integrated monopoly utilities. What does the bill do to make sure that organizations like Southern Company or the Southeast generally have additional transmission capacity?
David Pomerantz:
Yeah. So the most important thing the bill does is it covers them, which is something that in the flurry of lobbying over the next few weeks, Southern Company and Duke Energy, I expect, will try to get themselves exempted. So even though there's no RTO in the Southeast, they are covered by the various laws and orders from FERC that says they have to do transmission planning of some kind. And they would be covered by this bill as it currently stands based on the public draft. The problem is they're not doing any of that. Southern Company, as a good example, Southern Company is one of the biggest utility companies in the country. They own the monopoly utilities, the only monopoly investor-owned utility that serve Alabama, Mississippi, and Georgia. Georgia Power, Alabama Power, and Mississippi Power for electricity, at least. They're co-ops too, but they're the only game in town when it comes to large corporate utility companies. To date, it's not that Southern Company — and this is actually true for other utilities around the country too, but the problem is most pronounced in the Southeast— it's not that they don't build transmission. They build local transmission, right, that enjoys really high profits but is of questionable need and is much easier to permit because it often doesn't cross state lines. So the bill would cover Southern Company and Duke and the other Southeastern utilities for its planning components. It doesn't draw a distinction from the RTO regions. It says they have to do consolidated planning and then they have to sync up with their neighbors to match planning with them as well.
The Southeastern utilities will fight all that. Aggressively. Southern companies probably spend more money lobbying FERC than any other utility. NextEra, which is in Florida, owns the Florida Power and Light utility. Florida Power and Light and NextEra spend more money lobbying than any other utilities. Actually, for what it's worth on this point, we looked at Q3 lobbying disclosures in the Senate. And while the companies don't have to list, like, details, they don't have to say the position they took on legislation, you do see what they lobbied on. Almost all these companies lobbied on BAAJA. And while you don't see how much they spent on any one bill, just for a sense of scale, Southern Company only on its in-house lobbying team spent over $3 million dollars in the third quarter this year on federal lobbying. That's just in three months. They spent a million dollars a month lobbying Congress, and they do list transmission planning, interconnection, permitting, EEI — the Trade Association for Electric Utilities — they spent 1.6 million. Entrygy spent a little over half a million. This is a lot of money that is pouring into the coffers of utility lobbyists in the last few months to influence the bill. So far, they've been unsuccessful, which speaks to how down on their political luck utilities are right now.
But coming back to that local transmission, just quickly, this is where I think the bill seeks to do maybe the most unexpected and important thing that I would draw attention to. I think it's probably utilities' top priority to kill, which is that, like I said, currently utilities, it's not that they're building no transmission, they're building plenty of this local low-voltage transmission. The bill would allow, and this is totally new, would allow states to refer to FERC, a utility's local transmission planning. If they find that the utility is not picking efficient or cost-effective local projects, or that it's getting in the way of regional planning in the exact way I mentioned Entergy is doing, then the state, like a state like Georgia or Louisiana, could say, hey, FERC, can you help us out here? Because the reason we're not building the regional transmission we need is because the utility is blocking that and wasting all the customers' money on local transmission. And then a joint team between FERC investigators and the STEEC would be able to investigate that utility obstruction. And if they found findings that the utility was in fact doing that, they could take action. They could cut the profit rate the utility earns on those local lines. They could issue fines. I think the utilities will come gunning for that really hard. I actually think that's a really important part of this bill because it recognizes that the problem isn't that the utilities aren't spending money on transmission. It's that they're only spending on the kind that they like that doesn't threaten them. So if all the bill did was around permitting and aligning planning, I think that would be really important and worth doing. But this extra component, I think, will give the whole thing a lot more teeth.
Robinson Meyer:
Why can this kind of provision or just all the reforms that the bill would make to the transmission system, why can all of this happen now? Like, why is it happening now? Because I think, much like, say, the local and community banks, which have a lot of power in Congress, even more power in some respects than the investment banks, the utilities are supposed to have a lot of power in Congress, too. Almost every member of Congress, there's a local utility in their district, right? And so why is this happening now?
David Pomerantz:
Well, I think utilities are in their weakest political moment they have been in for a long time. It's bipartisan. And the simplest answer is we're going through a ratepayer revolt nationally where utilities have raised rates and bills on their customers repeatedly. I mean, investor-owned utilities rates have gone up faster than inflation. And by the way, one thing that's really important here is that it's not just like, oh, it's because transformers are more expensive and everything's more expensive and it's sort of a part of the economy. Public utilities like co-ops and municipally-owned utilities, have not raised rates faster than inflation. Their rates have actually gone up slower than inflation.
I'm going to parody myself here, but really a lot of this is about corporate greed. I mean, utilities at this moment where data centers are creating all this incredible new demand and even absent that, there'd be new demand from electrification. The pie for investor-owned utilities to make a lot of money should be growing bigger. Unfortunately, they kind of insist on having every slice of the pie. It's really turned the public against them dramatically. And you're seeing that public sentiment change, I think, reflected in politicians. And it's interestingly bipartisan, right? So maybe not surprising that Democrats who for some years have been conditioned to think that electric utilities are not always on the right side of climate. There are large corporations who are raising people's rates. Like you could kind of see where that would maybe be coming from. But it's just as much with Republicans. And that's probably the much more dramatic change, actually, is that from the reporting I've read, the Republican negotiators on the bill were very happy to sort of introduce utility accountability type provisions in there. And that just would have been unheard of five years ago.
Robinson Meyer:
There's a meme from SpongeBob SquarePants where Mr. Krabs, the cartoon crab character for those listeners who are Older Gen X and above, says, “Wait, I hate golf” in the middle of him golfing. He realizes he hates golf while he's golfing and people sub other things. And I think there's a story of this bill, which is basically Democrats going, “Wait, I hate permitting laws.” And Republicans going, “Wait, I hate utilities.” And yes, this bill basically being the product of those two realizations.
David Pomerantz:
I totally agree with that. I mean, some of this is just about people's bills going up and being mad at utilities and the political moment reflecting that. I do think there are some other things happening below the water level. One of the first things that made my eyebrows go up in the second Trump administration was in early 2025. The Trump administration's Department of Justice formed this anti-competitive regulations task force. It was in response to a Trump executive order. And it had paragraphs for different sectors of the economy. And on energy, it said it was seeking comment on, and I'm quoting this part, “laws and regulations can undermine reliability and affordability by protecting incumbent electricity providers from competition or disruptive innovation.” I mean, that could have been written by any environmental group in the country who's been battling incumbent utilities for the last several decades. And it was coming from the White House.
And so, like, traditionally, utilities have probably at the federal level been closer with Republicans than Democrats. They give more money to Republicans by about a two to one margin in most election cycles. But I think that has changed in the last couple of years. I mean, if you just look at Trump one versus Trump two, Trump's first Department of Energy was rife with staffers who came from electric industry, came from industry. That is not the case now. Like, there is a strong sort of anti-monopoly sentiment in parts of the Republican Party, whether it's always expressed is a different question. But I think you're seeing a lot of that bubbling up. And then with everything happening on energy prices and data centers, it sort of became a perfect storm for utilities to very quickly lose a lot of institutional power that they had previously held with Congress.
Robinson Meyer:
Do you think that this will continue just from what you're getting a sense of? Will this decline in utility political clout continue or is this limited to this moment? And if this bill doesn't pass, then utilities are going to close ranks. And there won't be another chance to take on utility power again.
David Pomerantz:
That's kind of the million-dollar political question from where I sit. On the one hand, unfortunately for ratepayers and customers, I don't see investors and utilities having like a sudden change of heart, and doing the things that they could and should do to arrest inflation and lower people's bills. I do want to make it clear, like, they could do that. There are a lot of things that utilities could do if they weren't looking at their next quarterly returns and just sort of maxing cap-ex, that they could do to bring people's bills down. Like, you could see that on the public side of the sector. I don't think they will. I think their incentives are too perverse. And because of that, I think they're going to keep getting themselves into trouble politically by going for rate increases and bill increases. And so I see that at least for the next couple of years as being somewhat secular. Some of it, by the way, is actually not wrong, right? Like the grid is aging and they do need to spend money. That's why it's unfortunate that they're not saving money where they can because they are kind of in a pickle there. So like, that part I see as sticking around at the same time on the other side of that argument.
I think one thing doing this work has taught me is that these companies have been around for over 100 years. If you read some of the history on some of the big political fights that investors and utilities were in the 1930s, they do the exact same things now. They did that. They spent on propaganda. They route their money through trade associations. They recruit other parts of the political economy, like labor, to back them with politicians for whom that constituency is important. Like, they have and this is something EPI has has really tried to investigate and highlight and ultimately address they have at the end of the day like a publicly subsidized pool of money of ratepayer money to spend on politics that almost no other industry has and so I think like they will regroup. Counting them out is probably a mistake. a utility CEO a couple weeks ago, I think for Eversource, got caught sort of saying the quiet part out loud, which is, I think he was trying to appease investors, but he said, “Look, I know you're hearing a lot of pretty nasty things about us from governors around the country, but those people, you know, they text me privately, we talk, and they'll tell me privately we're still friends and this will all blow over after the election.” So I think that is the hope of the sector, that, all this stuff, all this anger about prices, their political misfortunes right now, that only lasts through November and people will find something else to be angry about given enough time. I don't think that's true when so many Americans are being forced to choose between their medicine and groceries and rent and their utility bills. And you can see it in the polling. It's pretty dramatic, but that is what they'll be working toward, and they'll have a lot of political money to try to make people forget.
Robinson Meyer:
You observe basically that municipal utilities, publicly owned utilities, government owned utilities have not risen rates as fast as inflation. Well, investor owned utilities have risen rates much faster than inflation. So this was because of corporate greed. I think what's interesting is like whenever I hear this account, like this was not happening in the 2010s. It is happening now. And I assume greed being one of the seven deadly sins has a somewhat monotonic relationship in the economy. So what changed in the past few years that allowed these companies to exert their greed or their authority much more aggressively than they could, say, in the decades before? Like what has helped trigger this broader inflationary hike?
David Pomerantz:
Yeah, it's a little bit hard to pin down to a particular year because the way so much of utility finance works is like, a lot of their profitability is driven by the return that they're able to secure from regulators. And that return then compounds over years and years. So like, if a utility secures a really high return on equity in one year, like you're still seeing that drive its profit margins up, like 15, 20 years later, which makes it really hard to sort of draw lines between cause and effect, like what period at which they started making a lot more money versus what period the regulatory changes happened. One thing I'll say though is we have been in a period in recent years where, for a couple of reasons, the grid genuinely has needed investment, sort of alluded to this before, but one of those reasons is just like the cycling out of infrastructure. So a lot of the grid is pretty old. The other reason is because of increasing effects of extreme weather. So that's storms in the south and wildfires in the west and utility infrastructure, electric infrastructure is very exposed to all that stuff.
So we are in a period in the last decade of utilities genuinely needing to turn over a lot of that investment. They should be allowed to do that. The problem is they shouldn't be allowed to sort of rake people and laugh all the way to the bank along the way. I think probably if you ask most Americans and even just most politicians, like, should utilities be able to profit at really high levels from the stuff that they need to build or rebuild as a result of a hurricane or wildfire or some other tragedy, I think most people actually, if you ask them, would assume they were doing that at cost. Like, they wouldn't even understand that that can be such a big utility profit center in the first place. So I think it's a combination of really poor regulation at the state level by public utility commissions who are in charge of this stuff, and FERC for that matter, and being in a period of needed cap-ex investment for the grid.
Robinson Meyer:
Do you think the bill is good for data centers? And what's been your observation of how utilities have behaved during the data center boom?
David Pomerantz:
I think the bill is good for keeping data centers on the grid and making them pay more for it. So let me unpack that a little bit. Right now, data centers have this choice they have to make where they can either try to get a grid connection, which is hard because the grid is so broken. I mean, the sort of fundamental reason it's hard is because it's so hard to build transmission. And the bill seeks to address that. Because it's been really hard for data centers to get a grid connection, some of them are instead building these off-grid gas parks. We need a more malevolent sounding word than park, but like these behemoth facilities.
Robinson Meyer:
Totally islanded, basically massive, extremely dirty natural gas power plant fields.
David Pomerantz:
Yes, that's much better. These are cropping up in West Texas or cropping up in Ohio and other places. From my perspective, this is the worst possible outcome. Like, these are climate super emitters. To the extent you believe, and I do, that data center development that was done really well could lower people's rates. It takes away that possible upside, right? And I don't even know that it totally insulates people from rate impacts of data centers, like putting aside the pollution, like nothing is totally disconnected from supply chains, right? So even the off-grid data centers, that's part of the implicit promise there is that they're going to hold rate payers harmless. Well, they're still buying up all the turbines and all the transformers and like everything that the grid needs.
Robinson Meyer:
I think this is a particularly salient concern in Pennsylvania and Ohio because the Trump administration is trying to expedite 9 gigs of gas in Ohio. And like, I know there's a ton of gas in the Marcellus, it's completely conceivable to me that, like, production increases and we just get an extra 9 gigawatts of gas every day out of the Marcellus. But like, it just does seem to me that there's going to be a bottleneck somewhere and that is going to increase natural gas prices for everyone else in the Marcellus and everyone else in that basin. And it's not good for the climate, but that's how energy prices work in equilibrium. But it means we need to be realistic about what adding 9 gigawatts of quite dirty gas consumption would do to the entire region and that you can never prevent new energy demand of that scale from not doing something to everyone else's rates when you're talking about a system that can only grow so fast.
David Pomerantz:
Yes, I totally agree with that. I see that off-grid gas as basically like a failure mode for everybody. It's not really what the data center operators want. It's not really what the utilities want. They'd rather have the load. It's terrible for the climate and I don't think it does anything for ratepayers, so to me, the goal should be: data centers, if they're going to be built, that are on the grid paying their fair share and even like going beyond their fair share, right. There's some interesting fights actually happening between the data centers and the utilities, where in places like Virginia, some people are saying — and some of the hyperscalers, at least in selected cases, are volunteering for this, since utility capital is so expensive and that's where they make their profit, and what the data centers really want is speed, but they're somewhat price insensitive, or at least more price insensitive than they are speed sensitive: Like, why don't you displace all that utility financing with data center financing? Make them pay for the stuff we need on the grid.
That to me is the best case scenario, is that the data centers that are built are built on the grid, and they not only pay for their stuff, but they pay for the grid that we all want and need. What BAAJA does on data centers moves toward that goal. So it makes a policy change that allows utilities to charge data center customers for not only the cost of using specific transmission infrastructure that their data centers cause to be built, but also the cost of the existing power grid. And I think that's a significant change. Now, like, if your whole orientation toward this issue is to stop all data centers at any cost, independent of whether they're on-grid or off-grid, then, like, I guess a reform that makes the on-grid solution a little bit easier for data centers and everybody else — factories, hospitals, everybody, but also sort of makes them pay more — then maybe you don't like that. If your goal, from a climate perspective, is to have data centers that are going to be built on the grid be less polluting and contribute more toward funding the grid, then I think the bill is progress on that goal.
I also don't think those things are totally mutually independent. People can do whatever they want, of course, but people could support data center moratoria and support legislation that makes it more likely that data centers that are built are on the grid and paying their fair share. So anyway, that's what the bill does with regard to data centers.
Robinson Meyer:
One of the many problems that Americans seem to have with data centers is this disproportionate effect they have on electricity rates. And sometimes that's an effect of how the local electricity market works. And increasingly, it will become more and more just a result of the enormous electricity demand from data centers. And Americans have other problems with data centers, too. And people who fight data centers have lots of problems with them and would prefer to see a world with no data centers. And so this bill is not a data center bill, but it's trying to fix some problems around data centers in the energy system because it is an energy bill. And I think to some people, they look at that and they go, well, this is just going to make it easier to build data centers. And data centers are bad for X, Y, and Z reasons, not this reason. And that drives why, to their perspective, this can be a bad thing.
Notably, the politicians who have had the most success talking about data centers are not running on a — Abdul El-Sayed, Gina Hinojosa in Texas, right? They are actually not running on a “no data centers anywhere, anytime ever” platform. They're running on a “data centers if they solve this set of problems” platform. And the bill does in fact solve the energy set of problems around data centers.
David Pomerantz:
I think it at least moves the ball forward. One area where I'm somewhat sympathetic to people who say — I've seen this point made — that there's an asymmetrical time horizon issue in the bill where parts of the bill that will make it easier to build fossil fuel infrastructure could take effect pretty quickly, whereas the parts of the bill designed to encourage transmission development, I think, like we said, the tradeoffs may be a little more complicated than that, but that's the oversimplified version is that the transmission development parts of the bill will take some time. And I actually think that's pretty fair. People can make their own judgments about how they should treat the bill in light of that. The reason the transmission development portions of the bill will take some time to implement is because, like, mechanically the way a lot of this works is it kicks things to FERC to make rulemakings. And in those rulemakings — utilities will spend millions of dollars on lawyers to block the intentions of the bill. So I don't think that means the bill's transmission reforms aren't going to be effective. I do think what it means is if people want to see transmission reform happening, this bill passing would not be the finish line. If it overcomes the utility lobbying, which will be furious in the next two weeks or so or three weeks to either kill it or define it, even in that event, even if it basically passed as written, that will open a whole series of new fights.
And so to the extent this is a moment where Congress is interested and recognizing the detrimental effect that utilities are having on repairs, there's no reason they need to stop. I mean, there are a whole load of other things Congress could do, and certainly that dozens of new state legislatures and governors could do, to crack down on concentrated utility monopoly power that the utilities will use to subvert the transmission reforms in this bill if they pass.
Robinson Meyer:
As someone who's written basically saying we should create a continent-wide macro-grid of some kind, however we do it, it doesn't need to be the government who does it. I think that would make sense. It seems like that would be faster in a lot of ways, but it doesn't need to be. Like, this is the opening gun on that. This bill to me seems like the door opening to that possibility, like you cannot execute that plan without a piece of legislation like this passing but you cannot actually but it will not result it will produce a much better grid than the one we have. And if this, I think, bill were to pass alone, it would be an improvement, at least from the transmission perspective, on what exists right now. But this is like the door opening and then basically legislators, lawmakers, policymakers, potentially Democrats will have to walk through that door in the future. The John the Baptist of saving America's electricity grid — this is not the final salvation.
David Pomerantz:
I agree with that characterization 100%. And if there's an optimistic note to end on for that in terms of like what could happen next, what might happen next, I do think the fact that from all the reporting I've read, the transmission reforms and the bill have been relatively bipartisan, could mean that policymakers, both in Congress and hopefully at the state level, are ready to take the next steps in that, journey and not say, well, we sort of poked the big bad utilities in the eye this one time, but now let's all be friends again, but that they're actually ready to move consistently, which I agree with you, is critical. I think from a transmission and a grid perspective, the reforms in here are very necessary progress and wholly insufficient. So if they pass, there will be a lot of work to build on.
Robinson Meyer:
No matter what happens to this bill, I want to keep talking about it. I think it's such an important conversation. So I'm looking forward to continuing the conversation in the future. And in the meantime, David Pomerantz, thank you for joining us on Shift Key.
Rob talks with David Pomerantz, the executive director of the Energy and Policy Institute, about how the bill would remake the electricity grid — and strike against utiities’ political power.
Climate and environmental advocates are sharply divided over the Senate’s bipartisan permitting reform proposal. But what most people agree is that the bill’s changes to electricity and transmission law are really, really good — and in some sense are much better than expected.
Because of how the media works, that means nobody has talked about these proposals very much. So on this show, we wanted to focus on the part of the Bipartisan American Affordability and Jobs Act that has gotten rave reviews.
On this episode of Shift Key, Rob is joined by David Pomerantz, the executive director of the Energy and Policy Institute and a former Greenpeace campaigner. They discuss how the bill would rewrite electricity law, why the bill is bad for utilities, and why utilities are (in Dave’s view) such a problem for decarbonization.
Shift Key is hosted by Robinson Meyer, the founding executive editor of Heatmap News.
Subscribe to “Shift Key” and find this episode on Apple Podcasts, Spotify, Amazon, YouTube, or wherever you get your podcasts.
You can also add the show’s RSS feed to your podcast app to follow us directly.
Here is an excerpt from their conversation:
Robinson Meyer:
Will this decline in utility political clout continue, or is this limited to this moment? Then if [BAAJA] doesn’t pass, are utilities going to close ranks and there won’t be another chance to take on utility power again?
David Pomerantz:
That’s kind of the million-dollar political question, from where I sit. On the one hand, unfortunately for ratepayers and customers, I don’t see investors and utilities having, like, a sudden change of heart and doing the things that they could and should do to arrest inflation and lower people’s bills. I do want to make it clear, like, they could do that. There are a lot of things that utilities could do if they weren’t looking at their next quarterly returns and just sort of maxing cap-ex, to bring people's bills down. Like, you could see that on the public side of the sector. I don’t think they will. I think their incentives are too perverse. And because of that, I think they’re going to keep getting themselves into trouble politically by going for rate increases and bill increases. And so I see that, at least for the next couple of years, as being somewhat secular. Some of it, by the way, is actually not wrong, right? Like, the grid is aging, and they do need to spend money. That’s why it’s unfortunate that they’re not saving money where they can because they are kind of in a pickle there. So that part I see as sticking around at the same time on the other side of that argument.
I think one thing doing this work has taught me is that these companies have been around for over 100 years. If you read some of the history on some of the big political fights that investors and utilities were having in the 1930s, they do the exact same things now. They spent on propaganda. They route their money through trade associations. They recruit other parts of the political economy, like labor, to back them with politicians for whom that constituency is important. This is something EPI has really tried to investigate and highlight and ultimately address — they have, at the end of the day, a publicly subsidized pool of ratepayer money to spend on politics that almost no other industry has. And so I think they will regroup. Counting them out is probably a mistake.
You can find a full transcript of the episode here.
Mentioned:
The Senate’s Big Bipartisan Permitting Deal, Explained
The Senate Permitting Deal Contains a Data Center Double Tap
The Long, Strange Success Story of America’s Biggest Clean Energy Project
Previously on Shift Key: What a Permitting Reform Deal Could Look Like
This episode of Shift Key is sponsored by ...
Formed through a joint venture between Wärtsilä and RCT Solutions, Valo helps utilities, independent power producers, and developers navigate market and grid complexity without sacrificing system performance. Learn more at valoenergy.com.
RE+ 26 is the largest clean energy event in North America, happening November 16th through 19th at the Las Vegas Convention Center. Register at re-plus.com and use code SHIFTKEY20 to save 20% off a Full Conference pass.
Every year Giving Green researches the top climate nonprofits and sends 100% of every dollar donated to its Giving Green Fund straight to them. Make your first gift before the new year, and it will be matched up to $1,000. Go to GivingGreen.earth/Shift.
Music for Shift Key is by Adam Kromelow.