You’re out of free articles.
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
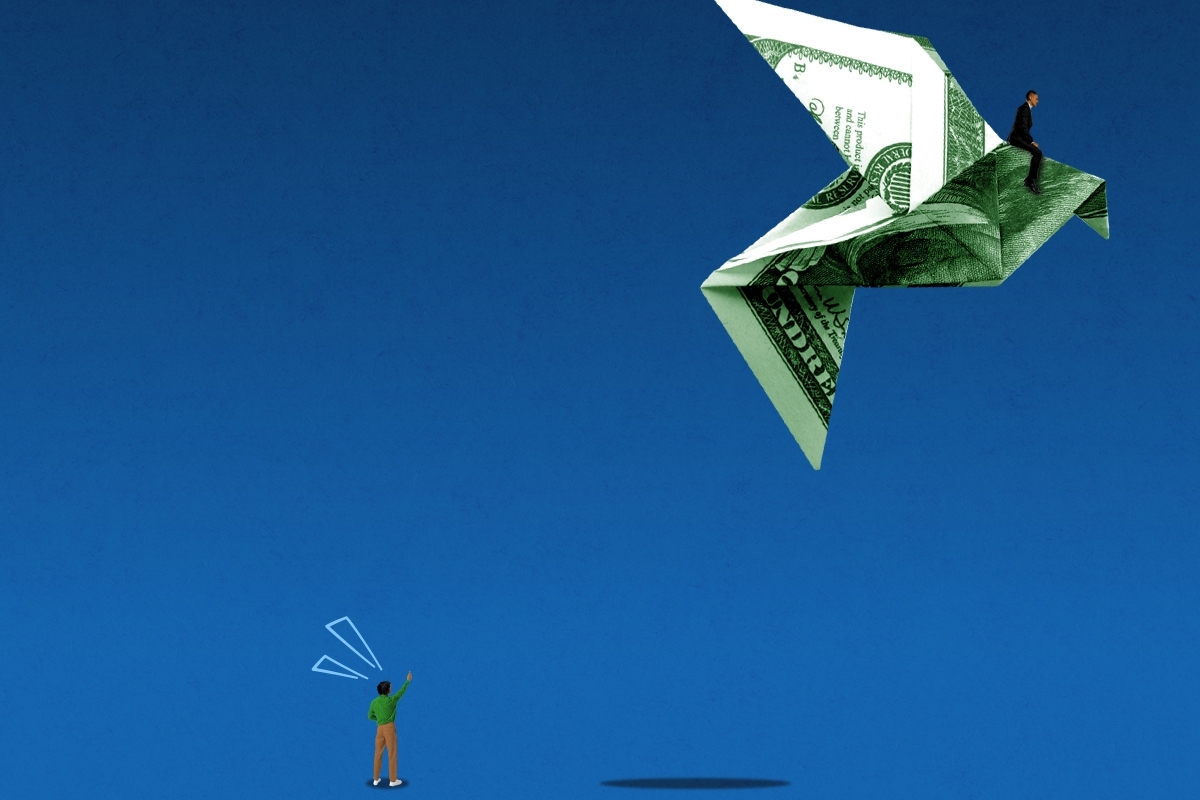
In an age of uncertainty, investors want proven technologies.

When Trump won a second term, nobody quite knew exactly what havoc he would wreak on the climate tech industry — only that its prospects looked deeply unstable. After all, he’d alternately derided and praised electric vehicles, accused offshore wind turbines of killing whales, and described himself as “a big fan of solar” — save for its supposed harm to the bunnies — all while rallying supporters around the consistent refrain of “drill, baby, drill.”
At the same time, a number of key technologies continued moving down the cost curve, supportive policy or no. This collision of climate tech antipathy and maturing technology is already reshaping the funding landscape. New reports from Sightline Climate, Silicon Valley Bank, and J.P. Morgan point to a clear bifurcation in the industry: While well-capitalized investors and more established climate tech companies continue to raise sizable funds and advance large-scale projects, much of the venture ecosystem that backs earlier-stage solutions is struggling to keep up.
The headline numbers — which look strong at first glance — help obscure that reality. Sightline Climate’s Dry Powder and New Funds report, for instance, shows investors raising a record $92 billion in new climate-focused capital across 179 funds last year. But 77% of that total was concentrated among the largest players, institutional heavyweights like Brookfield Asset Management, Copenhagen Infrastructure Partners, and Energy Capital Partners, which tend to back proven technologies such as utility-scale solar, wind, and battery projects.
“A lot of infrastructure funds are very comfortable saying, Yeah, I’m going to do wind and solar. I know how that works. I can see the project finance there. All good,” Julia Attwood, Sightline’s head of research, said on a webinar about the firm’s report.
Meanwhile, the proportion of U.S. investment going to seed and Series A companies fell for the first time in about a decade, according to Silicon Valley Bank’s Future of Climate Tech report, bad news for less mature but critical technologies like carbon capture, green steel, low-carbon cement, and agricultural decarbonization. These remain the domain of more risk-tolerant early-stage venture investors, whose share of total funding raised is similarly shrinking, dropping from about 20% in 2021 to under 8% last year, according to Sightline. That’s due to both a decline in VC fundraising — the average fund size dropped from $174 million in 2024 to $160 million in 2025 — as well as infrastructure’s share of the pie growing as the industry matures.
Capital concentration also shows up within early-stage venture itself. While Silicon Valley Bank’s topline numbers show startup valuations increasing at every stage from seed to Series C and beyond, “there’s clearly a story behind that where the top performers are doing really well and a lot of the longer tail are still scraping to keep up,” Jordan Kanis, Silicon Valley Bank’s managing director of climate technology, told me. “There’s still money flowing into early stage companies. I think there’s more selectivity. It’s a higher bar.”
That selectivity has become a necessity, as investors struggle to raise fresh capital from their limited partners in a politically volatile environment, in which affordability and energy security have become the name of the game and the word “climate” is all but forbidden. Even before Trump’s second term, LPs were facing a liquidity crunch, as infrastructure-heavy climate tech companies often take a decade or more to exit and return capital to investors. So until those IPOs or acquisitions accelerate, many LPs will likely remain cautious about ponying up additional capital.
This year could be a turning point on that front, however, with nuclear startup X-energy going public last month at a valuation of nearly $12 billion, and geothermal unicorn Fervo Energy gearing up for its pending IPO. “Nothing gets this fired up more than some really good exits,” Andrew Beebe, managing director at Obvious Ventures, told me, referring to the climate tech ecosystem at large. “That’s going to get people talking a lot about the opportunities in the space.”
Obvious, which invests in climate tech companies but also those focused on “human health” and “economic health,” is one of the few venture investors to bring in fresh capital recently, raising about $360 million in January for its fifth fund. Last year, only 39% of climate-focused VC funds that were actively raising were able to close, according to Sightline Climate’s data, compared to 73% of mature infrastructure funds and 60% of growth funds.
Beebe said that for a well-known firm like Obvious, which has been investing in this space for over a decade, “we did not find it that hard” to raise, explaining that “LPs today are favoring experienced teams with track records.” The firm’s diversification beyond climate also might have been a boon, he said. And there’s always the possibility that “there were just too many funds, and we’re going to see a thinning of the field” in both climate and the venture landscape at large.
Indeed, the broader venture market mirrors many of these trends, indicating there’s more than just political sentiment — or even climate industry maturation — driving capital concentration at the top. For one, the entire venture industry contracted after 2022, as post-pandemic interest rates rose, money got more expensive, and valuations plummeted across the board. That’s led investors across all categories to hold off until companies demonstrate significant proof of traction.
“When we look at tech firms and look at how much revenue the median Series A company has in 2021 and compare that to what they had in 2025, it’s double,” Eli Oftedal, a principal researcher at Silicon Valley Bank, told me, meaning Series A companies are bringing in much more revenue than they were five years ago. “Investor expectations are higher across the board, not just in climate, and that’s a pretty clear indication of the whole ecosystem changing to request a higher level from founders.”
At the same time, revenue growth rates have slowed, elongating the time it takes startups to move from one round to the next. This environment has LPs and investors placing big bets on a few prosperous industries that seem almost guaranteed to generate returns, whether it’s solar and wind or artificial intelligence companies. For instance, OpenAI and Anthropic raised $40 billion and $13 billion last year, respectively, accounting for 14% of total global venture investment in 2025.
That type of focused hype is redirecting attention from generalist investors — who might have otherwise funded climate tech — toward more AI-centric bets. But the AI boom and the accompanying data center buildout are also behind many of today’s strongest climate tech deals, with surging electricity demand fueling investment in clean energy and gridtech startups as hyperscalers look to meet their ambitious — and perhaps impractical — climate targets.
“If you’re investing in the clean baseload energy and power part of climate tech, there’s so many dollars that need to be deployed to bring these companies to scale, and they’re viable today,” Robert Keepers, head of climate tech at J.P. Morgan Commercial Banking, told me. “Funds that are focusing on that part of the sector are doing really well.”
But the result is also a dynamic that disproportionately favors the energy sector, the most mature segment of the climate tech ecosystem. Last year, three quarters of new capital raised by climate-focused funds was earmarked for energy investments, leaving sectors including transportation, industry, and agriculture increasingly cut off from capital
If the trend continues, it could create a pipeline problem. Infrastructure investors would keep scaling solar and wind farms alongside politically favored tech like nuclear and geothermal, while a dwindling supply of venture capital leaves fewer next-generation companies able to graduate into that queue. “If they don’t have VC commercializing and providing [first-of-a-kind] funding for a bunch of the new tech then you’re just going to see more and more concentration in a few technologies, and you won’t really have that growth of a brand new market,” Attwood explained on the call.
As of now, however, that’s just speculation. As Attwood noted, Sightline’s data is based on climate tech funds that have already closed. “There’s another $200 billion out there that has not closed yet,” she emphasized. “So if all of that money is still in the pipeline, is still moving through, and could reach close fairly soon, that’s a huge indicator that there is still appetite to fund climate.”
With the historic level of electricity demand growth, Keepers told me “there’s never been this much momentum in the space.” And the climate issue certainly isn’t going away anytime soon. As Silicon Valley Bank’s report notes, over the past decade, billion-dollar climate and weather disasters alone have caused $1.5 trillion in direct damages — a figure that excludes smaller disasters and doesn’t even begin to capture the catastrophes’ broader economic ripple effects.
“We’re tackling a problem that some people still don’t really see, and we see with great clarity. So that’s where you make a lot of money,” Beebe told me. “Unlike some other cycles like blockchain, or crypto, or even enterprise SaaS, this cycle doesn’t come and go. It is a one way street. It will continue to become a bigger and bigger opportunity.”
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
A conversation with the Guardrails Alliance’s Shaunna Thomas.
This week’s Q&A is with Shaunna Thomas of the Democrat-allied super PAC Guardrails Alliance, which describes itself as “not anti-technology” but supportive of AI “rules, accountability, and a government that actually represents the public.” Part of that AI accountability they’re calling for is on data centers.
After the midterms, Guardrails Alliance sent a memorandum to all House and Senate Democratic offices arguing for AI and data center accountability to be a key part of their message and plans heading into the new Congress. Described as a “playbook for how to understand and channel anxieties about AI and data centers,” the document laid out “key narratives” that they said voters who care about these issues want to see reflected and echoed by their politics. They said the push against data centers could help Democrats build more lasting political power.
I reached out and asked if Thomas could explain further what all of this means to my readers. She kindly obliged.
The following conversation was lightly edited for clarity.
Let’s start with the elections. What were your takeaways when it came to what voters want to see on data centers?
I think the elections were a rebuke of the status quo on a number of fronts. We saw across the board that people are frustrated with what amounts to legalized corruption and the forcing without consent of new technology, and new infrastructure to support a technology that they didn’t ask for in ways that are harmful to their lives and the country.
What we saw in polling is that the data center backlash is one of the most bipartisan political issues of our time, driven by everything from noise pollution to rate hikes to Big Tech trying to steamroll state and local governments. Americans are sick and tired of the AI industry trying to control our lives by building data centers in our communities, which goes along with trying to control our data and who represents us in government. The AI industry was also trying to spend a lot on elections trying to control the outcome.
When we dig deeper on all that, it’s not just about elections. They’re seeing this unholy alliance between Big Tech and the Trump administration.
In the post-election analysis laid out in that memo, you explain these key narratives that you think Democrats should pick up against the tech sector. Can you explain how you developed these?
What we dug into during the primaries and the lead-up to the general election was questions in focus groups and polling with Republicans and Democrats about what was behind the frustration. Is this just about buildings they don’t want in their backyard or is this connected to AI and bigger picture concerns over who makes choices? About control? The data centers people were most opposed to were data centers specifically for AI, which was a really important indicator it was both/and.
We then started to talk to voters in Ohio and Iowa and Michigan about what they’d want to see in terms of changes, in terms of new leadership, how they would want to see this framed. What was appealing? We tested a number of frames and these key narratives are a compilation of that data. So for example, a key narrative says, The AI oligarchs and their political allies are wildly out of step with a supermajority of the public. There’s also sample messaging under it in the memo. And it’s a reflection of the sentiment and the tone and the language a lot of people used when they got into robust conversations about what they’re really concerned about or what they want to see their leaders doing differently.
Can you say more about these focus groups? And can you say more about what you saw in terms of bipartisan shared concern around not just data centers but these messages you’re bringing up?
I can tell you about some of the key findings of the focus groups we did in Michigan and Ohio and Iowa in August and September. People are generally open to the idea AI can have some benefit to their lives, and they’re open to using it personally. But everyone we talked to expressed some concern about the pace it was being developed. You can see technology having value but also see there’s no regulation in place or guardrails around the technology itself.
Most people we spoke to expressed concerns about how the technology has been affecting society and the environment — that came up a lot in data center conversations. People are also concerned about the role chatbots could have in their children’s lives, and that AI could replace teachers.
It’s also a lot of concern about and a lack of confidence in either government regulators or AI companies to properly regulate the technology. You saw more support for regulators at the state level and people deeply opposed to federal pre-emption, because they see more evidence of democracy working at the state level as opposed to the federal level.
People express mixed reviews about the specific policy solutions. What we’re seeing is people see AI as a vehicle for a small handful to amass more wealth and power. I don’t think we have had enough of a robust debate about how you deal with that problem.
So, on that point in particular, I want to drill down. What do we know about what voters want to see? What does accountability or guardrails look like to them?
First of all, there’s blanket support for federal regulations in general to deal with the way the technology is developed and deployed. We see a lot of clarity from voters about the fact they may not have a lot of confidence the federal government will step in. They want to see it.
When it comes to the economy, where there’s still broad public support is taxing billionaires and CEOs of these companies and raising the minimum wage and raising the social safety net. People’s interest in seeing that move forward has been growing in intensity.
On AI specifically, people don’t want to have a conversation about distribution of wealth without a conversation about distribution of power. They don’t want to be bribed to accept the acceleration of AI in their lives. They want to know that the power of those companies to do what they’re doing is going to be significantly limited and safety guardrails are put in place to keep us all safe from what the new technology is capable of.
I think once the safety conversation is step one. Step two is the conversation about how you distribute wealth from a technology built on other people’s labor and intellectual property.
On the concern about bribes, we’ve been reporting on Trump’s call for cash payments to communities to accept data centers. Are you telling me proposals like that might not be a good political strategy?
It was precisely because Trump was talking about it that we heard it brought up in focus groups, and how it was described was that voters may get some short term incentive to accept a technology they don’t trust is designed to help them fundamentally. They believe it is being deployed to more deeply consolidate power and wealth. And they don’t want that. When the president or a big AI company says they agree with it, it’ll have an impact on how the idea is perceived.
It has to also be coupled with a set of policies that are putting democratic governance over the technology itself before its deployment. People want to see technology isn’t going to continue to advance without guardrails.
Distinct from Trump’s data center dividend, some policymakers have suggested a “data dividend” — a distribution of wealth from the usage of AI products because they’re using people’s data. That’s more of what we’re talking about.
What do we know about what the public wants to see regarding data centers?
It’s important we recognize local leaders have had demands driven by their local communities. But as a structural matter, the public sees slowing down data centers as a mechanism for slowing down the project of AI generally. It remains an open question about how you do that.
There are federal policymakers working on a set of solutions that could create more space for people at the local level to be in the driver’s seat on when, how, or if data centers get built. I think we’ll see more proposals on that front.
So where do you think this conversation goes next?
I would expect the public to continue to make demands from policymakers and I would expect the Big Tech sector to continue down the path they’re going, which is, we were always Democrats and pro-regulation all the time. This will look like policies resembling always being okay with regulation but actually avoid putting checks on their power. And that’ll mean the public has even more at stake and the government has an even bigger obligation to make sure AI is deployed for public benefit as opposed to for the profits of a few companies and CEOs.
Plus more of the week’s biggest development fights.
1. New York City — We have a new must-watch offshore wind lawsuit with potential implications for the entire sector — and this time, it’s from lobstermen seeking damages.
2. Hinds County, Mississippi — The largest proposed solar farm in Mississippi is moving forward after an appeals court rejected arguments from aggrieved local residents that it had been improperly approved.
3. Dakota County, Minnesota — I’m scrutinizing a lawsuit against a data center developer centering on allegedly improper permitting of its cooling technology.
4. Polk County, Florida — Will the Sunshine State remain a challenging place for data centers after Ron DeSantis? A test case could reveal the future quite quickly.
Trump’s “data center dividend” appears to have backfired. Our latest poll results help explain why.
This year’s midterm elections called into question the efficacy of a push to pay local residents directly in exchange for building data centers.
Before the elections, I profiled the campaign for politicians to embrace the data center “dividend,” a policy idea modeled off Alaska’s Permanent Fund, which doles out checks to residents from profits off state oil, gas and mineral royalties. The Bitcoin Policy Institute, a tech policy think tank, was one of the first to trumpet the concept, but it was quickly taken up by President Donald Trump, who started raising it in speeches and on social media. “If companies want to make their Data Centers popular, pay the community, and/or individuals within the community, a ‘dividend,’” Trump posted to Truth Social on October 21.
Clearly the idea didn’t stop the bleeding. Democrats trounced Trump’s party in the midterms on a message that was heavy on attacks against data centers. But that still doesn’t explain why direct payments did so little to move the American public.
A Heatmap Pro poll conducted in early-to-mid October, right before the midterm elections, gives us an answer. As part of a broader survey of 2,500 registered voters, we asked about the idea — what we believe to be the first independent poll on direct payments for data centers by a news organization. We asked respondents whether there was a specific dollar amount they’d accept as a one-time cash payment in exchange for a data center being built near them. We also gave them the option to say no amount of money was sufficient.
Shockingly, a majority of people surveyed said they’d reject the data center cash payment in any amount. Among those who said they’d actually take the money, the median figure was around $10,000. The average was a whopping $146,000, skewed by the number of people who wrote $999,999, the maximum allowed by the survey.
This tracks what we’re seeing play out in communities where developers have tried this idea. In Hazle Township, Pennsylvania, NorthPoint — developer of an Amazon-linked data center project — proposed $10,000 cash payments to residents, no catch. Residents compared it to a bribe. In De Soto, Kansas, data center developer Digital Realty is offering annual $1,000 tax credits for a decade to neighbors of its proposed data center project. That proposal has been reportedly met with mixed reviews, too.
Clearly one of the problems here is that data centers not only face public perception issues around their local impacts, but are also more broadly associated with systemic inequality in the U.S. economy. The same Heatmap Pro survey found that a majority of voters believed AI companies have more control over the government than the oil and gas industry, pharmaceutical companies, banks, or other large industries.
Shaunna Thomas, executive director of Democratic-allied super PAC Guardrails Alliance, told me that during the campaign season they found that residents often associated the dividends with bribes, and that the president’s support for direct payments ultimately fed into voter sentiments about the tech sector controlling the government and society.
“People don’t want to have a conversation about distribution of wealth disconnected from a conversation about distribution of power,” Thomas said. “Specifically because Trump was saying that, we started hearing from voters in focus groups that it didn’t work for them. They’re hearing it as a bribe. They’re hearing they may get some sort of short-term economic or financial incentive to accept a technology they don’t trust is designed to help them.”
The Heatmap Pro survey results about cash payments ultimately reveal how emotionally driven the data center debate has become, said Sam Lyman of the Bitcoin Policy Institute. I asked Lyman to respond to the results because I thought they called into question the political effectiveness of the proposal we’d discussed months earlier. Lyman stipulated that he thinks the one-time payment nature of the question may have undermined the results, saying he prefers the dividends be paid out “in perpetuity.” But he acknowledged they also show “there’s still a lot of education to be done on data centers, what they do, and the impacts they have on the places where they’re built.”
“I think there’s a lot of Americans out there who have legitimate concerns that the future economy doesn’t include them. That’s something that needs to be addressed,” said Lyman, who said he laid part of the blame on what he called “irresponsible rhetoric” from AI industry executives about their technology’s impacts on society. “With data center dividends, the idea behind this policy is to help Americans understand the AI economy includes them. To give them a very material stake in that economy as it gets built out, especially in the rural communities that make data centers possible in the first place.”