You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
The new rules are complicated. Here’s how to make sense of them if you’re shopping for an electric vehicle.

The Department of Treasury published new rules last year that will determine which new electric vehicles, purchased for personal use, will qualify for a $7,500 tax credit. They went into effect on April 18, 2023, and last for the next decade or so.
These new tax credit rules are complicated. The list of cars that qualify for the new tax credit can change from year to year — and even month to month. Many buyers in the EV market might have a few questions, including: Should I buy that new car now, or should I wait? Which cars qualify for the current tax credit, and which ones will earn the new one?
This is Heatmap’s guide to the new tax credit, why it matters, and what to keep in mind as you go EV shopping.
If you’re an ordinary American buying a brand-new EV to run errands and pick up the kids, these new rules apply to you. They will determine which cars you can get a federally funded discount on.
If you’re not buying a new car for personal use — because you’re getting it for your business, say, or because you’re buying a used EV — these new rules don’t apply to you. But you may qualify for other new subsidies. We get into those below.
And even if you are in that first category, you may discover it’s much cheaper to lease a new EV instead of buying it outright. We get into why below, too.
They completely change how the United States approaches the EV industry.
During the Bush and Obama administrations, the U.S. was focused mostly on getting automakers to begin to experiment with EVs. So it discounted the first 200,000 or so electric vehicles that each manufacturer sold by up to $7,500. If a company had cumulatively sold more than that number over time, as Tesla and General Motors eventually did, then the discount expired. By 2022, that had led to a peculiar situation where foreign automakers, such as Hyundai, could use the subsidy, while some of the largest American automakers couldn’t.
Now, U.S. policy is focused on two goals: (1) building up a domestic supply chain for EVs and (2) getting more EVs on the road. So the tax break is completely uncapped — any automaker can use it as many times as possible if they meet the criteria.
But many new requirements apply: Only cars that undergo final assembly in North America will qualify for any of the tax credit. Then, cars with a battery that was more than 50% made in North America will qualify for a $3,750 subsidy. And cars where at least 40% of the “critical minerals” used come from the U.S. or a country with whom we have a free-trade agreement will qualify for another $3,750 subsidy.
Those percentage-based requirements will ramp up over time. By 2029, for instance, 100% of a car’s battery and battery components must be made in North America.
Because Congress said so. The Inflation Reduction Act, which Democratic majorities in the House and Senate passed last year, mandated this change to the EV tax credit as part of its broad expansion of American climate policy.
Initially, fewer EVs will receive a subsidy under the new rules, Biden officials say. On a press call with reporters, a senior Treasury official argued that more cars will eventually qualify under the new rules than qualified under the old ones.
This year, at least 15 car or light trucks will receive some or all of the credit. Only some of those vehicles will qualify for the full $7,500 tax credit; some will qualify for a partial $3,750 tax credit. Here is the full list of qualifying models, along with the amount of the tax credit that they will earn:
• Audi Q5 TFSI e Quattro PHEV ($3,750)
• Cadillac LYRIQ ($7,500)
• Chevrolet Bolt ($7,500)
• Chevrolet Bolt EUV ($7,500)
• Chrysler Pacifica PHEV ($7,500)
• Ford Escape Plug-in Hybrid ($3,750)
• Ford F-150 Lightning, Standard & Extended Range ($7,500)
• Jeep Wrangler PHEV 4xe ($3,750)
• Jeep Grand Cherokee PHEV 4xe ($3,750)
• Lincoln Corsair Grand Touring ($3,750)
• Rivian R1S, Dual Large & Quad Large ($3,750)
• Rivian R1T, Dual Large, Dual Max, & Quad Large ($3,750)
• Tesla Model X Long Range ($7,500)
• Tesla Model 3 Performance ($7,500)
• Tesla Model 3 Long Range AWD ($3,500)
• Tesla Model Y AWD, Rear-Wheel Drive, & Performance ($7,500)
• Volkswagen ID.4 AWD PRO, PRO, S, & Standard ($7,500)
Some vehicles that earned the full tax credit in 2023, such as the Ford Mustang Mach E, don’t qualify for any benefit as of January 2, 2024.
Yes. A few examples: The Hummer EV, which costs more than $110,000 a piece, won’t qualify for either the new or old tax credit — it’s too expensive. And the Polestar 2 won’t qualify because it’s assembled in China.
Yes. Starting this year, the U.S. is preventing cars that receive too much manufacturing input from a “foreign entity of concern” — that is, China — from qualifying for any of the tax credit. This has reduced the number of vehicles that qualify for the $7,500 bonus.
This year, the government will also allow buyers to refund their EV tax credit at the dealership. That means buyers can now get up to a $7,500 discount at the moment when they buy their car instead of waiting until they file their taxes in the following year.
Yes. A married couple must have an adjusted gross income of less than $300,000 a year, and a single filer must have an AGI of less than $150,000 a year, to qualify for any aspect of the subsidy. A head-of-household must have an income of less than $225,000 a year.
Yes. Under the proposed rule, cars must have an MSRP below $55,000 to qualify for the credit. Vans, pickup trucks, and SUVs must have an MSRP below $80,000.
Yes. The Inflation Reduction Act also included a new $7,500 tax credit for EVs used for any commercial purpose. The Treasury Department is expected to interpret that provision to cover leasing, but it hasn’t announced the guidelines for that rule yet, so we don’t know for sure.
But the provision will probably tilt new EV drivers toward leasing their car rather than buying it outright, because the dealer should — emphasis on should — offer relative discounts on leasing vehicles as compared to buying them.
Yes. There’s also a new $4,000 tax credit for buying a used EV that costs $25,000 or less. It went into effect on January 1, 2023, so you can go ahead and use it today.
But note that it has even stricter income limits: Married couples can only take advantage of it if they make $150,000 or less, and other filers if they make $75,000 or less.
Here’s the list of cars that qualified for the $7,500 tax credit before April 18, 2023, according to the Department of Energy.
• Audi Q5 TFSI e Quattro (PHEV)
• BMW 330e *
• BMW X5 xDrive45e**
• Cadillac Lyriq
• Chevrolet Bolt
• Chevrolet Bolt EUV
• Chevrolet Silverado EV
• Chrysler Pacifica PHEV
• Ford E-Transit
• Ford Escape Plug-In Hybrid *
• Ford F-150 Lightning
• Ford Mustang Mach-E
• Genesis Electrified GV70
• Jeep Grand Cherokee 4xe
• Jeep Wrangler 4xe
• Lincoln Aviator Grand Touring *
• Lincoln Corsair Grand Touring *
• Nissan Leaf
• Nissan Leaf (S, SL, SV, and Plus models)
• Rivian R1S
• Rivian R1T
• Tesla Model 3 Long Range
• Tesla Model 3 Performance
• Tesla Model 3 RWD
• Tesla Model Y All-Wheel Drive
• Tesla Model Y Long Range
• Tesla Model Y Performance
• Volkswagen ID.4
• Volkswagen ID.4 AWD, Pro, and S models
• Volvo S60 PHEV *
• Volvo S60 Extended Range
• Volvo S60 T8 Recharge (Extended Range)
* These cars don’t qualify for the full $7,500 subsidy, although they all receive at least a $5,400 tax credit.
** Only some BMW X5 xDrive45e vehicles qualify — it depends where the car was made. Check the VIN or ask the dealership to confirm it was made in North America before buying.
This story was originally published on March 31, 2023. It was last updated on March 5, 2024, at 10:00 a.m. ET.
Get the best of Heatmap delivered to your inbox:
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
The state’s market is in such disarray, a Democrat actually stands a shot at winning the office.
In the waning weeks of the midterm election cycle, the question of who will serve as Oklahoma’s next insurance commissioner is unlikely to be a topic of intense speculation at dinner tables around the country — or in Oklahoma, for that matter.
For one thing, it’s about as down-ballot a race as you can get, another bubble to be filled in alongside state treasurer and superintendent of public instruction. For another, it’s difficult to imagine it will be much of a competition: It’s been two decades since a Democrat last won statewide office in Oklahoma.
But if there ever were a race for an upset, this would be it. Oklahoma is one of the most expensive places in the country to purchase home insurance, with an average annual premium in 2024 of over $5,819 for $350,000 in dwelling coverage — well above the national average of $3,303 and behind only Florida and Louisiana, per the most recent numbers from the Consumer Federation of America. That’s even more staggering given the local cost of living: Oklahomans spend more of their median household income, $65,039, than residents in any other state on home insurance — almost 9%.
When it comes to arguing for greater industry regulation, Democrats are typically on more comfortable footing against their conservative counterparts. Craig MacIntyre, the Democrat in the Oklahoma insurance commissioner race, has promised to use the state’s new “file and wait” law to review rate increase requests closely before they’re implemented. But in a strange reversal of roles, Republican candidate Bob Sullivan won a four-way primary and subsequent runoff that centered on the conservatives arguing over who would be the toughest industry regulator.
The topsy-turvy politics don’t stop there. Republicans in the state have also called out the impacts of extreme weather on premiums, albeit without going quite so far as to blame climate change. Sullivan unabashedly models himself after Trump (“Make insurance fair again!” “Drain the insurance swamp!”) but also set himself apart from the competition by challenging the narrative that severe weather — not climate change, per se — is the primary explanation for the state’s high rates — putting him more in line with the Democrat, who almost hasn’t mentioned weather at all.
It’s a notable break. Extreme weather has long been the go-to explanation for Republicans about the state’s high homeowners’ premiums. “We get our fair share of weather in Oklahoma,” the state’s outgoing, term-limited insurance commissioner Glen Mulready told me. “We’re right next to Texas and Kansas and Arkansas, so they get the same weather we do — that’s the quote we hear all the time,” he added, “which is just simply not true.”
Oklahoma Watch, a nonprofit investigative newsroom that reports extensively on the state’s insurance crisis, has suggested that the insurance industry and its allies in the state might be using hail in particular “as a scapegoat to justify high rates,” given that other states with high instances of hail pay far less in premiums.
It’s true, though, that Oklahoma seems to be a particularly bad place for hail, which is responsible for an estimated $1 billion in annual property and crop damages in the United States. In most of the state, even at the tiny geographical scale of an individual roof, you have about a one-in-10 chance each year of seeing two-inch or larger hail, Ian Giammanco, a lead research meteorologist at the Insurance Institute for Business & Home Safety, told me. Verisk, a risk assessment firm, also found that over the last four years, nearly 50% of Oklahoma roofs were hit by severe hail — the highest rate nationwide.
"Hail gets overlooked, but it’s a huge contributor to rising insurance costs," Michael DeLong, a researcher at the Consumer Federation of America, told me.
Hail’s climate signal isn’t obvious to researchers yet. “We haven’t seen any observational fingerprints that hail appreciably changes” in a warming world, Giammanco said. But while the number of days with severe hail across the U.S. hasn’t changed much, “there may be an upswing in severity that’s just starting to be able to be observed,” he noted. Warmer air, for example, may raise the potential for “really big hail, while the lower end may actually decline.”
Hail is one piece of Oklahoma’s nasty extreme weather cornucopia. Increasingly frequent wildfires, extreme heat, and severe storms and tornadoes also threaten homes (not to mention seismic activity from injecting fossil fuel wastewater underground). Between 1980 and 2024, the state averaged about 2.6 weather disasters per year that cost more than $1 billion in damages, adjusted for inflation, but in the last five years of that timeframe — 2020 to 2024 — it averaged six, including droughts, tornado outbreaks, and blizzards. (The Trump administration retired the National Centers for Environmental Information’s U.S. Billion-Dollar Weather and Climate Disasters database last year, so there isn’t more recent data.)
But the affordability problems don’t exist in a vacuum, and are compounded by historic infrastructure and materials choices. New home construction, for example, peaked at an average of over 2,800 square feet in 2015, meaning a bigger target for hail. “We have lots of field observations of 300 hailstones in a square foot area,” Giammanco told me; in a given storm, more than 800,000 might pummel a house. And while slate and tile roofs — popular construction before the post-war suburban boom — withstand hail well, they’re also slow and difficult to install. Asphalt shingling, on the other hand, is cheap, easy, and popular — and “highly vulnerable to hail, especially as it ages,” Giammanco added.
Republicans have traditionally argued that relatively little can be done about Oklahoma’s high homeowners’ insurance rates, given the state’s weather and larger nationwide trends in inflation-driven rebuilding costs and reinsurance. Karen Collins of the American Property Casualty Insurance Association, an industry advocacy group, further warned the Oklahoma House of Representatives in a hearing last year that cracking down on the industry could drive insurers out of the state. “We’ve seen … when government regulates directly or indirectly price controls on markets with escalating losses, it does turn those affordability challenges into an availability crisis,” she said.
When I asked the APCIA for comment, Walter Gonzalez, the assistant vice president of state government relations, told me in an email that “the story in Oklahoma today is not accelerating rate increases. It’s decelerating rate increases.” He pointed me to data showing that average rate increases among the state’s largest insurers fell from 16.4% in 2023 to 5.3% by 2025, and they’re at just 2.9% so far in 2026. Still, what homeowners actually pay is a different story: Oklahoma was among six states nationally to see homeowners’ premiums increase by more than 20% in 2025, an Insurify report found.
Gonzalez also pointed out that insurers paid close to or more in losses and expenses than they made in premiums over the past several years. In a blog post last year, Mulready wrote that Oklahoma’s top 20 insurers paid out $129 in claims for every $100 in premium collected in 2023, improving slightly to $97 in claims for every $100 in premiums collected in 2024. Critics of the industry, however, argue that focusing on underwriting losses elides a major source of profit for insurance companies: their investments.
Birny Birnbaum, the executive director of the Center for Economic Justice, a nonprofit that works on insurance advocacy for low-income and minority consumers, agreed that recent years have been challenging, especially after the reinsurance market retrenched and doubled prices following Florida storms in 2021 and 2022. But those rates have since stabilized and even declined, he said, yet “the insurance companies haven’t been reducing their premiums to reflect that.” Birnbaum has also been highly critical of Mulready’s approach — a hands-off, free-market approach to the insurance industry designed to spark competition and drive down prices. The insurance commissioner never denied a home insurance rate increase requested by an insurance company during his eight-year tenure, Mulready confirmed to me. Indeed, state statute barred him from doing so, he said. “There is no excessive rate in a competitive market,” he told me.
Birnbaum is not convinced. “For some reason, in virtually every state, the regulatory model is: If we allow the insurance companies to do whatever they want, that will bring them back into the market,” he said. He likened that argument to someone claiming that if we removed the Affordable Care Act’s preexisting condition protections, we’d ultimately end up with more people insured. If you heard that, “you’d go, ‘That’s the stupidest thing I ever heard in my life,’” he said, minus an expletive.
A loose regulatory environment might also mean that Oklahoma ends up subsidizing insurance in higher-risk, more tightly regulated ones. When national insurers take big losses in states like California that have stricter rules around rates, they may increase costs in states where it’s easier to do so, Ishita Sen, a professor of finance at Harvard Business School, told The New York Times. (Mulready has vehemently denied this on his podcast.)
Whether Oklahoma’s insurance market is truly competitive is even an open question to some. The insurance industry’s stance, like Mulready’s, is that the Oklahoma market is competitive, and “market-share concentration alone is not a measure of whether consumers have meaningful coverage choices.” And yet Allstate and State Farm alone represent a little over 40% of the market in Oklahoma.
Breaking with Mulready and the APCIA, Sullivan, the Republican candidate for commissioner, told E&E News that he plans to declare the state’s insurance market “non-competitive” if elected. (In an odd quirk of state law, there is no benchmark at which a market becomes competitive or not; it is entirely at the insurance commissioner’s discretion to declare it as such, so long as they hold a public hearing first.) MacIntyre, the Democrat dark horse, has described the market the same way.
Mulready told me that doing so would be a “mistake.” “The only data point that anyone ever presented to me only proved a competitive market,” he said, citing both the Herfindahl-Hirschman index and the four-firm concentration ratio, two popular forms of measurement. An investigation by Oklahoma Watch, however, found that the Oklahoma Insurance Department counted companies, not insurance groups, giving it rosier numbers on the HHI and CR4 scales and distorting the picture of a “potential oligopoly.” Birnbaum, the executive director for the Center of Economic Justice, told me that Oklahoma has “a complete seller’s market” and describing it as competitive is “laughable.”
That said, either choice for the office on the ballot in November would be “lightyears ahead of the current commissioner,” Birnbaum added. “The two candidates who are running both have better ideas and better values and better understanding of how insurance markets operate,” he said.
The winner will have his work cut out for him, though. Birnbaum stressed that the state has done little to assist in residential storm-proofing — one of the most important levers for bringing down costs — and the existing grant program for roof replacements is woefully insufficient. “It would take probably 50 years at this current level of funding to reach all these [homes], and none of these programs actually require insurance companies to have any skin in the game,” he told me, pointing to Wisconsin and Louisiana as examples of states that require insurance companies to offer discounts that incentivize loss prevention. (Mulready told me the first-come, first-serve grant program, which draws on unused funds of the Insurance Department, has helped replace around 700 roofs since it began in 2025).
In addition to reviewing rate increase requests and opening investigations into insurance companies’ claims payment processes, DeLong echoed the need for a much larger grant mitigation program. “Admittedly, that’s going to be expensive,” he conceded. “But it will be a lot more expensive if you don’t do anything.”
Mulready, meanwhile, laughed when I asked him for his advice for his successor. “That could be awhile,” he said. But he directed Sullivan or MacIntyre to “make decisions based on the data.” That’s what he did, he said. And the years, he mused, have gone fast.
Current conditions: Tropical Storm Simon is expected to intensify into a Category 4 storm as it tracks northeast into Mexico and Texas from the eastern Pacific • Further north in the Pacific, Tropical Storm Rachel is barreling toward Southern California and northern Mexico • Hurricane Isaias, the first major storm of the Atlantic hurricane season, is poised to make landfall as a Category 2 sometime between 8 p.m. ET and 1 a.m. and somewhere between Alabama’s Dauphin Island and Destin, Florida.
With swells topping 7 feet, Hurricane Isaias has forced almost two-thirds of U.S. oil output in the Gulf of Mexico offline, as the storm cuts a path through one of the most productive regions of the sea. Of the 371 manned drilling rigs in the Gulf, 121 were evacuated as of Thursday night, representing a third of all platforms, according to data from the Department of the Interior’s Bureau of Safety and Environmental Enforcement. But those rigs represent 1.3 million barrels per day of production, or roughly two-thirds of the Gulf’s crude output. Almost 1.2 million cubic feet per day of gas production, representing over 57% of U.S. production in the Gulf, is also offline.
Meanwhile, an attack on an oil tanker near Qatar, in an area The Wall Street Journal described as deep inside the Persian Gulf, has triggered fears among traders that Iran plans to broaden its strikes on vessels traveling beyond the Strait of Hormuz as the U.S. Navy loosens the Islamic Republic’s grasp over the narrow waterway. The price of Brent crude, the key global benchmark for oil, spiked more than 4%.
Last month, OpenAI provided investors with figures indicating that it expected to rake in $70 billion in annualized revenue as of the end of September. But updated financial documents show a $20 billion shortfall in the ChatGPT maker’s books. The gulf between the two numbers amounted to what the Financial Times called “a massive gap likely to damp optimism about the growth of AI demand” at a moment when investors are diverting billions from factories, healthcare, and housing into data center infrastructure.
Shares in companies whose values are linked to rising demand for electricity, such as the utility Constellation Energy, the nuclear startup Oklo, and the geothermal developer Fervo Energy dipped on Thursday, along with chipmakers Nvidia and Micron.
First off, let me just say, this is quite a stirring way for a national government to begin a press release touting a policy on energy efficiency: “The world is changing rapidly. In response, a confident Canada is choosing to build.” In the name of slashing bills in a country where 7 million households “still heat their homes with oil, propane, diesel, electric baseboards, or outdated furnaces,” Prime Minister Mark Carney launched a nearly $1.5 billion (in U.S. money, not loonies) program Thursday aimed at delivering a million home retrofits. The first part of the program will provide a national heat pump rebate of up to $12,000 for up to 820,000 households. The second part will support the Canada Mortgage and Housing Corporation and the Canada Infrastructure Bank to renovate 280,000 units over the next eight years to make homes more airtight and energy efficient. Combined, the measures are expected to reduce Canada’s emissions by 25 million metric tons, equal to taking 8.5 million cars off the road for a year.
While my colleague Katie Brigham had a really sharp guide to making your home more efficient back in 2024, when federal money was flowing into such projects through tax credits, U.S. support for home retrofits has fizzled since President Donald Trump returned to office. But as the effects of wildfires worsen, the market for DIY fire protection is booming, our colleague Jeva Lange wrote this week.
Sign up to receive Heatmap AM in your inbox every morning:
Polskie Elektrownie Jądrowe, the state-owned company building Poland’s first nuclear station on its Baltic coast, has begun ordering long-lead items for its planned trio of Westinghouse AP1000s. That typically involves heavy forgings and castings for pressure vessels, World Nuclear News reported, as well as steam turbines and generators, and marks a major milestone for a project that has started gaining new momentum after years of bureaucratic back and forth.
Urenco USA, the American division of the European nuclear fuel giant, announced Thursday that its new enrichment facility in the U.S. is now 75% complete. “We are consistently delivering new capacity to help fuel the U.S. nuclear industry and allied nations, and our teams are doing it ahead of schedule and on budget,” Jody Blackshear, Urenco USA’s managing director, said in a statement. “This experience will support our larger capacity programs in the years ahead as we look to increase our enrichment production by more than 50% to meet the needs of our customers with traditional and advanced reactors.”

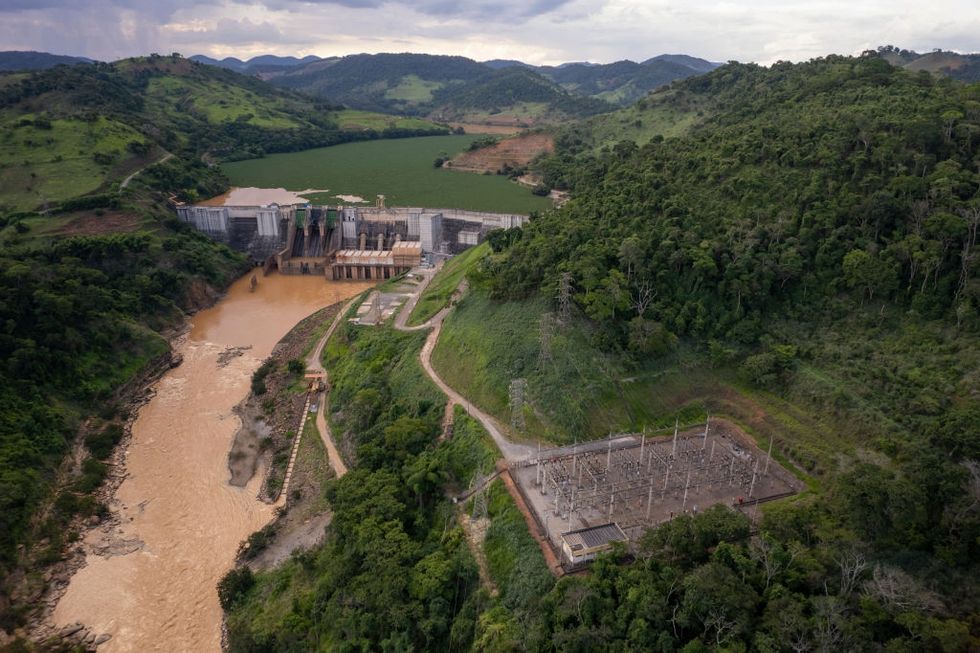
El Niño is here, and it’s threatening below-average rainfall across the northern parts of South America and above-average precipitation in areas such as southern Brazil, Paraguay, and Argentina. That, according to a new International Energy Agency analysis, poses a problem for a continent that depends heavily on hydropower for electricity. “While countries across the region have accumulated significant experience in managing hydrological stress due to El Niño and other climate-related risks, preparedness measures are often focused on specific events, rather than embedded within specific and comprehensive risk-management frameworks,” the report stated. “With climate-related disruptions likely to become more frequent and severe, there is increasing value in adopting a systematic approach to assessing and strengthening emergency preparedness for the electricity sector.” Among the steps the IEA recommended: More interregional power connections, more diverse power mixes, and more dispatchable power units.
QuantumScape has long been a frontrunner in the race to commercialize solid-state batteries that are lighter, more efficient, and ultimately cheaper than the lithium-ion packs that dominate the market today. Now, much like other developers who were previously locked into electric vehicles, the San Jose-based startup is getting into the data center business. On Thursday, the company announced the launch of its QS PowerBlock, a battery unit for behind-the-meter power users. The modular system “can deliver four times the power density and five times the runtime” of the data center industry’s current standards for batteries, the company said in a press release. “Solid-state battery technology offers an unmatched combination of energy, power, and safety for many different applications, from electric vehicles to AI data centers and beyond,” Siva Sivaram, QuantumScape’s chief executive, said in a statement.
Many nonprofits representing the environmental and climate movement are split.
This is Heatmap Daily, an evening digest written by our executive editor.
It’s now been just over a week since a gang of four bipartisan senators released the Bipartisan American Affordability and Jobs Act, or BAAJA. The permitting reform proposal would make too many changes to federal law to summarize cleanly here — read our explainer for that — but suffice it to say it creates a messy group of winners and losers. Utilities, data centers, and the Trump administration would lose; electricity ratepayers, clean energy companies, long-distance transmission lines, and natural gas pipeline builders win. (As would geothermal startups, virtual power plant providers, and a few other climate tech subsectors that my colleague Katie Brigham recently detailed.)
In the ensuing week since its release, we’ve gotten a better sense of the battle lines over the bill. The hardhat unions largely support the proposal (although the International Brotherhood of Electrical Workers, which is often aligned with utility executives, has stayed notably silent on it.) Clean energy trade groups, such as the American Clean Power Association, back it, too, as do fossil fuel lobbying groups, such as the American Petroleum Institute.
Groups representing the environmental and climate movement are more split, and some of the most influential nonprofits have yet to render a verdict. Earlier today, the Sierra Club published its first take on the proposal, which it described as a “hard look” at the bill. The Natural Resources Defense Council asked its own “hard questions” last Friday. Neither document rejects the proposal outright, although both are critical, and both suggest that future statements are coming.
To some degree, the statements say what you might expect: The groups like all the parts of the compromise that Democrats fought for (such as those that will encourage transmission) and dislike what Republicans wanted (such as those that will ease some pipeline permitting). That is what a compromise means — and for congressional procedure reasons too tedious to explain here, permitting reform will likely always need to be passed as a bipartisan compromise, because it will always need to overcome a 60-vote Senate filibuster.
The Sierra Club’s assessment divides the bill into “green flags,” which will make “long-overdue changes to protect consumers and level the playing field for proposed transmission,” such as by making it easier to plan long-distance power lines, protect ratepayers from utility and data center freeloading, and clarify who in the government can approve power lines. It also names four “red flags,” including the “hollowing out” of court authority over some permits, the removal of a Clean Water Act provision that lets governors block pipelines and power lines, and the option to delegate partial Endangered Species Act enforcement to state governments.
This is a helpful scheme, and I hope the Sierra Club continues using it. But I think it would be a mistake to analyze the bill solely through this metric, because it implicitly assumes we are starting from a neutral baseline — or that every additional “unit” of policy support, so to speak, helps an insurgent industry as much as it might aid an incumbent industry. To be clear: Although I’ve endorsed the idea of permitting reform in the past, I’ve been careful not to endorse or reject this particular permitting bill yet; I hope to write a more comprehensive take on this legislation — and whether I think it’s a good idea — before senators ultimately vote on it.
So for now, let me say that I think everyone should keep in mind that the baseline around U.S. energy permitting is, in fact, not neutral today. By this, I do not merely mean that natural gas pipelines already have a one-stop shop for federal permits, but transmission developers have to go hat in hand to every state government; nor that fracking is already carved out from some federal environmental review laws, but enhanced geothermal technology isn’t.
The mismatch goes deeper than that. Many of the discussions of the bill that I’ve seen seem to fear that the United States might witness some enormous and unprecedented fossil fuel buildout were the bill to pass. But make no mistake: We are already witnessing such a buildout. The United States is slated to add more than 60 gigawatts of new natural gas generation capacity by 2030 under its existing laws.
The existing system of laws, regulations, and procedures is failing to avert an enormous fossil fuel buildout. The existing system has proven itself completely inadequate to manage an era of electricity demand growth and the data center boom without surging fossil demand and sky-rocketing electricity prices. The existing system of laws is pushing hyperscalers and developers to burn natural gas on site, often through rudimentary jet engines.
And the existing system of laws has shown that fossil fuel consumers will go to great lengths to move and obtain fossil fuels, even when dedicated transport options like pipelines are not available. I’ve heard fears that the permitting bill will make it easier to build natural gas pipelines. But pipelines, to a dedicated artificial intelligence customer, are no constraint: Oracle is now delivering natural gas to some of its data centers by truck when pipeline capacity isn’t available.
There may be reasons for green groups to reject this deal. (And there may be reasons for Democratic lawmakers to support it anyway, even if environmental groups oppose it.) But the perfection of our current environmental and energy legal regime is not one of them. Even if your sole goal were to reduce the carbon emissions produced by the American energy system — even if you set aside the problems with cost, conventional pollution, or monopoly control — the current system sucks.