You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
The CEO of Climeworks argues that the buildout of technology to suck greenhouse gas from the air should be considered part of the cost of artificial intelligence.

Somewhere in Virginia, Texas, or Arizona, a data center is being commissioned this month that will draw more power than a small city. The server racks inside will train and run artificial intelligence models for years to come. And the electrons feeding it will, in all likelihood, come partly from natural gas — because that is what can be built fast enough to meet the demand.
AI is driving a major new wave of data center construction, and with it, a surge in demand for power and infrastructure. The International Energy Agency projects that the electricity consumption of global data centers could more than double to around 945 terawatt-hours by 2030, comparable to Japan’s entire electricity demand today.
That matters because much of the new electricity demand from data centers is still likely to be met by power sources where natural gas plays a central role. The backlog for new combined-cycle gas turbines — the more efficient type of gas plant, which generates electricity from both a gas turbine and the heat it produces — already stretches to five years. As a result, some data centers are turning instead to single-cycle gas turbines, which can be deployed more quickly but are even more carbon-intensive. In any case, that means fossil-fuel use for this generation of digital infrastructure is already largely locked in. Some of the emissions that follow can be reduced through efficiency and grid decarbonization, but a significant share will persist for years to come. I believe that closing this gap must be the job of carbon removal.
Carbon removal is the process of physically taking carbon dioxide back out of the atmosphere. At Climeworks, we have spent the past 17 years developing and deploying direct air capture technology that removes CO2 from the air and stores it in the ground for thousands of years. More recently, we launched our Climeworks Solutions business that works with third-party providers of other technology and nature-based carbon removal methods, such as reforestation, to help customers access a broader range of approaches and price points.
According to the United Nations Intergovernmental Panel on Climate Change, carbon removal will be necessary if the world is to come close to meeting its climate goals, even alongside deep emissions cuts. For companies building and using digital infrastructure, the question this raises is simple: What do they do about the emissions they cannot yet eliminate?
The strongest near-term answer is to treat carbon removal as part of the cost of digital infrastructure — not as a substitute for clean energy, but as a complement to it. Trying to pair every data center directly with a direct air capture plant may sound attractive, especially because data centers have power, land and waste heat. But in practice, that kind of integration is still highly site-specific and not yet an easy model to repeat at scale. A more realistic solution is to treat carbon removal as part of the cost of cloud and AI products, where it can be built into existing pricing and contracts. In other words, carbon removal should be built into the cost of the digital product itself, rather than physically attached to every data center site.
The incentive is simple: As companies come under growing pressure to account for the emissions linked to the digital infrastructure they rely on, data center providers that offer a credible lower-emissions product will have an advantage.
One criticism of using carbon removal in this context is that it could prolong the use of fossil fuels. That concern deserves to be taken seriously, but it also needs a nuanced answer. There is an important difference between using carbon removal to justify new fossil infrastructure, and using it to address residual emissions that cannot yet be avoided. The latter is the role that serious climate frameworks assign to carbon removal.
Data center operators are not turning to natural gas because carbon removal exists. They are doing so because natural gas can provide the speed required by the current pace of compute growth. Carbon removal should therefore not be seen as a substitute for decarbonization, but as a way to manage a real constraint in an energy system that cannot decarbonize instantly.
The relevant comparison is not carbon removal versus renewables. It is unabated fossil-powered data center expansion versus expansion in which some of the resulting emissions are credibly and durably addressed. In that sense, the growth of AI infrastructure also creates an opportunity for carbon removal: It can bring larger volumes into the market, support scale-up, and help drive down costs over time.
The economics of integrating carbon removal into AI infrastructure are more feasible than one might assume. In December, Julio Friedmann, one of the best-known experts on carbon management and carbon removal, wrote in a Substack article that a gigawatt of advanced data center capacity can generate around $10 billion to $12 billion in annual revenues. Against that scale of value creation, the cost of addressing residual emissions through carbon removal becomes more manageable.
The emissions associated with that computing power depend heavily on how it is supplied. Based on our own calculations, assuming the current U.S. grid mix and utilization rates of around 85% to 100%, a gigawatt of data center capacity would emit approximately 3 million to 4 million tons of CO2 per year. Behind-the-meter natural gas generation would produce a similar level of emissions. Renewable power can reduce those emissions significantly, while nuclear power could reduce them further.
In practice, not every gigawatt of data center compute will be powered in the same way. But assuming roughly half is supplied by renewable or nuclear power, average residual emissions would still be around 2 million tons of CO2 per year for each gigawatt of compute. That is a substantial volume — and exactly the kind of residual emissions gap that carbon removal can help address.
A portfolio of carbon removal solutions, which can directly mitigate these emissions, only costs a few hundred dollars per ton. While that is a meaningful cost, it is manageable given the economics of AI products. It is affordable enough to make a start, especially for companies that want to offer a credible lower-emissions digital product.
So, who pays? In the near term, the most likely model is that cloud and AI service providers procure carbon removal and build the cost into their products, while customers create the commercial pressure and ultimately support that cost through procurement. Even if companies are speaking more cautiously about net zero than they were a few years ago, the underlying need for credible value-chain emissions data has not disappeared. Organizations still face growing pressure to account for scope 3 emissions through disclosure rules, investor-facing reporting frameworks and supplier requirements. As their use of cloud and AI grows, they will increasingly ask providers a simple question: What emissions come with this compute, and what are you doing about them? Once buyers start routinely asking that question, carbon removal moves from being a climate nice-to-have to a product feature.
Climeworks has reduced the cost of direct air capture significantly since our first plant came online, and that trajectory will continue as the market grows. But cost curves do not come down on their own. They come down when buyers decide that a cleaner product is worth paying for. The cost of solar electricity fell around 90% between 2010 and 2023, driven not just by technology but also by early procurement commitments from the likes of Google, Microsoft, and Amazon that gave manufacturers the confidence to invest at scale.
Carbon removal is approaching a similar inflection point. In April, Climeworks signed an agreement with NTT Data — one of the world’s largest digital and IT service providers — to remove carbon dioxide from the atmosphere, as part of its commitment to net zero.
The business case, then, is simple. The AI boom is creating enormous economic value. But it is also creating residual carbon emissions that cannot be avoided only by clean power and increased efficiency. The solution is not to wait for a perfect zero-carbon grid, and it is not to force a bespoke carbon removal engineering solution onto every data center site. I believe the solution is to integrate carbon removal into the digital infrastructure offer now, and let customers choose it. That’s how lower-emissions compute becomes real and scalable. And that is why carbon removal needs to become an essential part of responsible AI growth.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
The zero-emission pioneer is doing the dirty work for the AI boom.
All kinds of companies have refashioned themselves to exploit the AI boom. A bitcoin miner became a data center developer, a shoemaker is building GPUs, and an electric vehicle company is integrating its powertrains into server racks.
Now, a company that once aspired to build one of the lowest-emitting power plants has pivoted to building one of the dirtiest in order to meet data centers’ requirement for speed to power above all. Net Power was founded to pioneer a new form of natural gas power plant with zero emissions, but it has given up on that technology and recently acquired 10 natural gas reciprocating engines that it plans to co-locate with a data center on the site intended for its first commercial plant.
“We believe the clean piece is important,” Net Power CEO Danny Rice said during an August earnings call when he announced the company’s pivot to building unabated natural gas plants. “But just as it’s always been, it will only come at scale once society’s basic energy pillars of reliable, affordable power are fully in place. Power demand is outstripping supply today.”
Net Power’s pivot is a sign not only that the AI boom has eroded market appetite for clean power, but that U.S. policies supporting carbon capture — primarily the 45Q tax credit that President Trump’s One Big Beautiful Bill Act recently expanded — are still not enough to support the technology’s deployment in the power sector.
“The long history of doing CCS in the United States is there isn’t enough public funding to get companies to deploy it at scale,” Jack Andreasen Cavanaugh, a senior research associate at Columbia University’s Center on Global Energy Policy, told me.
This is actually the second major pivot the company has made in less than a year. Last November, Net Power was still testing its proprietary oxy-combustion technology at its demonstration site in La Porte, Texas. The tech was designed to burn natural gas in a chamber with pure oxygen, producing a purer stream of CO2 than when natural gas is burned in regular air. Net Power’s system could recycle some of that CO2 for power generation and capture the rest more efficiently than a conventional gas plant could. The company had not yet demonstrated that the system could generate more energy than it used, however.
By that point, Net Power had determined that its oxy-combustion plants, if they ever even did generate net power, would not be economically competitive anytime soon. In its 2025 Q3 financial report, the company said it had “decided to broaden the scope of its business” and develop more conventional natural gas plants with carbon capture equipment tacked on. It signed a letter of intent with Entropy, a Canadian company building “post-combustion” carbon capture equipment, to bring the tech to the United States, and ordered two 30-megawatt Siemens natural gas turbines for 2028 delivery.
“For us and everyone else in the power and data center space these days, speed is everything,” Rice said at the time. “We believe gas turbines with [post-combustion capture] can and should be the fastest-to-market and most cost-competitive clean, firm solution for our prospective customers.”
He told investors that rising costs were one of the setbacks Net Power faced in building its first-of-a-kind oxy-combustion plant. It was highly unlikely the company could finance and build a $1.7 billion, 200-megawatt plant before completing all its testing, he said. The best-case scenario for the plant to come online was 2030 or 2031, and costs might keep rising with inflation. The company could either bet on that prospect and keep bleeding cash, or “slow down that spending in order to free up some of our resources for near-term accretive opportunities.” As a public company with shareholders to answer to, there was really only one choice.
By the end of 2025, Net Power decided to suspend its oxy-combustion development and testing activities altogether, according to its year-end SEC filing.
Six months later, the company’s thesis changed again. Gas turbines with post-combustion capture, it turned out, were not the “fastest-to-market and most cost-competitive” solutions that the company had hoped they’d be. Whereas once upon a time, electricity buyers considered a range of factors when shopping around for power, including carbon emissions, the reality was that they were now only looking for three qualities: speed, reliability, and scale. “Natural gas power generation, co-located with customer load, and deployable on a fast timeline, is how we expect to meet that demand today,” Rice told investors, adding that the company hoped to add carbon capture to its projects in the future.
To date, only one proposed U.S. natural gas plant with carbon capture has announced a deal to sell its prospective power. In October 2025, Google signed a power purchase agreement with the Broadwing Energy Center, an Illinois plant under development by a company called Low Carbon Infrastructure.
“There is a massive demand for unabated gas right now, and there is much less of a demand for carbon capture,” Cavanaugh said. He told me there are still lots of conversations happening between hyperscalers and carbon capture companies, but the physical realities and costs of capturing, transporting, and storing carbon from natural gas plants remain obstacles.
The Global CCS Institute published its annual Global Status of CCS report this week, which found more than 266 carbon capture, transport, or storage projects are under development in the U.S., but permitting delays and policy uncertainty are stalling their progress. “Inflation and rising capital costs have weakened project economics, reducing the effectiveness of existing policies, such as tax and investment credits,” the report said.
That doesn’t mean there aren’t still companies trying. Net Power may have given up on oxy-combustion power plants for now, but Arbor Energy, a startup founded by former SpaceX engineers, is just ramping up. Arbor announced a milestone in the development of its own oxy-combustion power generator last week, running a key piece of its system — a supercritical CO2 turbocompressor — for more than two hours at high speeds.
Arbor differentiates itself by using 3D-printed turbines and developing smaller, more modular plants. It’s scaling more incrementally than Net Power tried to, starting with a 1-megawatt demonstration plant in California that is “weeks away” from operating, the company’s Chief Operating Officer Alicia Harmon told me — although the project won’t include carbon storage. It plans to build a 25-megawatt demonstration plant by 2028, also sans storage, before manufacturing commercial-scale systems.
Arbor actually went through a pivot of its own due to the data center boom. The founders originally planned to focus on bioenergy with carbon removal, using the oxy-combustion technology to generate power from biomass and storing the resulting CO2 underground. Over time, though, it became clear that demand for power outpaced demand for carbon removal, and natural gas was more abundant than biomass.
I asked Harmon whether the company thought there was market demand for carbon-capture gas plants. Is anyone willing to pay that green premium right now? “Honestly, my answer is no,” she said, but the company sees a path to erasing the green premium by the early 2030s. She added that Arbor’s technology is already “very close” to parity with combined-cycle natural gas plants when the 45Q tax credit is taken into account.
Last month, Net Power announced it had acquired 123 megawatts’ worth of Wärtsilä reciprocating engines, in addition to the Siemens turbines it had already ordered. Reciprocating engines are among the dirtiest natural gas power-generation technologies. A recent report from Earthjustice estimated that a 1-gigawatt plant powered by reciprocating engines would emit 1.5 times as much CO2 per year as one powered by the “combined cycle” technology most modern plants use, and twice as much nitrogen oxides and fine particulate matter. It has not yet disclosed any data center partners to sell the power to.
Net Power declined to comment on this story.
Ben Allen wants to reform the existing market. Jane Kim wants a revolution.
From Crescent City to Coronado, California voters are facing decisions on a down-ballot strewn with over a dozen propositions and a series of statewide Democrat-versus-Republican races with mostly foregone conclusions.
And then there’s the insurance commissioner.
In the race to oversee California’s insurance market, a $452 billion-in-premium-volume monster imperiled by insurer defections and disaster risks, Democratic State Senator Ben Allen, whose district includes Pacific Palisades, is facing off against Jane Kim, a progressive former San Francisco supervisor.
Kim has the support of Vermont Senator Bernie Sanders — it’s the first thing you see about her when you Google her campaign. She previously served as his California political director during the 2020 presidential race, and she appeared earlier this month at an event with the senator in support of the state’s proposed billionaire wealth tax.
Allen, by contrast, won the endorsement of the state’s Democratic Party and its two incumbent senators.
There has been little public polling of the race, but one September survey showed Kim leading Allen 25% to 18%, with more than half the electorate undecided.
“My opponent and I are not even running for the same office,” Kim told me. “He’s running for what this office used to be, and I’m running for what this office could be.”
Allen wasn’t worried about Kim’s characterization in my interview with him, telling me, “I want to fix the market that we have and make it work. My opponent wants to build a new state insurer that nobody has priced.”
Nowhere are the stakes of insurance regulation higher than in California. On its own, the state’s insurance market would be the third largest in the world, according to the National Association of Insurance Commissioners. Homeowner insurance premiums have risen 84% from the end of 2020 to March 2026, according to research from Stanford’s Climate and Energy Policy Program. Several large insurers have either left the market entirely or stopped writing new policies.
California’s creaky and complex regulatory environment for insurers has combined with its famously flammable environment (all beset by a warming climate) to put regular policyholders at risk of losing their policies or bailing out those who can’t get covered. “Climate risks grow, and our mechanisms for dealing with it lag behind,” Matt Weiner, the chief executive of the wildfire policy group Megafire Action, told me. (Weiner said he was supporting Allen in his personal capacity).
Rates for homes insured by the FAIR Plan, the barebones insurer of last resort, have more than doubled from about 2% to 5% over that same period, with FAIR Plan coverage spreading from just high-risk areas to even areas with low and moderate wildfire risk. The plan required a $1 billion assessment from the state’s insurers in 2025 following major Southern California fires. “This trend is a symptom of many homeowners’ inability to secure insurance in the conventional market,” according to the Stanford researchers.
Allen seeks to make the insurance market work better, building on reforms implemented by current Insurance Commissioner Ricardo Lara. Allen described the reforms, which encourage insurers to write policies in high-risk areas and allow them to use forward-looking projections, as a “bit of a band-aid” that doesn’t “actually get to the core of the problem, which is making these communities less risky.”
Allen’s plan for the California insurance market involves both reviewing rate proposals more quickly, incorporating more data into those rates (which may push rates up, but also keep insurers in the market), and mobilizing the whole of government to invest in home hardening and resilience to lower risk and bring premiums down. Allen wants to, well, insure “that risk reduction is actually incentivized and rewarded by the insurance market,” he told me.
This would mean that “there will continue to be certain properties that are going to be so high risk that they really will and ought to be paying significantly more than everybody else,” he added.
When I asked him to elaborate on his vision for California’s insurance future, he told me, “My hope is that when a family and a neighborhood commit to hardening defensible space and community-scale mitigation, that should show up on the bill.”
Jane Kim, on the other hand, is interested in an insurance revolution, which would require — as her most famous supporter might put it — a political revolution as well. Her centerpiece proposal will be familiar from anyone who has followed Sanders’ career: a single-payer disaster insurer.
The plan, which she told me was a “concept and a proposal,” would be funded by a levy placed on insurers, and then a public insurer would invest in the market, buy reinsurance, and pay out claims. (Her opponents have criticized her for not being forthcoming enough with details). She says her plan would not be able to cover a Palisades- or Altadena-level fire in its first year, “but no insurance company can cover a catastrophe of that level.”
The nonprofit nature of the program, she adds, would let the state fund mitigation work directly. While such a program would require legislative action, “the great thing about campaigns is that this is trying to debate big ideas with voters,” Kim said.
In response, Allen cited a report from the California Earthquake Authority, which modeled a state disaster insurer (albeit not Kim’s plan specifically) could require $25 billion in capitalization. A more thinly capitalized insurer could mean $2,000 assessments on every policyholder in the state to cover an extreme wildfire disaster, the report said. “That’s the honest price of what she’s proposing,” Allen said.
“I also have a plan that’s actually grounded in reality and fixing the problems right now. It's not based on some pie-in-the-sky set of ideas that have no precedent, that have no real meat on the bones,” Allen told me.
One of Allen and Kim’s former opponents, Patrick Wolff, who fell short in the top-two primary election in June, told me that “the charitable interpretation of Kim’s platform is she does not think the current system can be made to work, and so she essentially wants to redesign and reimagine the entire system.” (Wolff has endorsed Allen). But, he added, “she’s coming at it from a set of solutions that were baked-in before she started, and then she's fitting [those] into her campaign.”
Moira Birss, a senior fellow at the Climate and Community Institute who said she had “provided input” to Kim’s campaign, but wasn’t speaking on its behalf, told me she “really recognizes that we are yet again in a situation where the private insurance market is not responding to a need that we as communities and as society have for this financial safety net of disaster insurance, and that we need a public approach.” She said the plan would build on lessons learned from New Zealand, which has public natural disaster insurance funded through a levy on fire insurance, and from the National Flood Insurance Program and the FAIR Plan.
Kim is happy to embrace the more ideologically charged vision of her campaign, telling me, “I am talking about transforming this office to be a place where we are leading on, and taking on, economic inequity, a wealth gap, and the climate crisis.
“I don’t even view my opponent as Ben Allen — I’m not running against Ben Allen,” she went on. “I’m running against the status quo.”
On Hungary’s Russian nuclear conundrum, why geothermal isn’t solar, and a funny use of gallium
Current conditions: An ill-timed and dense fog blanketed Toledo yesterday amid an industrial chemical leak, with the low-lying cloud acting to trap the toxic glycidyl methacrylate in the air, forcing an evacuation • Super Typhoon Champi has become the most powerful storm of 2026 as it roars westward across the Pacific to Taiwan, leaving a damaged Guam in its wake • After Polo, Simon, Rachel, and Trudy, yet another tropical depression capable of striking western Mexico as a major hurricane has formed in the eastern Pacific.
That’s the money quote Politico nabbed Wednesday from Senator Sheldon Whitehouse, the Rhode Island Democrat who helped broker the Senate’s grand compromise to ease federal permitting on energy projects. The statement came a day after the Department of Justice filed a petition to reopen the permits on New England Wind, the 2.6-gigawatt offshore wind project from Avangrid. Just over a week ago, the Trump administration restarted a legal fight with Orsted over Revolution Wind, which is already generating electricity off the coast of Rhode Island. At the time, some White House observers saw the effort as President Donald Trump’s hard-nosed negotiating, designed to pressure skeptical Democrats into voting for the legislation lest the administration continue going after projects that the bill, if passed, would protect. But Ira Joseph, a fellow at Columbia University’s Center on Global Energy Policy, saw the latest move as evidence Trump can’t control his impulse toward vendetta. “An inevitable turn. It’s always personal and never about what policy would either benefit or hurt the public,” he wrote in a post on X. “Wind will always be associated with harming the family business. It’s always a King Claudius situation and he or she who whispers last, whispers loudest.”

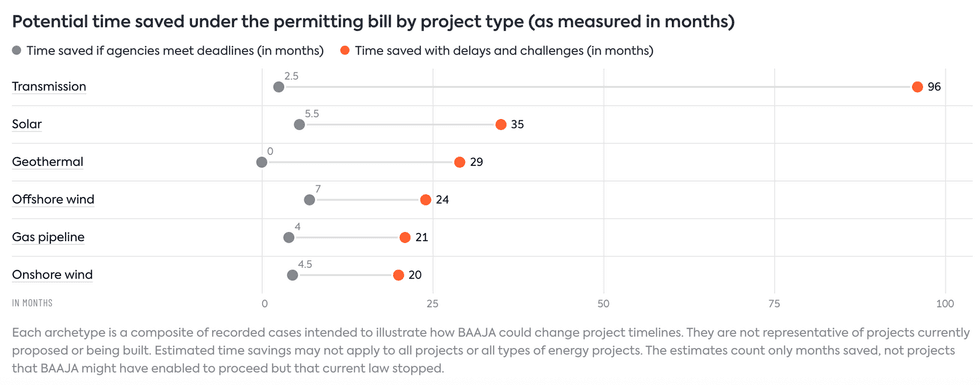
Joseph’s colleague at CGEP, Jack Andreasen Cavanaugh, is out with a new tool to estimate how much time the Bipartisan American Affordability and Jobs Act would save various kinds of clean energy projects. The results are pretty staggering. Transmission lines alone could save eight years by avoiding the delays and challenges opponents can currently lob against a project.
When the Department of Commerce enacted new trade restrictions on polysilicon in August, the agency gave the industry a 120-day head start to prepare for the policy to come into force. To prevent importers from stockpiling foreign solar panels and components, the Commerce Department promised to remain vigilant. The crackdown is underway. In a note to investors this week, Roth analyst Philip Shen said the agency has blocked roughly 60 importers over the past several weeks, including 10 just this past week. Prior to the Commerce Department’s Section 232 decision, the U.S. had roughly 200 approved importers bringing in solar panels.
The number of solar importers more than doubled over the past few months to more than 400 total. Roth’s memo highlighted speculation that the Commerce Department could dampen its 232 policy, giving utility-scale developers a carveout or delaying the implementation on December 3, when the 120-day waiting period ends. Shen said his sources “with direct access to the Commerce Department” say any such carveouts are “not being worked on” by the agency. A spokesperson for the Commerce Department did not respond to my email requesting comment last night.
In April, Hungarian opposition leader Péter Magyar defied the odds and ended nearly two decades of quasi-authoritarian rule by Prime Minister Viktor Orbán. Among the biggest differences between the two leaders is Magyar’s desire to realign Hungary, which had been Russia’s most reliable partner in the European Union, with Brussels. No one expects Budapest to wean off Russian gas any sooner than other addicted EU nations such as Austria and Italy. But the energy elephant in the room was the new Russian nuclear reactors Hungary was building. The Paks Nuclear Power Plant, Hungary’s only atomic station, generates roughly half the country’s electricity. Orbán had commissioned Rosatom, the Kremlin’s state-owned nuclear company, to expand the facility in 2014 without a competitive bidding process. On Wednesday, Reuters reported that Prime Minister Magyar is considering new vendors to replace Rosatom.
The U.S. could be a potential player in the mix. Over the past few years, Westinghouse, America’s nuclear champion, has started producing fuel assemblies for Russian-made VVER reactors in Bulgaria, Czechia, Finland, Slovakia, and Ukraine. Westinghouse is also making deals to build its AP1000 reactors across Eastern Europe, starting with Poland but ultimately expanding to at least Bulgaria and Ukraine. On Wednesday, the company announced a plan to invest $1 billion into expanding its fuel manufacturing into LEU+, a slightly more potent version of low-enriched uranium that Southern Company started experimenting with last year. “As we advance the next generation of fuel, we are positioned to create more value for our customers and unlock new nuclear generation to support the growing demand for baseload power,” Dan Sumner, Westinghouse’s chief executive, said in a statement.
Sign up to receive Heatmap AM in your inbox every morning:
In June, Google inked a deal with the virtual power plant provider Voltus to deliver 100 megawatts of flexible distributed power to PJM Interconnection, the electricity market covering the Mid-Atlantic and Midwest. On Thursday, the companies announced an expanded agreement to build a 1 gigawatt network of renewable and storage assets that can be tapped to balance out the nation’s second-largest and arguably most-stressed grid. The deal “represents one of the largest known distributed capacity portfolios deployed by a hyperscaler to date,” according to the companies’ press release. “Distributed energy resources are powerful tools for managing a modern, reliable grid while keeping energy affordable,” Ellen Zuckerman, Google’s head of energy market development for the Americas, said in a statement. “Expanding our initial commitment tenfold demonstrates our core effort to actively bring our own capacity to the grids that serve us.”
Meanwhile, General Motors led a $108 million Series B funding round for Peak Energy to help ramp up production of its sodium-ion batteries, Bloomberg reported Wednesday. That same day, Optivolt, a startup behind a device meant to make solar panels more efficient, raised $32 million in a Series A with backing from heavyweights in the solar industry, including former SunPower CEO Tom Werner and ex-Enphase CEO Paul Nahi.
Next-generation geothermal promises to generate 24/7 renewable power while tapping into the workforce and industrial knowhow the U.S. oil and gas industry built up during the fracking boom. But that won’t ever make geothermal wells as cheap as mass-manufactured solar panels — and the sector’s hypemen need to stop insinuating otherwise. That’s the take from Cindy Taff, the chief executive of the geothermal startup Sage Geosystems. In a Wednesday post on LinkedIn, the former Shell fracking executive, whose company is now a strong contender for the nation’s No. 2 next-generation startup behind fellow Houston-based Fervo Energy, accused rivals of telling “a compelling story” but not necessarily “an accurate one.” A solar panel made for Arizona “is fundamentally the same as those installed in Athens,” the Greek capital. But the unit in geothermal is a well, “and every well is drilled into rock with differing characteristics, temperature profiles, and operational challenges.” In other words: “We tell investors that geothermal will follow solar’s cost curve. I understand why the comparison is attractive. I’m not convinced it helps us. Solar got cheap by manufacturing millions of near-identical units, with improvements compounding across a global supply chain.” The industries, she went on, are on fundamentally different trajectories. “If we promise one curve and deliver another, we risk looking like we’ve underperformed even when we’re making real progress,” she wrote. “I’d rather we make the harder, more credible argument that geothermal costs come down through repetition in the field. And repetition requires a steady pipeline of projects and capital.”
The wake-up call came shortly after Fervo faced its first major short-seller report. When my colleague Emily Pontecorvo talked to experts on the bearish take on Fervo, she found few industry insiders who took the claims very seriously, but many who feared that, if the company stumbled, raising more money for next-generation geothermal could prove difficult.
The best art, in my humble and dilettantish opinion, can be interpreted multiple ways. The most obvious way to read the latest stunt from the climate activist group 350 Action should require little explanation for a Heatmap reader. The group hired an advertising agency to help construct and place a statue of Florida Governor Ron DeSantis, who has rejected the science behind the climate change so severely impacting his state, cast in gallium, a metal that melts at 85.6 degrees Fahrenheit. When temperatures in Tallahassee, the state capital, reached 90 degrees last Thursday, the statue’s face, which closely resembled the former Republican presidential contender, oozed away, revealing a skull. But here’s another way to look at it: The U.S. is facing a severe shortage of gallium, which is needed for power electronics, solar cells, and electric vehicles. As Noah Gordon, a policy fellow at the European Council on Foreign Relations, put it: “Hilarious way to use scarce US supplies of gallium.” Take from that what you will.