You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
A new report finds that utilities are spending more than fossil fuel companies to keep up with data center electricity demand.

The transition to clean energy is largely a shift from molecules to electrons — gasoline in the tank is out, electricity stored in a battery cell is in. It follows, then, that as the transition progresses, the balance of power in the energy industry will shift from oil and gas production to electricity generation.
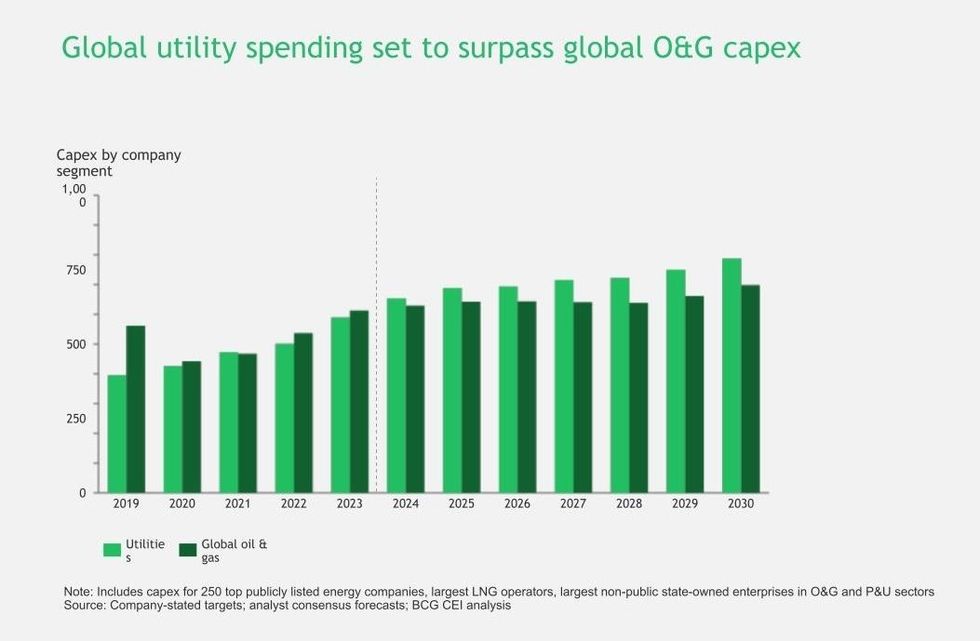
We may look back on 2024 as the year the scales tipped. Among the top 260 publicly listed energy companies, utilities’ capital expenditures around the globe were slightly higher this year than oil and gas spending, according to a recent analysis from Boston Consulting Group, and the authors expect the trend to grow through the end of the decade. But it wasn’t a sudden spike in EV adoption or home electrification or some other climate solution that put utility spending in the lead. It was the rise in data centers.
“When we went through all the data, all the 260 companies, it was the data centers that were having the biggest impact, most definitely,” Rebecca Fitz, a partner and director at Boston Consulting Group and lead author of the report, told me. “I’ve been in this sector for a long time, and to have such a rapid change in demand outlook, coupled with quick changes to capex, is a big story.”

The finding was the surprise headline of an annual report that Fitz’ group has completed for the past three years called “Follow the Capital,” an analysis of what’s driving changes in capital supply and demand in the energy sector using data culled from publicly available sources. Data for prior years comes from regulatory and investor fillings. Future years are modeled using public announcements, plans filed with regulators, and a few conservative assumptions, Fitz told me.
Surging demand for electricity from data centers was perhaps the biggest energy story of 2024, and the trend seemed to accelerate as the year went on. In just the past few months, almost every major tech company has signed an agreement to buy power from a nuclear plant, either reviving formerly shuttered reactors or helping to build new ones. GE Vernova, which manufactures energy generation equipment, reported last week that it had secured contracts for 9 gigawatts’ worth of new gas turbines since its previous quarterly report in October, “tied to both load growth in the U.S and … serving the hyperscaler demand associated with AI.” As the “Follow the Capital” authors were wrapping up this year’s edition in November, they found that U.S. utilities had added $50 billion in planned capex during the third quarter alone, mostly due to data center demand growth.
Data center demand isn’t the only factor playing into the above chart. Though utility spending is definitely up, oil and gas companies are also reining in capex growth in favor of shareholder returns, Fitz told me. But oil and gas also sees the winds changing and is making moves to get into the power business. Two weeks ago, during a panel hosted by the Atlantic Council, Chevron CEO Mike Wirth said the company was “looking at possible solutions to build large-scale power generation” that would serve data centers directly, rather than feed into the grid, so that regular electricity ratepayers would not shoulder the costs. “There’s sensitivity to increasing electricity rates for the average person just for the benefit of a few of these tech companies,” he said.
Beating Chevron to the punch, last week ExxonMobil announced that it was “moving fast” on this exact type of project, designing a natural gas plant that would “use carbon capture to remove more than 90% of the associated CO2 emissions” and directly power data centers without connecting to the grid.
“I have no doubt that most of the oil and gas sector is looking at opportunities in this area,” said Fitz.
Though the report covers global companies and spending, the data center demand signal is hyperlocal. Among the 30 largest North American utilities, 65% of demand growth is concentrated within just six of them, the report says. Though the report does not name the companies, Fitz told me that Texas, North Carolina, Virginia, and Ohio were seeing the most aggressive plans.
Artificial intelligence boosters often argue that this demand pull is a boon for the energy transition. By ushering in the age of electrons, the logic goes, tech companies with deep pockets can drive the first deployments of new clean energy technologies like advanced nuclear and geothermal power plants. These early deployments would then help lower costs and give rise to cheaper, cleaner electricity for the rest of us average energy consumers and our future electric cars, stoves, and water heaters.
But that’s not the only potential outcome. “Follow the Capital” found that when the six utilities most affected by demand growth recently revised their integrated resource plans, they increased the amount of natural gas generation they planned to add from 26% of total new generation to 31%. As GE Vernova reported, orders for gas generators are skyrocketing. “I can’t think of a time that the gas business has had more fun than they’re having right now,” the company’s CEO Scott Strazik said during a recent investor update.
As my colleague Matthew Zeitlin reported, the industry is turning to natural gas plants because they can run 24/7 and they are not as dependent on transmission lines as renewables are, so they can be built faster and more cheaply. Renewables paired with energy storage are only competitive with gas if there’s infrastructure to support it, sources told him.
The age of electrons may be nigh, but whether it helps to stop climate change is a separate question altogether.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Advanced nuclear will take a decade or more to hit commercial scale. Meanwhile, the hyperscalers need power now. Enter the uprate.
When America’s tech titans started plowing money into nuclear technology to power data centers in 2024, companies such as Google and Amazon opted to invest first in next-generation reactor startups. But electricity demand is soaring today, and those projects are still years away — at least — from generating power at reasonable commercial rates.
So the industry is hedging by betting on existing nuclear plants to pump out more electricity in the near term. Uprates — renovations that allow nuclear operators to produce more power from existing reactors — are all the rage this year.
In February, the Department of Energy issued its largest-ever loan to Southern Company to fund up to 6 gigawatts of uprates across the utility’s nuclear fleet. Last week, Amazon signed a deal with Constellation Energy, the nation’s largest operator of nuclear reactors, to uprate the Calvert Cliffs plant in Maryland to generate another 190 megawatts on top of its current 1.8-gigawatt output. Soon after, the Energy Department offered nuclear operator Vistra a $4 billion loan to uprate plants in Ohio and Pennsylvania.
Then on Tuesday, Google inked its own deal with Constellation aimed at wringing out 890 megawatts of new power from 11 reactors across PJM Interconnection, the nation’s second-biggest and arguably most overworked grid system.
“Everyone loves nuclear, but it takes a really long time to build,” Raiford Smith, Google’s head of power and energy for the cloud, told me yesterday. “The fastest way to get it is via uprates. It’s real megawatts, but the quicker, shorter-term approach.”
Building new reactors, he said, “is the intermediate term plan, and we see fusion as the longer term bet.” Given that “new data centers are coming on at a gigawatt a clip, that means even with all the uprates, there’s still more to come,” he added.
The investments into existing nuclear stations deliver a win for Constellation, whose chief executive, Joe Dominguez, has been among the more vocal C-suite skeptics of what my colleague Matthew Zeitlin described as utility executives’ “load growth mania” over the past two years. But the deals say as much about the shifting lines in the debate over how to expand the nuclear power fleet in this country — what size reactors are better, how to finance projects — as the disagreement over how much new generation is needed to supply the artificial intelligence boom.
The deal “is a win-win,” Emmet Penney, the director of energy and infrastructure at the think tank Foundation for American Innovation, told me. “Constellation and Google are revealing just how essential our nuclear fleet is to maintaining our energy dominance.”
America’s last attempt at a nuclear buildout ended in a series of financial boondoggles. The problems traced back to numerous factors: Decades without any nuclear construction atrophied the workforce. Electricity market reforms aimed at breaking up monopoly utilities left the industry with few players equipped with large enough balance sheets to take on megaprojects that would take years to build and billions of dollars of upfront capital. Increased competition from cheap natural gas.
The only two new reactors that made it over the finish line, Southern’s pair of Westinghouse AP1000s at the Alvin W. Vogtle Generating Station in eastern Georgia, came in billions of dollars over budget, in part because the developers erred in choosing a Nuclear Regulatory Commission licensing pathway that required long stops and costly delays every time the builders tweaked the design. Since those were the first AP1000s constructed in the U.S., there were plenty of last-minute design kinks to iron out.
In the meantime, the industry rallied behind the idea of small modular reactors. By making individual reactors roughly a third or less powerful than large-scale units such as the AP1000, the thinking went, developers would need to buy more, helping the technology slide down the cost curve through repeated construction and assembly-line manufacturing of components.
While Google and Amazon both backed fourth-generation startups whose designs use coolants other than water, such as liquid sodium or helium gas, the only such reactor operating in the world is in China, and America’s track record of running similar plants is poor. As such, government-owned utilities such as Canada’s Ontario Power Generation and America’s Tennessee Valley Authority have thrown their weight behind third-generation SMRs that essentially just shrink down existing water-cooled technology. The first of GE Vernova Hitachi Nuclear Energy’s BWRX-300s, a 300-megawatt design based on the boiling water reactors that make up about a third of the U.S. fleet, is now underway at OPG’s Darlington plant. In the U.S., meanwhile, the NRC just issued a construction license for the TVA’s first BRWX-300.
But the completion of the second AP1000 at Plant Vogtle demonstrated an uncomfortable reality proposed by researchers at the Massachusetts Institute of Technology: That the next, cheapest reactor to build in the U.S. would be another of Westinghouse’s flagship design. Vogtle Unit 4 came online in 2024 roughly 30% cheaper and faster than its slightly older twin, Vogtle Unit 3.
If that reduction seemed to justify the approach SMR companies were pursuing, a report by an economist and former antinuclear researcher raises new questions. The study by Charles Komanoff, which I covered here last month, suggests that the number of reactors required to achieve major cost reduction through “economies of duplication” pales in comparison to the price drop achieved through “economies of scale.” In other words, the nuclear industry’s time-tested approach to making reactors more economical — making them bigger — is still the best bet.
The Trump administration certainly agrees. The Energy Department laid plans for at least 10 new AP1000s last year, and put up another nearly $20 billion loan package for utilities that form joint ventures with Westinghouse to build one of the 1,100-megawatt reactors. South Korea is currently working out the fine print on a deal to help finance and build as many as six AP1000s and two APR1400s, the Korean rival to the Westinghouse reactor.
Whether any American utilities step up to help build any of those AP1000s remains an open question.
“There’s no way any utilities could consider building a large AP1000 because doing so could bankrupt the whole operation, and they don’t have enough confidence,” Chris Gadomski, the lead nuclear analyst at the consultancy BloombergNEF, told me.
The workforce that constructed the two AP1000s at Vogtle, he said, are now out building data centers. Unlike the Chinese, whose state-owned nuclear companies reverse engineered the AP1000 and made it relatively cheap to build by constructing as many as half a dozen at a time at one location, “we don’t have the wherewithal or sites in this country to build six reactors at once,” Gadomski said. “You’re lucky to build two at one site in this country.”
So fusion and next-generation fission remain years away. Current-generation SMRs come with big questions. And the leading large-scale design, the AP1000, is proving a hard sell to utilities. That leaves two options: Restarting decommissioned plants and uprating current reactors. The Energy Department has pumped billions in loans into projects to restart at least three permanently closed reactors: Holtec’s Palisades plant in Michigan, NextEra’s Duane Arnold facility in Iowa, and Constellation’s Crane Clean Energy Center, née Three Mile Island, in Pennsylvania. The consensus among industry experts is that those are the only three that remain intact enough to start back up; every other shuttered plant is at too advanced a stage of demolition.
That leaves uprates.
There are limits to how much power can be drawn from existing plants, said Jeff Jenkins, the founder and managing partner of Bernhardt Capital Partners, an investment firm whose portfolio includes Allied Power, a contractor that has worked with Constellation on past uprates. “There’s still a few gigawatts out there,” he said. “And a gigawatt is a lot.”
But ultimately, the U.S. nuclear buildout needs options.
“It’s very much a hedge,” Gadomski said. “They’re spreading their bets. That’s a strength of Google’s strategy. They’re willing to place bets on advanced reactors, fusion, and still try to double down on the capacity of existing plants.”
On methane rules, British wind, and the Israeli electricity market
Current conditions: Singapore’s air is the worst in the world as wildfire smoke from Indonesia chokes the city state and neighboring Malaysia • Following a summer-like heat wave, temperatures in the American West are set to drop by as much as 50 degrees Fahrenheit as a cold snap moves in • In the Gulf of Mexico, Tropical Storm Isaias officially strengthened into the first Atlantic hurricane of the season this morning.
With its offshore oil fields booming in Guyana and its opportunities opening in Venezuela, Exxon Mobil is eyeing the next location for the Americas’ oil and gas: Trinidad and Tobago. In an interview with the Financial Times this week, the company’s exploration chief said the island nation’s existing oil and gas industry could expand to tap the same basin east of Venezuela that has transformed Guyana from one of the hemisphere’s poorest nations to one of its richest in terms of per capita gross domestic product. “A lot of people ask, ‘well, where’s the next Guyana?’” John Ardill, Exxon Mobil’s vice-president and head of global exploration, told the newspaper. “In Trinidad, we moved in as a play extension to Guyana.” The agreement between Exxon Mobil and the Trinidadian government took “about half as long as it usually takes on a good day,” delivering a pact in “record time.”
America’s oil majors are also looking outside the hemisphere. As you may recall from August, I told you that Exxon Mobil was also considering a big investment in Africa, with Mozambique drawing particular attention. Brazil’s state-owned Petrobras, meanwhile, is expanding its own grasp on the Americas’ oil boom. On Wednesday, Upstream reported, the company bid $590 million for control of an ultra-deepwater concession.
The European Union is pausing implementation of its new rules requiring oil and gas exporters to more scrupulously track data on methane emissions. The U.S., on the other hand, is planning a straight-up rollback. At an oil industry conference in Santa Fe on Wednesday, Environmental Protection Agency Administrator Lee Zeldin teased out plans to gut core parts of the methane regulations finalized in 2024. “This proposal takes on many of the problems American producers and operators have raised with us,” Zeldin said, according to Argus Media. “That includes the burden on marginal wells and oil and gas operators in general, the super emitter program, associated gas and control device requirements.”
Record wind power generation may have slashed how much natural gas Britain needed to burn last month for electricity, but it “wasn’t enough to shield the country from surging prices triggered by the war in Iran,” Bloomberg reported. Wind turbines pumped out 6.6 terawatt-hours of electricity in September, a record for the month and 4% more than a year earlier. As a result, gas-fired generation plunged to its lowest level on record for that month. But day-ahead power rates still doubled from a year earlier.
The world’s capacity of floating offshore wind, the subset of the sector that could vastly expand the areas of shoreline dotted with turbines, has reached 382 megawatts, a 38% surge over the past 12 months, according to a Renewables Now writeup of the latest report from the trade group RenewableUK. Meanwhile, Poland has now constructed all 76 of the standard turbines built into the seabed of the Baltic Sea for its first offshore wind farm. One-third of the turbines are now generating power, according to offshoreWIND.biz.
Sign up to receive Heatmap AM in your inbox every morning:
South Korea plans to speed up its shift away from fossil fuels with a new goal of 100 gigawatts of low-carbon energy additions by 2030 and roughly $747 billion in government-led investment over the next decade. The plan, part of the Korean Green Transformation program, “seeks to make Korea one of the world’s top three green manufacturing powers by developing industries such as hydrogen-reduction steelmaking, next-generation solar cells, and all-solid-state batteries,” according to The Korea Times, an English-language daily. New nuclear reactors are also part of the strategy.
The move comes as Seoul advances construction of as many as eight nuclear reactors in the U.S., including six of America’s Westinghouse AP1000 and two of its own APR1400s, as I told you last week.
The utility megamerger of the century so far is “not in the best interest of Virginians.” That’s the judgment the state’s lieutenant governor, Ghazala Hasmi, rendered this week following a five-city public listening tour. The statement came ahead of the State Corporation Commission’s first local hearing on the deal, and marks what Utility Dive called “the most formal expression of opposition from Virginia’s executive branch so far.” Governor Abigail Spanberger, a fellow Democrat, has not yet taken a definitive position on the merger.
But the deal follows some clear market logic. Among the benefits: It would create, as my colleague Matthew Zeitlin wrote in May, “a storage juggernaut.”

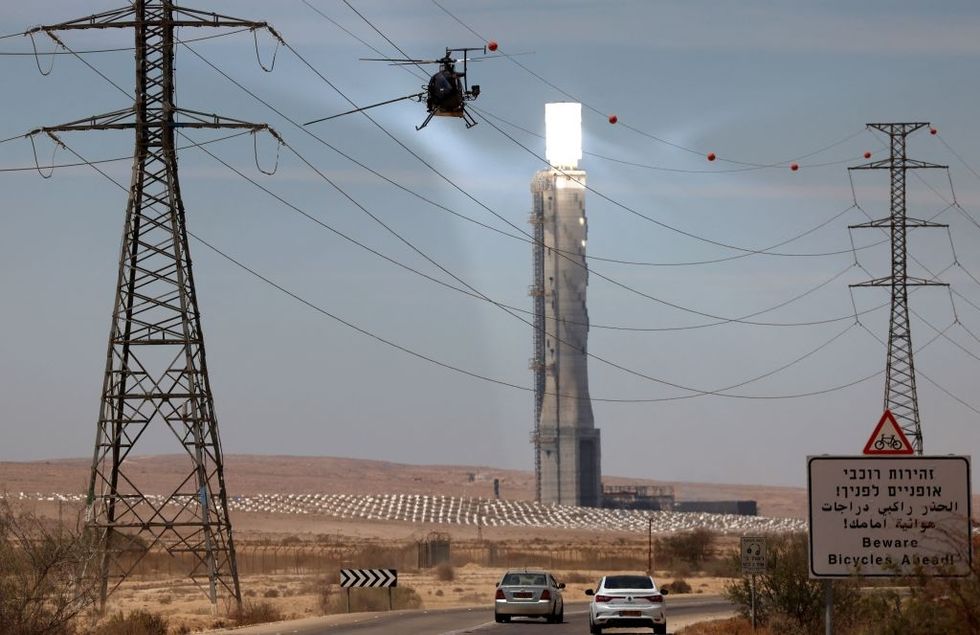
Israel’s booming tech sector and soaring stock market are just two ways its economy has dramatically changed from the socialism that defined the early decades after the country’s founding in 1948. Now that shift also includes the electricity market. Since market reforms allowed private actors into the grid at the start of last year, more than 2 million citizens, representing more than 500,244 private and business customers, have switched from the Israel Electric Corporation to private providers, according to The Jerusalem Post. Ratepayers buying electricity from private suppliers enjoy discounted rates ranging from 7% to 20%, “thanks to the lower generation costs in the private market.” Another 23,286 households and businesses submitted requests to switch suppliers just last month. OPC Energy, an independent power provider based in Tel Aviv, raised $200 million in bond issuances in August.
The announcement follows a Series A round that included investment from the Department of Defense.
The U.S. wants to make more of its own rare-earth magnets, which are critical to everything from guided missiles to aerospace systems and electric vehicle motors. But doing so will require a domestic source of high-purity iron, the main material in these magnets and one the U.S. imports almost entirely from China. Hertha Metals is betting it can fill that gap while helping decarbonize the ironmaking process, too. After raising a more than $133 million Series A, which the company announced last week, the Texas-based startup is promising to supply domestic magnet and steel manufacturers with 10,000 metric tons per year of lower-carbon, high-purity iron. That will come from its first commercial facility near Houston, where the company broke ground on Thursday.
Steel customers, including automakers and other equipment manufacturers, have already expressed interest in Hertha’s tech. But the startup’s most important customer might be the federal government. Defense manufacturers depend on rare-earth magnets — which require 99.95% high-purity iron — for things like aerospace platforms and radar systems. That explains why the Department of Defense invested $65 million in Hertha’s Series A through its Industrial Base Analysis and Sustainment program. The investment comes in partnership with the Economic Defense Unit, a new Pentagon division established under Trump that makes grants, loans, equity investments and purchase commitments into defense and dual-use sectors like critical minerals.
Hertha’s CEO and founder Laureen Meroueh called the new facility — sited next to its operational demonstration plant — the nation’s “first domestic iron and steel innovation complex” when I spoke with her in April to learn more about the company’s technology. She expects the plant to be operational by the end of next year.
That’s thanks to a new proprietary process that Meroueh, a mechanical engineer and materials scientist by training, pioneered. “We find ourselves in the year of 2026 making steel out of the same furnace that was developed in 1850. That’s insanity,” Meroueh told me. Today, most iron is produced by stripping oxygen from ore in a furnace that operates at over 3,000 degrees Fahrenheit. Called a blast furnace, this towering steel-and-brick shaft is fueled by coke made from metallurgical coal. The resulting molten iron then enters a basic oxygen furnace, where it’s refined into steel. Producing the higher-purity iron needed for rare earth magnets requires additional refining steps to remove impurities.
While lower-emissions alternatives do exist, they come with their own limitations. Direct iron reduction, for example, uses hot gas to strip oxygen from ore, then melts the resulting solid iron in an electric arc furnace. But the process typically requires higher-grade ores to begin with, and thus remains a small share of global production. Electric arc furnaces can also recycle steel scrap — indeed most domestic steel is produced this way — but supply is finite. Meanwhile, ore quality is decreasing over time, limiting the grades of steel it can ultimately produce.
Enter Hertha, which says it can turn low-grade iron ores into high-purity iron in a single furnace. Meroueh explained that Hertha uses either natural gas or hydrogen to strip oxygen from molten ore in an electric arc furnace, with no separate reduction step beforehand. Because the furnace melts down the ore and its impurities from the outset, it can accept low-grade ore in many forms, including fines, the powdery particles left over from mining and processing. When everything is molten, the lighter impurities separate from the denser iron and form a layer of slag that operators can then drain from the furnace. The resulting iron needs only minimal additional refining to go into rare earth magnets.
“This is a continuous reactor, so you continuously feed it and semi-continuously tap out your slag and product,” Meroueh explained. Melting iron made from ore produces far more slag than standard electric arc furnaces are designed to handle, and would thus require frequent interruptions in operations. But Hertha’s proprietary process doesn’t need to do that. “This continuity in operations is what makes it economically viable for us to generate large amounts of slag while maintaining production and throughput.”
The startup also says it can make steel using the same process by adding a controlled amount of carbon to its single furnace. While Hertha hasn’t provided an estimate of avoided emissions for this plant specifically, it says a third-party modeler has projected that its subsequent 500,000-metric-ton facility will emit up to 50% less than conventional blast furnace steel production when running on natural gas, and 98% less when running on green hydrogen.
Hertha also expects its process will cut costs by 25% compared with blast furnaces, and says its system can make full-cycle steel plants as small as 500,000 metric tons per year economically viable. Most steel mills that use a blast furnace to convert raw materials into finished steel produce 3 million metric tons or more annually, making this future plant the size of a so-called “mini mill,” which recycles scrap metal in an electric arc furnace rather than starting with the iron ore.
The 10,000-metric-ton facility the company is currently building will start by running on natural gas, which is still far cheaper than green hydrogen. But Meroueh told me that once green hydrogen falls below $5 a kilogram — and ideally below $3 — she expects it will make economic sense for Hertha to start blending hydrogen with natural gas, potentially in the early 2030s.
Outside the U.S., Hertha could reach ultra-low carbon production even sooner. “So with the really attractive renewable power prices in the Middle East, it makes it a lot more digestible to produce green hydrogen,” Meroueh told me in April. “And the best use case of that green hydrogen is to make steel. Moving hydrogen around in pipelines, not attractive. Converting it to ammonia and then back to hydrogen is not very attractive. Just make the steel right there.”