You’re out of free articles.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:

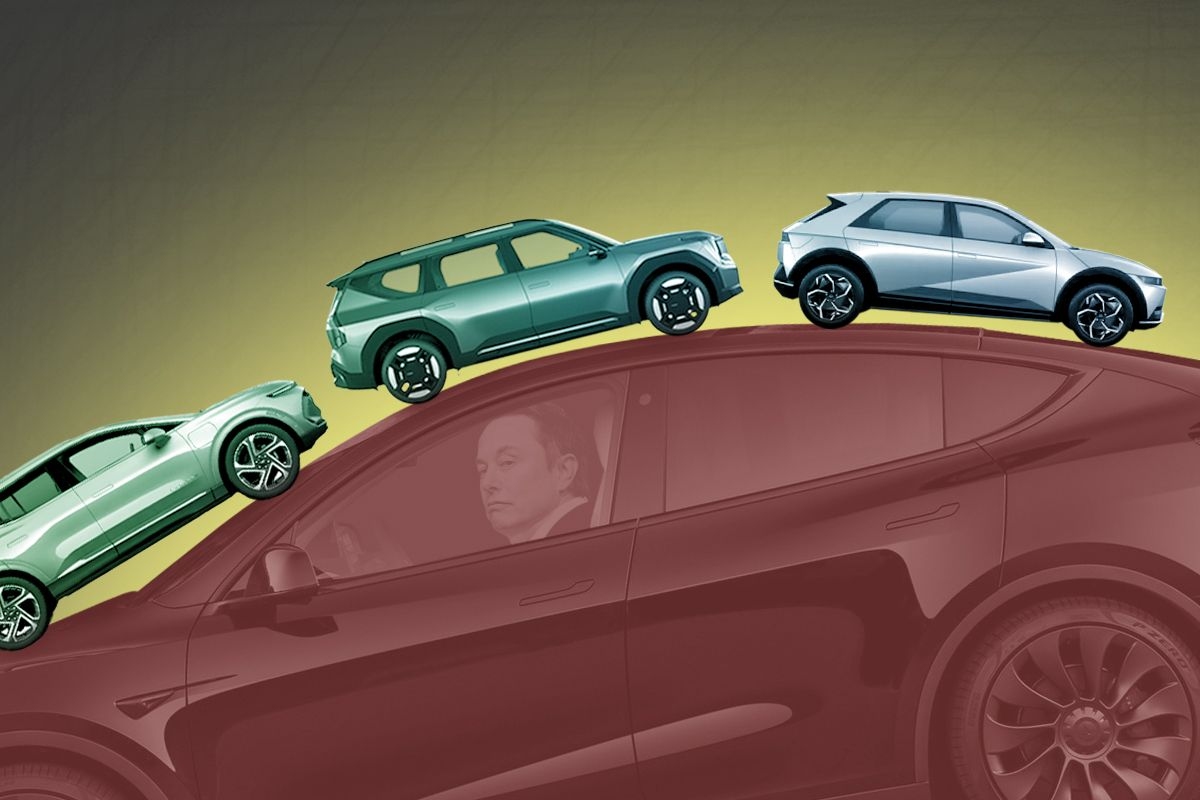
In the closing days of April, Elon Musk shocked the EV world when he laid off Tesla’s entire 500-person charging division.
The company suddenly — and seemingly for reasons of professional pique — gave up on its biggest competitive advantage. At a time when every other automaker was supposed to be moving to Tesla’s best-in-class charging network, Tesla seemed to be abandoning it.
The announcement shot the American EV industry through with fear and seemed to cement the broader industry’s malaise. If Tesla was giving up on EVs and becoming an “AI and robotics company,” what chance did anyone else stand?
More than a month has now passed. Tesla hasn’t released its sales figures yet for May, and it isn’t likely to do so until its shareholders vote on a $56 billion pay package for Elon Musk next week. Given how the company has been acting lately, its sales probably won’t inspire.
But in the meantime, we can take stock of the rest of the industry. And the results have been … pretty good! Hyundai, Kia, General Motors, and Ford all saw their best May ever for EV sales. With little fanfare, EVs continue growing as a share of American car sales and making concerted progress. Tesla’s future business might be a question mark, but EVs have a foothold in the rest of the industry.
Let’s break down the data:
Hyundai, one of the Korean automakers that has emerged as an electric power player in the U.S., says that its EV sales were up 42% nationwide year-over-year. The Ioniq 5, its all-electric hatchback, just had its best sales month ever. It has already sold nearly 21,000 cars in its Ioniq line-up so far this year.
Its Korean partner, Kia, also saw its electric sales double in May, which was Kia’s best month for EV sales ever. For the first time, Kia sold more than 7,000 all-electric cars in one month. Although it’s too early for this to appear in the sales data, Kia also began to produce its three-row SUV, the EV9, at its new assembly factory in Georgia this month, which means that the EV9 will qualify for the full $7,500 tax credit under the Inflation Reduction Act.
So far this year, Kia has sold more than 16,000 EV6 and EV9s. (Hyundai and Kia also sell plug-in hybrids, but they don’t regularly break them out in their monthly sales data announcements.)
American automakers also put up solid numbers. General Motors recorded its best-ever month for EV sales in May — even though it has now stopped selling the Chevrolet Bolt, which was previously the cheapest EV on sale in America. But GM’s new electric platform, Ultium, is starting to fill the gap. Sales of the Cadillac Lyriq, which had previously lagged GM’s cars, are suddenly surging; the vehicle is on track to outsell the Tesla Model X this year. This month, Chevrolet launched the Chevrolet Equinox EV, a two-row SUV starting just around $43,000 that got “surprisingly great” reviews. The Equinox qualifies for the full EV tax credit.
Ford also put up decent numbers: May was its third-best month for EV sales ever. Sales of the Ford Lightning, Mustang Mach E, and E-Transit van were all up by 46% year-over-year, and Ford’s electric sales overall are 88% above where they stood at the same time last year. But Ford, unlike GM, hasn’t announced any new electric cars in the pipeline.
Other good news came not in the form of sales, but in product announcements and updates. The automaker Stellantis — you might know it best as Fiat-Chrysler — disclosed that it will release a $25,000 all-electric Jeep in America soon, based on the same platform as the cheap EVs that it already sells in Europe.
The electric automaker Rivian also made progress on its goal to become profitable by the end of the year. The EV truckmaker has reopened its factory in Normal, Illinois, after retooling and renovating it last month. It also unveiled new versions of its flagship R1S SUV and R1T pickup with more range and new features. While Rivian’s ultimate survival will be determined by its sales in the second half of the year, it is checking the boxes on its plan to stop burning cash by 2025.
“The last two weeks have had good vibes for maybe the first time all year,” Corey Cantor, an analyst at Bloomberg NEF, told me. “A lot of the companies that have had to make progress are starting to make progress.”
The one big weak spot in the month was in charging. As predicted, Musk has hired back some of the charging employees that it laid off five weeks ago, but the rate of its charging expansion has slowed — and no other company has stepped up to fill the gap. GM has said that its EV drivers will have access to Tesla’s network by “spring 2024,” a deadline that will arrive in 13 days. And the charging network funded by the Bipartisan Infrastructure Law has yet to produce more than a handful of stations.
Another point of caution: It’s still unclear whether EV sales in May will fall overall — but that would be entirely because Tesla, which makes up a large share of EV sales nationwide, has seen such slowing deliveries lately. In recent months, EV sales have had a “Tesla problem,” where every automaker that isn’t Tesla sees record growth, but Tesla brings down the overall rate. There’s a positive way to view that trend (the EV transition is broadening beyond Tesla!) and a negative way (fewer folks are buying EVs overall). That could happen again this month: We won’t know until Tesla reports its monthly figures.
Still, even in a year defined so far by big road bumps for electric cars, the direction of travel is good.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
The cofounders of The Impact Project have a three-step test for voters.
In November 2025, Texas Governor Greg Abbott announced a $40 billion Google investment in his state and declared, “Texas is the epicenter of AI development, where companies can pair innovation with expanding energy.” At a campaign stop in East Texas seven months later, he had a different message: “We must prohibit them from building AI data centers in rural Texas neighborhoods.” Last week, Abbott instructed Texas’ environmental agency to stop issuing permits to data center projects until the state’s grid operator completes an audit of all data centers in the interconnection process.
Abbott is not alone. In the past week, three other candidates for governor moved toward limits. On September 23, Maryland Governor Wes Moore, a Democrat, signed an executive order tying state incentives for large projects to a new review process, pledged that “the state will not go around a local community’s ‘no,’” and announced that he would ask lawmakers to repeal the state’s data center tax exemption, passed in 2020. The same day, Kansas Democratic nominee Cindy Holscher, who voted for data center tax incentives as a state senator and now backs a moratorium, said she “certainly would vote differently based on the information we have now.” Teri Ann Hourihan, Arizona’s No Labels candidate, also promised a “Day 1” moratorium on new data centers.
These shifts represent a pattern we’re seeing across party lines during an election season dominated by conversations about data centers and artificial intelligence. At The Impact Project, we track where the candidates for governor stand on data centers: 143 candidates in 36 states and three territories. By our count, 69 of the 78 major party candidates have voiced positions on data centers. Thirty-eight candidates have staked out restrictive positions on data centers, while 31 are supportive, ranging from unequivocal support to reluctant support with significant safeguards and concessions. Importantly, we counted a candidate as supportive if they champion data center development, even if they want a pause or a moratorium to take a closer look first.
Across party lines, candidates appear to be trying to balance environmental and social concerns with economic and technological priorities. At least 30 support a pause, halt, moratorium, or ban, including 20 Democrats and 10 Republicans. In five states — Maine, New Hampshire, Ohio, Oregon, and Texas — the Democratic and Republican candidates both clearly back a pause. Among sitting governors up for reelection, a quarter back a pause; among major party candidates newly seeking the job, 43% do. The 65 third-party and independent candidates lean further toward restriction: We documented positions for 32 of them, including 19 who back a pause, moratorium, or ban. Today, we are making our research publicly available.
Candidates appear to be following voters, whose opinions have shifted rapidly. In September 2025, Americans were evenly divided over whether they would support a data center being built near their homes. By August, 75% opposed one. In Virginia, the share of voters comfortable with a new data center in their community fell from 69% in 2023 to 35% in 2026 in 2026. In May of this year, seven in 10 Americans told Gallup they oppose AI data centers in their area, with the strongest opposition in the Midwest and the South. Voters’ complaints are concrete, concerning water use, air pollution, persistent noise, rising utility bills, and projects negotiated under nondisclosure agreements without neighbor consent.
Candidates should be responsive to their constituents’ priorities, but the electorate is naturally skeptical when candidates shift their positions so dramatically during an election year. These pivots invite questions about whether some candidates’ new skepticism of the data center boom will last beyond November.
In Nevada, Democratic nominee Aaron Ford co-sponsored the 2015 law that created the state’s data center tax abatements. He now promises to pause them. His Republican opponent, incumbent Governor Joe Lombardo, once called data centers the state’s new “gold rush.” On September 18, less than two months before the election, he signed an executive order curbing the tax breaks. Arizona Governor Katie Hobbs, a Democrat, told lawmakers in January that she voted for the state’s data center tax exemption as a legislator, and that she now wants to eliminate it. Wisconsin’s Republican nominee, Tom Tiffany, called data centers “exciting new technology” in January. His campaign now says, “[w]e are America’s Dairyland, not America’s Dataland.”
Pennsylvania’s Republican nominee, Stacy Garrity, was even more blunt: Last summer she praised data center deregulation and expansion. This June, Garrity announced that “we pause for as long as we need the pause.” Garrity’s opponent, incumbent Democrat governor Josh Shapiro, has similarly flipped: Last year, Shapiro celebrated fast-tracking permitting for data center and AI development. This year, Shapiro signed an executive order proposing limits on data centers and has spoken about developers “running roughshod” over communities. In Ohio, billionaire Republican gubernatorial candidate Vivek Ramaswamy called his state’s data center boom “great” in 2025. Now he promises an executive order pausing construction.
Candidates, of course, are allowed to change their minds, and these changes may be sincere. Our understanding of the burdens of data centers is growing along with the industry. The vast AI hyperscalers being built today are not the server farms of 2015, which is how Nevada’s Ford explained his shifting position.
Are we witnessing political convenience or a real change of heart? No one can see inside a candidate’s head. Voters can, however, check three things.
First, does a candidate’s promise come with a plan? Many of the loudest pledges are for a “Day 1” executive order. Executive orders are the easiest policy to make and the easiest to undo, and a pause is hollow without regulatory action to follow it up. We can ask what bill language the candidate would support, what it would require, and what happens the day a proposed pause ends. We can also question whether the candidate can deliver. Utility rates are set by public utility commissions, not governors, and tax incentives are written into law. A governor can stop new deals, but signed deals keep running. Lombardo’s order, for instance, applies only to companies seeking new tax breaks.
Second, does the plan require disclosure? We cannot regulate what we cannot measure. Many candidates describe their pause as time to study the problem. Maryland’s Republican nominee, Dan Cox, wants a moratorium “so that we can study this.” A study needs data, and data centers developers and operators are famously opaque. As data is so infrequently available directly from data centers, journalists, activists, and researchers have resorted to techniques as varied as satellite imagery, public records requests, thermal drone footage, tax document sleuthing, and human tips to collect data and break news about data centers. Yet fewer than a quarter of candidates who call for a pause call for mandatory disclosure. A pause without reporting requirements ends where it started: without the facts needed to regulate.
Third, what did the candidate do before this was popular? Votes, signed deals, and ribbon cuttings are public record. A candidate who switched should be able to say what changed and what they got wrong. One who cannot is asking voters to trust the new position on faith.
After November, voters can keep score. Watch the first legislative session and the first budget. Do data center incentives come back under a new name? Does a “Day 1” pause end with rules, or does it simply end? Communities have already shown what accountability looks like locally, where residents have recalled officials and replaced council members who approved unpopular projects. Governors deserve the same attention.
What voters want is reasonable. When a Michigan poll asked about a data center within 25 miles of home, 55% said they were not open to it, 11% were not sure, and only 33% said they were open to it. After hearing a set of protections, including no rate hikes, no tax incentives or secret deals, and closed-loop cooling, 49% said they would be open to one. What most voters oppose is data centers without rules.
Americans are demanding change, and data centers are top of mind. Candidates who mean what they say will make good on campaign promises by writing rules and passing them. The rest will let their hollow promises lapse and hope no one is counting. We all should be.
The renewables developer is expanding its business to serve “our nation’s growing energy needs.”
Two years ago, Arevia Power marketed itself as a renewable energy development powerhouse founded by solar industry veterans.
Today, the company is now also building data centers and gas turbines, Arevia chief development officer Ricardo Graf confirmed in a statement to me.
“Arevia is an energy company that delivers reliable and affordable electricity to the communities and utilities we serve,” Graf told me via email, acknowledging that “in some cases, that energy may be solar; in others, it may be gas.” He added that “yes, we also develop data center projects, but ones with accompanying power solutions to ensure ratepayers are not impacted by the data center’s energy needs.”
I’ve been keeping a close eye out to see whether any renewable energy developers, faced with the Trump administration’s squeeze on federal permits, will bet on diversifying their businesses. Maybe if they couldn’t build a solar farm on federal lands or access ample federal tax credits for constructing new projects, they’d invest in other sorts of large infrastructure projects instead.
We’ve definitely seen large U.S. energy developers such as NextEra and Invenergy take Trumpian tacks towards supplying data centers with new gas power under. Over the summer I broke the news that Clearway Energy asked the Bureau of Land Management to change a five year-old application for solar farm permits with “a proposed data center and natural gas facility.” After those plans were made public, Clearway told me in a statement to me that it was nixing the idea because it did not comport with their business strategy. “As a clean energy developer and operator, our focus in Nevada remains solar and battery storage.”
In mid-September, D.C. news outlet The Washington Sun first reported that Rhea Data, a subsidiary of Arevia Power, was behind the proposal for a giant data center and energy complex in Idaho including thousands of acres of federal land. On Thursday, the Bureau of Land Management sent me a statement confirming key details such as the inclusion of a 450-megawatt on-site gas facility. The next day, a Nebraska public radio station reported that Arevia and Graf were connected to prospective early-stage data center project site evaluation outside the city of Lincoln.
When I asked whether the company was reorienting itself toward data centers and the gas energy business, Graf acknowledged how things looked. “While this may be perceived as ‘pivoting,’ it is just a product of the evolution of our nation’s growing energy needs, which solar alone cannot satisfy,” he said over email on Friday. “Our company takes an all-above approach to helping our nation meet its increasing power demands.”
A new study from energy company Foundry-Logic argues that simply replacing old solar panels could add significant new capacity to the grid.
All across the United States, solar panels are withering on the vine. Equipment installed 10 to 15 years ago is still capturing sunlight and pumping out electricity, but significantly less of it than when the cells were new.
This is not a story about decline, however, but about growth. America’s aging solar farms represent an opportunity to expand clean energy capacity without using more land — and potentially without having to wait years for new projects to get through the grid’s interconnection queue.
Modern panels can produce as much as 70% more energy than new ones sold 20 years ago, according to Wood Mackenzie. A report published Monday estimates that “repowering” existing solar farms, or replacing old panels with new ones, could unlock about 9.6 gigawatts of solar power by 2030, 29 gigawatts by 2035, and 67 gigawatts by 2040. (For comparison, the U.S. added 27.2 gigawatts of utility-scale solar last year.) If every project up for repowering between now and 2040 installed batteries, as well, that would add up to 13 additional gigawatts of storage to the grid by 2030, and nearly 92 gigawatts by 2040. The U.S. has just over 50 gigawatts of storage online today.
That means repowered solar farms could supply about a third of the growth in peak demand the North American Electric Reliability Corporation expects to be driven by data centers by 2035, the report found.
“Solar is entering its first replacement cycle at this moment when we are seeing a structural increase in demand,” Lisa Hansmann, the director of energy company Foundry-Logic and one of the paper’s authors, told me. “The more we dug in, the more it became clear that this market is early, but it is fast growing and ultimately could be very large.”
Advances and cost declines in battery technology are key to harnessing this generation potential. If a developer wants to increase the output of their solar farm, they’ll likely have to get a new interconnection agreement, which can take years. Adding a battery to ensure the plant doesn’t send more power to the grid than it was initially approved for can help avoid that, although it depends on the specs of the project, the location, and regional regulatory requirements.
Foundry-Logic, which published the paper in partnership with the clean energy finance company Crux, is focused on “getting more out of the installed base of energy systems.” The paper, in other words, is essentially Foundry-Logic’s sales pitch. It estimates that when combined with battery storage, repowering will represent a $10.8 billion market in 2030, growing to $51.8 billion by 2040.
The estimates are certainly on the high end of what’s possible, however, as the authors looked at technical potential rather than regulatory or economic feasibility. While the first half of the paper highlights the reasons repowering can be so attractive — existing interconnections, land leases, and permits — the second half digs into the real-world conditions that complicate that narrative.
The Federal Energy Regulatory Commission requires regional transmission organizations to offer “surplus interconnection service,” rules that allow new generators to skip the interconnection queue if they connect to the grid using the same infrastructure as an existing power source, so long as there’s “surplus” room to connect at that node. The rules vary throughout the country, however. The paper finds that the Midcontinent Independent System Operator, which covers much of the Midwest, has the most favorable regulations for repowering, followed by the Southwest Power Pool, which covers the swath of the country between Montana and the Texas panhandle. In the nation’s largest transmission region, PJM, the surplus interconnection process has historically taken nearly as long as the queue, but the regional operator recently indicated it’s considering reforming the process.
Requirements also vary widely depending on the type of project — utility-scale versus smaller solar farms versus rooftop arrays — as well as by state and region. Utility-scale projects require interconnection agreements from regional transmission operators, while smaller projects connect at the local distribution level with permission from the relevant utility.
“Policy is evolving to meet the market demand for speed to power, and that's one of the things we tried to highlight too,” Josh Price, the director of market intelligence and research at Crux, told me. Because of the data center buildout and surging energy demand, he said, state regulatory commissions have started to push their utilities to examine their distribution systems, identify where there’s available interconnection capacity, and create rules or pilot programs to leverage it.
Price added that another advantage to repowering projects is that developers don’t have to start the financing process from scratch. In most cases, they already have a lender, an equity sponsor, and potentially a tax equity partner. They might need to renegotiate terms, but they also have 10 to 15 years of real-world data into how solar performs at the site, making it a less risky investment than a brand new development.
I spoke with one solar farm operator, CleanCapital, which owns many smaller sites throughout the country that were built in the early 2010s “and are needing more love,” as Zoe Berkery, the company’s chief operating officer, put it to me. The first step in deciding what to do with them, she said, is to try to extend the offtake contract for the power. “Otherwise, there would be no justification for pouring in so much additional capital into a site that may be rolling off in just a couple of years, so that piece has been something that CleanCapital has focused on pretty intensely over the last, I would say, six years,” she said.
CleanCapital has repowered some of its projects, but only to restore the original generating capacity. It has not yet added batteries to any legacy sites. Berkery said the company looked at adding batteries in New Jersey and California, but has not been able to make the economics work. “I do think there's a lot of potential there,” she said. “It just depends on the site, the space, the market.”
Hansmann told me that a lot has changed in the past year to make it easier to add batteries to existing solar sites, including new ways to get paid for energy storage, such as through participation in virtual power plants. For example, in June, Google announced it would fund a virtual power plant in PJM run by the company Voltus, which will aggregate batteries from homes and businesses, among other distributed energy resources.. “For the first time, you're having the technical potential and the commercial potential line up in a very interesting way.”