You’re out of free articles.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
Spoiler: None of them feels great.

“Delete, delete, delete,” Elon Musk reportedly told his biographer, Walter Isaacson, describing his approach to management. “Delete any part or process you can. You may have to add them back later. In fact, if you do not end up adding back at least 10% of them, then you didn't delete enough.”
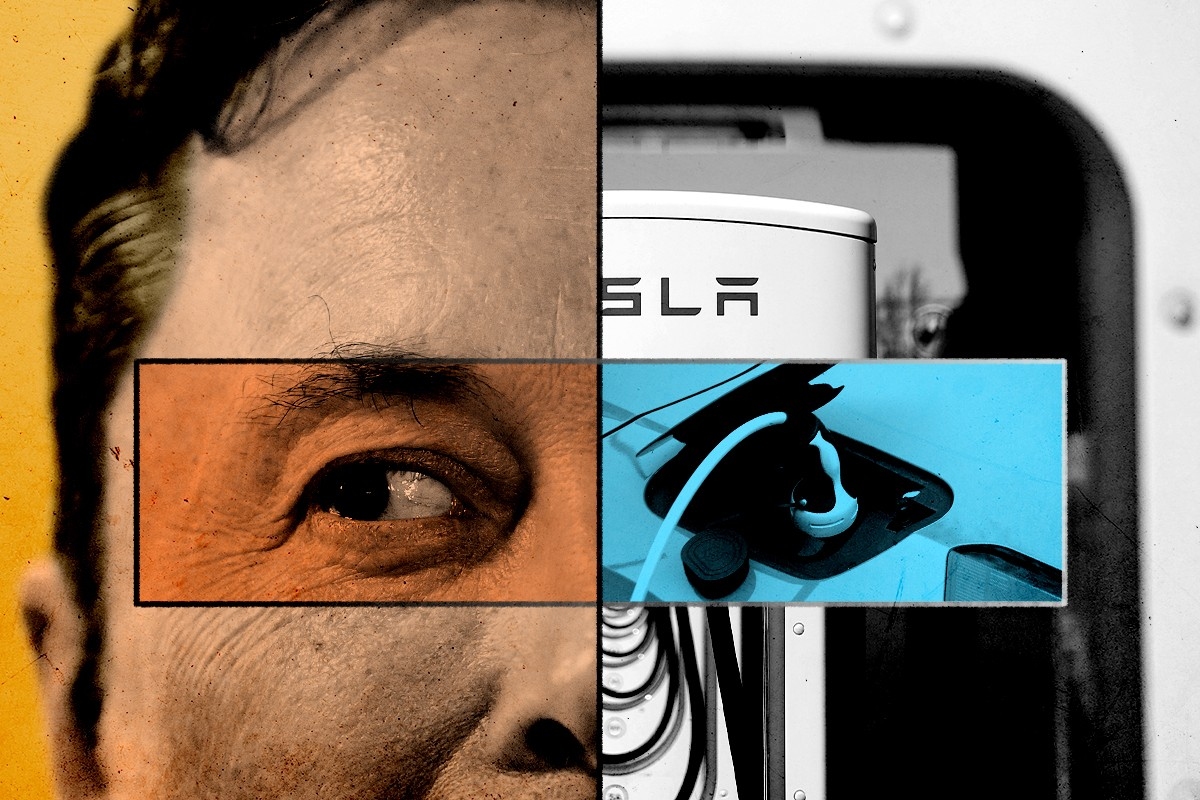
Musk has taken his own advice: He is slicing to the bone. Earlier this week, he dismissed the head of Tesla’s Supercharger network, Rebecca Tinucci, as well as her more than 500-person team. As of today, Tesla has only a barebones crew, at best, tasked with maintaining and expanding its high-speed car charging network. It has already pulled out of a planned expansion in New York City.
Musk also laid off what remained of the company’s policy and new vehicle teams. These severe cuts follow layoffs announced in March, when Musk dismissed about 10% of Tesla’s employees. According to Electrek, the two events may be related: Musk asked Tinucci to make deeper cuts in her team in April, she pushed back, and he fired her to set an example. The company has cut more than 14,000 employees worldwide since the beginning of the year.
The news is — and there is no way of sugarcoating this — either sort of stupid, bad, or very bad for the electric vehicle transition. Here are three ways of looking at it:
Over the past year, every other major automaker in the United States has switched to Tesla’s charging plug, the North American Charging Standard, or NACS. They have struck deals that will let them use much of Tesla’s existing Supercharger network; Ford is in the process of mailing its drivers a free NACs adapter plug. These agreements were meant to give consumers more certainty about the EV transition: No matter what car they bought, they would be able to use most of Tesla’s superior charging network.
Now, that certainty is gone. Which chargers will work in the future? How much more will the Tesla network expand? And what will happen to those deals with automakers now that the Supercharger team is gone? The employees laid off this week included those who worked closely with other companies.
At least publicly, Ford is keeping its cool. “Our plans for our customers do not change,” Marty Günsberg, communications director for Ford’s electric vehicle division, told Heatmap. And yet contractors and others with business in front of Tesla's charging team were left completely in the dark Tuesday, their emails bouncing back from addresses that no longer existed, according to E&E News. No other equivalent charging network exists in the U.S., meaning there's no other easy place for them to go.
Musk, for his part, has intimated that the company will begin to look into wireless charging. Although wireless charging may make slightly more sense for self-driving cars — the car could drive itself into a given spot, et voilà! — it is a puzzling decision from a man who has said the only real constraints are those imposed by the laws of physics. More than half of current and prospective EV owners say that they worry about charger availability and convenience, yet wireless charging is slower and less efficient than wired charging, meaning it will require more charging spots and each vehicle will have to stay there longer.
So again we must ask, why? The answer may lie in the animal spirits of the market — and Elon’s dependence on the market for his personal wealth. Tesla’s stock has more or less held steady since the cuts. As my colleague Matthew Zeitlin wrote, Musk has spun the layoffs as part of a corporate turn away from selling electric vehicles, chargers, and home batteries and toward achieving artificial intelligence and autonomous driving.
That is partly because Musk must keep justifying — or, if we really want to be blunt, propping up — Tesla’s astronomical share price, which itself is premised on the idea that Tesla is a technology company, not a car company. In order to do that, he must continually steer his sometimes-profitable company toward the buzziest, most hyped-up phenomenon in the economy. Never mind his actually existing EV charger business; that can’t justify the fantasy of the share price. He needs to find something new.
One of the more useful ways of understanding Elon Musk is that he seeks to create and control private infrastructure. SpaceX creates privatized access to rocket launches. Starlink allows for privatized access to the global, satellite-provided internet. The Hyperloop — to the degree that it existed at all — sought to create a privatized and individualized form of mass transit. (Musk, fittingly, hates public transit.) Even Musk’s purchase of Twitter, now rechristened X, reflected a desire to enclose the public sphere.
And for the past year, you could understand Tesla in the same light. Sure, Tesla was an electric vehicle company. But it was rapidly becoming an infrastructure company. Through its deals with other automakers, it was cementing itself as the premier provider of electric vehicle charging in the United States. It was also the part of the company that elicited the least suspicion from Tesla’s many critics. Drivers might not always be able to rely on a third-party charger, but a Tesla Supercharger? It worked.
It hasn’t always been this way. For years, the Supercharger network seemed like Tesla’s key competitive advantage, its Warren Buffett-style moat. If you wanted access to America’s most famous and reliable fast-charging network, you had to buy a Tesla. But starting with Ford a year ago, Musk struck deals with other automakers allowing their cars to use some of its charger network. At the same time, Tesla also bowed to federal pressure and standardized its NACS charger with SAE International. That helped it win more than $17 million in grants from the Bipartisan Infrastructure Law to build even more chargers.
Why pull back now? None of the options is very encouraging. The most hopeful answer is Tesla-specific: Maybe demand for the automaker’s vehicles is sinking so quickly that Musk is, in essence, reaching for things he can throw overboard. Tesla has historically relied on Chinese consumers to buoy its sales, but it has hemorrhaged market share in China as the country’s home-grown automakers have come out with newer and often superior EVs. But things there took a turn for the better earlier this week as Musk won approval (albeit conditional) to use Tesla’s so-called Full Self-Driving software on Chinese roads. And even if a sales slump were the explanation, why also ditch the team working on new vehicles at Tesla?
The other possibilities are bleaker. BloombergNEF has ballparked that Tesla’s charging business could generate $740 million in annual profits by 2030. But that relies on Musk’s estimate that the Supercharging business has a 10% margin. If that margin has since shrunk — or if its chargers just aren’t getting used as much as Tesla once anticipated — then further investment right now might not make sense.
That’s a problem, though, as most prospective buyers say that there need to be even more public chargers before they would consider buying an EV. If the economics don’t justify a further investment in chargers, however, even with all that apparently pent up demand, then the country is in a pickle. In that case, Musk’s decision looks self-defeating, a panicky and downturn-averse reaction that will ultimately undercut the market for Tesla’s cars.
About the only bright spot here is that Musk has surrendered hundreds of the most talented charging employees to the market. Tesla excelled at using a mix of policy and engineering prowess to integrate their chargers into local utilities’ systems and rate structures; other automakers can now snap up the people with those skills.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Current conditions: Severe storms are drenching a broad swath of the Midwest with heavy rain from Des Moines to Fort Wayne • Intense downpours put all 76 of Thailand’s provinces, or changwat, on a five-day flooding alert, ending on Sunday • Tropical Storm Dujuan has strengthened in the Pacific en route to Japan.

The Trump administration has narrowed the federal government’s interpretation of the Endangered Species Act to only consider intentional targeting of protected animals illegal. The move, part of what The New York Times called “a seismic shift” in the application of one of the nation’s bedrock conservation laws, would essentially free energy companies from the need to, for example, invest in infrastructure to keep migratory birds from making deadly landings in ponds of oil and gas slurry. Killing endangered animals “almost always happens incidentally, in the course of economic activity,” the newspaper noted. It’s unclear whether the legal change would also apply to one of the industries President Donald Trump most frequently antagonizes for its accidental killing of birds: the wind industry.
When President Donald Trump announced an energy truce between Ukraine and Russia, he promised that a halt to attacks on pipelines and refineries would lower prices on diesel worldwide, insisting the Iran War wasn’t to blame. But half of Russia’s six top diesel-producing refineries were forced to significantly cut back or completely stop production this month due to damage from Ukrainian drone attacks, according to a Reuters analysis published Wednesday. Russian President Vladimir Putin, meanwhile, is making a $135 billion bet on Arctic oil that OilPrice.com suggested “could save his Ukraine war.”
U.S. energy companies, meanwhile, are storming into a country in America’s backyard that — unlike the Kremlin’s attempt at a blitzkrieg capture of Kyiv’s leaders in 2022 — successfully decapitated a rebellious regime and reasserted Washington’s regional dominance. I’m talking, of course, about Venezuela. Harold Hamm, the oil tycoon behind the U.S. shale boom, told the Heartlander News yesterday that his company had signed a tentative agreement to explore one of the South American nation’s oil fields. New York-based Heeney Capital is eyeing a gold mine in Venezuela, per Reuters. Bloomberg reported that the company is also looking to ship aluminum from Venezuela to the U.S. Exxon Mobil, meanwhile, is “nearing a preliminary deal” to invest in Venezuela oil, according to The Wall Street Journal.
The Federal Reserve raised the benchmark federal interest rate by a quarter point Wednesday. The U.S. central bank’s first rate change since Chairman Kevin Warsh took over in May, and its first rate hike since 2023, will bring the federal funds rate to between 3.75% and 4%. The increase could make raising capital “more difficult” for “capital-intensive renewable and clean energy industries,” my colleague Matthew Zeitlin wrote yesterday.
Sign up to receive Heatmap AM in your inbox every morning:
Lawmakers in the House of Representatives overwhelmingly passed the first major bill to curb the costs of the AI boom with legislation Politico described as “intended to shield Americans from potential energy costs associated with data centers.” The Ratepayer Protection Act passed in a 417 to 3 vote. The bipartisan win hands the GOP a victory ahead of the November election on one of the issues firing up voters the most. The bill would require states to consider a federal standard guaranteeing that large power consumers pay for 100% of the costs of new generation and transmission upgrades, but falls short of a direct mandate.
Meanwhile, the House split along partisan lines for another bill on California’s right to regulate pollution more strictly than the federal government. The chamber voted 216 to 211 to bar California from setting strict new limits on air pollution from ships docked at the state’s ports, marking what The New York Times called “the latest salvo by Republicans against the state’s pioneering environmental policies.” The move comes after Congress last year banned Sacramento from imposing a ban on gasoline-powered vehicles by 2035.
One of the most significant nuclear stock market debuts of the past few years has hit a major hiccup. On Wednesday night, Holtec Nuclear Corporation suspended plans for an initial public offering, citing “market conditions.” Bloomberg and Reuters first reported the postponement, which I confirmed with Holtec last night. “Holtec will continue to evaluate the timing of the offering in the future,” the company told me. With plans to restart a nuclear reactor for the first time in U.S. history in the coming months, Holtec is the only company likely to bring (somewhat) new atomic electricity onto the grid before 2030. The company owns several other decommissioning nuclear plants, where it plans to build its own in-house small modular reactors.
Another major player in the burgeoning nuclear market, meanwhile, hit a major regulatory milestone. Blue Energy, a developer that bills itself as “agnostic” to reactor technologies, is instead focused on building facilities that will initially run on gas and eventually transition to reactors, with GE Vernova Hitachi Nuclear Energy’s BWRX-300 — the closest rival to Holtec’s SMR-300 — centering in those plans at the moment. On Wednesday, Blue Energy submitted its application for a construction permit to the Nuclear Regulatory Commission for its inaugural gas-to-nuclear project in Port of Victoria, Texas. The submission makes Blue Energy one of just five companies so far to ask the NRC for permission to begin building. “This is serious work done by serious people for a serious project,” Blue Energy CEO Jake Jurewicz said in a statement. “This is another huge step towards building the world’s first gas-to-nuclear power plant and proving the Blue Energy approach to build nuclear in the safest, quickest, and most scalable way possible.”
The wine-dark sea is getting more briny. As its temperatures rise faster than the global ocean surface average, the Mediterranean Sea is growing saltier. The upper 100 meters of the sea between Europe and Africa have been about 2 degrees Celsius warmer than their 1950 to 1999 average, according to a study published in Geophysical Research Letters. “For us, what was alarming was the rate at which this is changing and the depths that such significant changes reach,” Elena Terzić, a physical oceanographer at the Ruđer Bošković Institute and lead author of the study, told Bloomberg. “The warming and salinification are statistically significant down to three or four thousand meters, and the speed-up itself reaches down to about 2,500 meters.”
The company plans to invest in domestic manufacturing for its high-heat magnets.
Our electricity system runs on magnets. Every transformer stepping voltage up or down, every inductor smoothing out electrical current, and every motor turning electricity into motion relies on the same basic physics: magnetic fields that control the flow of electrons, converting, filtering, and transporting power at every stage. But as AI and electrification push the grid to its limits, better magnetic materials can help power electronics — and our grid itself — keep up.
That’s the bet behind CorePower Magnetics, a Pittsburgh-based startup which raised a $10.5 million funding round co-led by Engine Ventures and Material Impact, announced on Thursday. The startup is developing more efficient, power-dense components such as inductors and transformers using proprietary nanocrystalline magnetic materials, whose ultra-fine grains reduce energy loss. While these materials have historically been brittle and limited to operating at temperatures below 150 degrees Celsius, CorePower says it engineered alloys that can perform above 200 degrees while maintaining durability.
That higher temperature ceiling is critical. As surging electricity demand meets our increasingly complex grid, power electronics like inductors and transformers are being pushed to handle more power, greater voltages, and higher frequencies than ever before. Magnetic material that can run hotter allows engineers to push more power through smaller components. In the context of a data center, for example, that could equate to about a 10% overall reduction in power demand, CorePower’s CEO Sam Kernion told me
“Data centers are the tip of the spear for this really big push into power electronics,” Kernion explained. “If you look more broadly, electricity demand is growing, but the grid itself is becoming a lot more complex, and data centers are just a great example of that.”
Traditionally, electricity flowed unidirectionally from large, centralized power plants to homes, businesses, and other end users. But now the system must support a wider array of both generation and demand sources. Distributed energy resources like rooftop solar panels can generate power directly where it’s consumed, while batteries (and soon electric vehicles) can both draw power and send it back to the grid. Today’s standard electrical equipment isn’t built to handle the bidirectional power flow and real-time current and voltage conversions that this new ecosystem demands.
Solid-state transformer startups such as Heron Power and DG Matrix are tackling this same challenge, using advanced semiconductor technology to convert voltage electronically while also handling functions like bidirectional power flow and alternating-to-direct current conversion. But even these newer systems still generally rely on conventional magnetic materials, which CorePower says have become a key bottleneck.
“We’re taking a car engine, and now we’re going to a jet engine in terms of how different this is,” Kernion told me regarding the demands of this new, higher performance operating environment.
CorePower is designing its advanced, medium-frequency transformers to operate across a broad range of frequencies, from 10 kilohertz to 100 kilohertz. Eventually it plans to sell these transformers to power electronics manufacturers, which will build complete, solid-state systems around the startup’s magnetic core, adding components such as semiconductors and capacitors along with their own software and control systems.
While CorePower hasn’t disclosed any customers to date, it did launch its first product last year, a standardized, low-voltage inductor that’s smaller, lighter, and more efficient than the industry standard. The device smooths out current in power conversion systems, including data center distribution equipment, EV chargers, and inverters that convert DC electricity to AC. Next, CorePower is preparing to launch its standardized transformer product.
The company’s magnet tech could ultimately find numerous applications beyond inductors and transformers. “We’re also able to supply onboard magnetic components for EVs, or uninterruptible power supplies at data centers, or inverters for renewables,” Kernion explained. “Every electron everywhere passes through a magnetic component at some point, so there’s a whole bunch of opportunity out there.”
It’s certainly a fortuitous time to be a domestic power electronics manufacturer. Last month, President Trump signed an executive order banning the import of certain foreign-made bulk power equipment, including substation transformers and grid-connected inverters. While CorePower is mainly focused on producing high-performance equipment that Kernion says can’t currently be sourced domestically or abroad, the push to shore up domestic manufacturing is providing a tailwind for another of its new business lines: amorphous ribbon, a traditional alternative to the electric steel used in conventional distribution transformers on the grid.
With this latest funding, CorePower plans to expand its team and increase manufacturing capacity at its 10,000 square foot pilot manufacturing facility in Pittsburgh, which it was able to complete thanks to a $5 million ARPA-E grant. The company is eventually looking to move into a larger, 100,000 square foot facility in the region to scale its material and component manufacturing further, though there’s no confirmed timeline for this yet.
One of the largest companies in the world says its products pose catastrophic peril. Sound familiar?
This is an edition of Heatmap Daily, an evening review of the day’s news written by our executive editor. Sign up for it here.
Imagine, for a moment, a vast and growing firm — a conglomerate that could be said to define its era of American capitalism. Over the past several years, this firm’s products have become the biggest story in the U.S. economy. Its products are so mindbogglingly expensive to produce that they have driven new types of financial and infrastructural innovation, yet nevertheless the company seems to be quite profitable.
And little wonder: Everyone wants what they have. Investors, policymakers, and economists believe that America’s ongoing economic growth and competitiveness depend on ample access to this company’s products. The sitting Republican president has staked his administration on making sure Americans can get as much of it as they want — regulations be damned.
But there is a problem. One of the company’s researchers has become convinced that the company’s products are dangerous — so harmful, in fact, that their continued use and growth trajectory portends catastrophic risk for humanity. He attempts to alert the company’s executives to this fact. What happens next?
Perhaps you know the story. In the late 1970s and early 1980s, Exxon’s internal scientists concluded that the ongoing growth of fossil fuels would raise global temperatures and have “potentially catastrophic” effects on the planet’s climate. They presented these results to Exxon’s executives. A senior scientist warned that humanity had a brief window — “five to 10 years” — before “the need for hard choices regarding changes in energy strategies might become critical.”
Exxon led a large research effort into climate change, affirming its scientific validity. But then in the late 1980s, its CEO decided to go in the other direction. Its executives chose not to warn the public about climate change — and instead began a successful disinformation campaign meant to convince the public that climate change was not settled science.
But what if things had gone differently? We’re getting a taste of that pathway now. Last week, Sam Coxon, a researcher at the artificial intelligence company Anthropic, resigned because he feared the AI industry was too close to building an “out of control” intelligence. He quit his job just a few months before his corporate equity would have vested, giving up what would have likely been life-changing wealth to warn about what he believes to be existential risks. Humanity only had a brief period of time — perhaps a year — to steer the technology to a better path, he said.
Anthropic researchers who remain at the company affirmed his analysis. “We really do earnestly believe AI could kill all humans,” a senior scientist at the company posted on the social network X.
But this time, Anthropic’s CEO, Dario Amodei, did not respond as Exxon’s leadership did three decades ago. Instead, Amodei basically agreed with Coxon: He asked for the government to regulate artificial intelligence and “pace the frontier,” meaning that it should enforce a slower rate of cutting-edge artificial intelligence development.
I’ve thought of these two examples over the past few days as I’ve tried to make sense of the surge in public concern about AI and existential risk.
It seems to me that climate change is looming over the AI conversation and shaping the assumptions, outlook, and behavior of many key players and observers. President Trump, of course, is reading from the old playbook and has deemed AI to be a “hoax”; Coxon, appearing on Fox News, has downplayed climate change’s existential risk as compared to runaway AI. Yet even beyond those reruns and revisions, the analogy goes deeper: Just as nuclear non-proliferation agreements structured early attempts to regulate global greenhouse emissions, climate policy is now shaping how people understand AI risk.
And not for lack of cause. In some important ways, the problems — or alleged problems, depending on your perspective on AI — resemble each other. For instance, because technology exists in a global commons, any successful AI diplomacy must involve the United States and China. And since China’s AI development currently lags the United States, American politicians must persuade China that their proposals to regulate AI are not just concealed attempts to restrain China’s development.
This dynamic has long bedeviled climate negotiations, too. Since economic growth has (until very recently) required fossil fuels, China and other middle-income countries have long feared that any global climate treaty would constrain their future economic development. The Kyoto Protocol tried to finesse this problem by splitting countries into two groups, rich and not-rich; the Paris Agreement did it by imposing no collective restrictions on fossil fuel consumption at all.
Neither approach has worked, exactly, but each offer examples, counterexamples, and tools for thought. Perhaps the Montreal Protocol, which has successfully limited global production of the pollutants destroying stratospheric ozone — and has shown how to stop the growth of a dangerous but hard-to-manufacture technology that presents near-term existential risk — is a superior model.
There is at least one big way the two risks differ. Climate change is a chemical problem that arises from the size and scale of global fossil fuel consumption. Scientists have known that the greenhouse effect is real since the early 20th century. Climate change’s physics are rudimentary enough that Exxon’s in-house scientists could predict the path of future warming with some accuracy. It is a verifiable risk.
AI’s alleged existential risks, on the other hand, emerge from a lab pushing the technological frontier too far and drilling, like Tolkien’s dwarves, too deep. AI concern relies not on empirical observations, but on a story about exponential change and runaway growth. In this way, it’s a harder risk to predict, and a harder one to accept.
Climate advocates have long wondered what would have happened if Exxon’s leaders had embraced reality and warned the public in the 1980s that global warming is real and caused by fossil fuels. Inside Climate News once called it a “road not taken.” I can’t help but wonder if we’re watching it.