A new era of transparency for corporate sustainability is coming — finally. After two years of deliberation, the Securities and Exchange Commission is expected to issue a final rule requiring public companies to make climate-related disclosures to investors. The decision could come as soon as next week.
The rule considers two categories of climate-related information relevant to investors: greenhouse gas emissions and exposure to climate-related risks like extreme weather or future regulations. While many companies voluntarily disclose this kind of information in other ways, the rules will both require and standardize climate-based reporting as a core part of a company’s fiduciary duty.
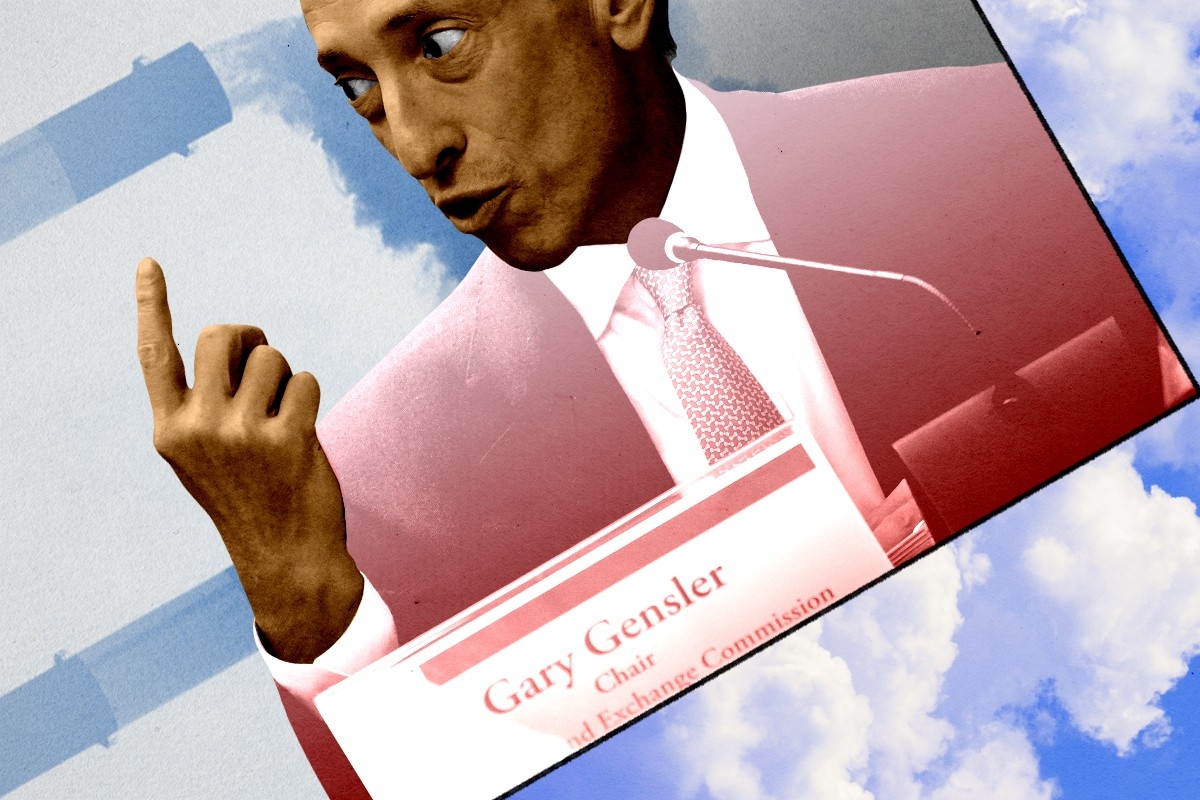
From almost the moment it appeared, the proposal has been the center of a lobbying firestorm. Some of the rule’s opponents write it off as part of an activist agenda — an indirect route to economy-wide carbon regulations. “The host of new requirements in this Proposed Rule are motivated by a small number of environmental activists who seek to steer the economy away from fossil fuels,” wrote twelve Republican attorneys general in a letter to the SEC responding to the proposal. The U.S. Chamber of Commerce, meanwhile, vowed to fight back against “unlawful and excessive government overreach.” (At a Chamber-sponsored event last October, SEC Chair Gary Gensler joked, “Wait, are you already suing us? I just walked in.”)
Certainly there are environmentalists who do see the rule as a tool to undermine the oil and gas industry. But proponents primarily make the case that the stakes are less about the atmosphere and more about protecting investors and the entirety of the financial system.
While we’re still waiting on the final rule — which was originally expected in the fall of 2022 and has been repeatedly delayed — here’s a catch-up on what we know so far.
Why is the SEC doing this?
At a basic level, the SEC makes rules saying what companies have to disclose and how so that investors can make well-informed decisions. The two types of information this particular rule covers — climate-related risks and greenhouse gas emissions — are distinct, but related.
The former is pretty straightforward. From the growing number of billion-dollar weather- and climate-related disasters in the United States to the ongoing exodus of insurance companies from fire and flood-prone areas to trade delays in the drought-stricken Panama Canal, it’s clear that climate change poses a substantial financial risk to businesses. It makes sense that investors would want to know how exposed a company’s warehouses or data centers or trucking routes are to wildfires and floods.
But why should investors care about a company’s emissions? Because they are an indicator of another type of risk.
“A shareholder is not necessarily concerned with whether a company is ‘on target’ with any climate commitment,” Boston University law professor Madison Condon writes, “but rather in assessing how exposed an asset may be to changes in global or local climate policy, energy prices, or shifts in consumer and investor sentiments.”
These changes are already in motion around the world, and are generally accelerating. Companies that aren’t preparing could be disadvantaged, or alternatively, could miss lucrative opportunities. Steven Rothstein, a managing director at the nonprofit Ceres, gave the example of the steel industry. If you think that, in the next several years, customers are going to ask for low-emission steel — which some already are doing — or that there might be a regulatory cost put on steel-related emissions, then a company with lower emissions will be better positioned to grow, while a company with higher emissions might have to spend a bunch of money to retrofit its factories.
Are investors actually asking for this?
Part of the SEC’s rationale for the rule is the proliferation of investor-led initiatives calling for government-mandated climate risk disclosure. “These initiatives demonstrate that investors are using information about climate risks now as part of their investment selection process and are seeking more informative disclosures about those risks,” the Commission wrote in its proposal. (Oil giant Exxon filed suit against the sponsors of one such proposal in January, having lost patience with proposals it said were “calculated to diminish the company’s existing business.”)
After the draft rule was released in March 2022, the SEC was bombarded by thousands of comments from investors, academics, NGOs, politicians, trade associations, and companies. One analysis of those comments by legal researchers found that investors were the most supportive group, with more than 80% in favor of the rule.
What are the major points of debate?
The most contentious aspect of the proposal invited criticism even from parties that were generally supportive of the rule. The SEC had taken a strong stance on emissions reporting, asking companies to disclose emissions indirectly related to their business, known as“scope 3” emissions. That means a company like Amazon wouldn’t just have to report the emissions from its warehouses and delivery trucks, but also an estimate of the emissions associated with producing and using all the products it sells. A company like Ford wouldn’t just have to report the emissions from its factories, but also from the production of the raw materials it uses, as well as from all the gasoline burned in the cars it sells.
Those in support of scope 3 reporting point to the fact that for many companies, including the two I just named, the number would vastly exceed their direct emissions.
In a legal review of why scope 3 emissions reporting matters, Condon warned that without it, companies could begin outsourcing their most emissions-intensive processes to third parties in order to appear greener than they actually are. She also argued that leaving out scope 3 obscures climate risks. She gave the example of electric vehicles, which can involve higher emissions during production than conventional cars but result in much lower emissions over their lifecycle. “When excluding Scope 3, an EV manufacturer is penalized, even though from the perspective of considering transition risk and climate impact, this makes little sense,” she wrote.
But companies and their trade associations threw every excuse at the idea of a scope 3 requirement: It would cost too much to gather the data; the data on supply chain emissions is unreliable and impossible to verify; since companies don’t directly produce these emissions, they aren’t relevant; etc.
And by all accounts, they won. The SEC is expected to drop requirements to report scope 3 emissions in the final rule.
However, that’s unlikely to satisfy opponents, many of whom, like the Republican attorneys generals who wrote letters to the Commission, say the SEC doesn’t have the legal authority to require climate-related disclosures at all. If there’s one thing that critics and supporters agree on, it’s that the rule, whatever it says, is going to be challenged in court.
What about the rules in Europe and California?
A lot of companies are going to have to report their scope 3 emissions anyway. The European Union’s Corporate Sustainability Reporting Directive includes scope 3 and is expected to cover more than 50,000 companies, with some starting to report as soon as this year; U.S.-based businesses on EU-regulated exchanges, or with subsidiaries or parent companies in Europe, will be expected to comply. A similar rule voted into law in California last year also requires scope 3 emissions disclosures and covers any company doing business in the state — whether private or public — giving it broader reach than the SEC. However, Governor Gavin Newsom did not include any funding for the law in his budget proposal this year, creating concern that it will be delayed.
Danny Cullenward, a climate economist and legal expert, said the fate of the California regulations are important in light of the likely Supreme Court challenge to the SEC rule. “It's a lot harder to mount comparably broad challenges to state laws on this front,” he told me.
How will this change the climate economy?
Despite the SEC’s narrow focus on protecting investors, the mandatory disclosure of corporate emissions and climate risks would have widespread effects — even some that regular people might feel. Suddenly, consumers would have better tools to compare the relative sustainability of different companies and products. Activists would have more documentation to hold companies accountable for greenwashing or failing to live up to their public climate commitments.
The rule is also set to spark an explosion in the businesses of corporate emissions accounting and climate risk analysis. Most companies don’t have the staff or expertise to track their emissions, and thus will have to turn either to specialized climate-specific firms like Watershed or all-purpose corporate accountants like Deloitte to manage the disclosure process for them. Similarly, analytics giants like Moodys and S&P Global will also be called upon to feed company data into climate models and spit out risk reports.
Both exercises come with inherent challenges and uncertainties. Climate risk researchers have warned that rating services keep their methodologies in a black box, making it hard to know whether they are using climate models appropriately. “The misuse of climate models risks a range of issues, including maladaptation and heightened vulnerability of business to climate change, an overconfidence in assessments of risk, material misstatement of risk in financial reports, and the creation of greenwash,” wrote the authors of a 2021 article in the journal Nature Climate Change.
“When you ask, ‘What is my exposure to future climate risks?,’ you're asking for a projection of future climate states and probabilities of different future climate outcomes and extreme weather events. There's an enormous amount of scientific uncertainty and complexity in getting to that,” Cullenward told me.
But while neither emissions accounting nor climate risk assessment may be perfectly up to the task yet, Cullenward argued that’s all the more reason for the SEC to get these rules in place.
“If you don't ask people to disclose what's going on, it's just sticking your head in the sand,” he said. “No one will ever know how to do it perfectly, getting out of the gate. To me that is not a reason to stop or to slow down, that is a reason to get started.”


 Збогом! Pedja Milosavljevic / AFP via Getty Images