Sign In or Create an Account.

By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy

Technology

Death of a Climate Bank

More than 60 percent of community solar financing nationwide involved Silicon Valley Bank.

•
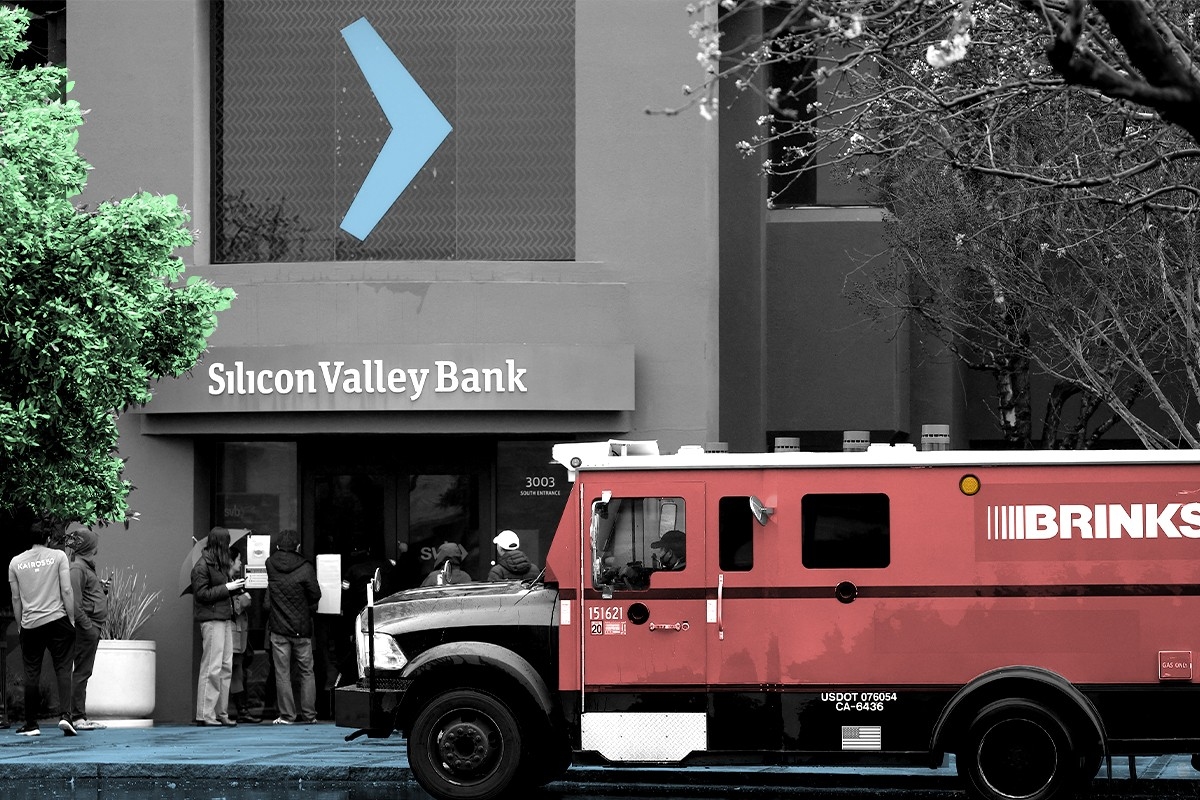
Silicon Valley Bank.
Heatmap Illustration/Getty Images

The United States witnessed its largest bank failure since 2008 on Friday, as Silicon Valley Bank ran out of cash and was taken over by the Federal Deposit Insurance Corporation.

True to its name, the bank was central to the technology ecosystem and Northern California economy; it claimed half of the country’s venture-backed startups as customers.

But what hasn’t received as much attention is that Silicon Valley Bank was particularly important to the climate-tech sector.

“Silicon Valley Bank was an integral part of the early-stage climate tech community and I hope that they survive in some form to continue that role,” Gabriel Kra, a managing director at Prelude Ventures, told me on Friday.

Silicon Valley Bank served as a banker to dozens of climate and energy-tech companies, holding their cash on a day-to-day basis and issuing billions of dollars in loans in support of the type of large-scale, one-off projects that are essential to the sector.

The bank’s website bragged about its particular support of solar, hydrogen, and energy-storage companies. It provided more than half a billion dollars in revolving credit to Sunrun, the country’s largest residential solar company. (Sunrun did not respond to a request for comment by press time.)

And more than 60 percent of community solar financing nationwide involved SVB in some capacity, the bank claimed on its website.

The bank also published influential annual reports on the climate-tech sector, and it sponsored events for climate VCs and startups — including one at the Lake Tahoe Ritz Carlton as recently as last week.

“They were careful, thoughtful, and willing lenders to early-stage companies,” Kra said. “As a bank, they were focused on that segment of the ecosystem and they understood the risks they were taking more than a bank that wasn’t focused.”

As news of the bank’s downfall spread, at least one venture firm extended emergency support so that companies could still pay their employees.

“The downfall of SVB will launch a thousand tweet threads, but right now our focus is securing payrolls for the Lowercarbon portfolio companies whose cash is tied up so they can keep up their planet-healing work,” Clay Dumas, a founding partner at Lowercarbon Capital, a climate-focused venture fund, told me in an email.

SVB’s collapse “has consumed the time of every founder I know for the last 36 hours,” Tim Latimer, the CEO of Fervo Energy, a geothermal company based in Texas and California, said on Twitter in a response to this story.

The bank’s recent problems weren’t connected to its climate-tech or startup lending, although they did stem from its broad lack of diversification away from the startup sector and Bay Area economy. In 2020 and 2021, the bank’s clients had more cash than they knew what to do with, and the bank chose to buy bonds and other securities to earn a higher yield on deposits. But over the past few months, as startups and the tech sector writ large faced a choppier economy, many of its depositors withdrew their money — and the bank had to sell its assets, which had lost value.

Because of its large number of corporate clients, most of its clients kept balances at the bank in excess of the $250,000 in deposit insurance provided by the federal government. That means many startups are now stuck in a potentially months-long line to get their money back — if they get it at all.

“Startups need cash — they’re not run in the same way that Fortune 500 companies are run,” Kra said. “Losing access to their cash balance for potentially several months can have catastrophic effects. And a small portion of companies in the space are probably looking at that possibility and figuring out how to avoid it.”

This article was updated at 11:35 PM EST on Friday to incorporate new details and quotes.


To receive Robinson Meyer's articles directly in your inbox, sign up for Heatmap Daily:
Blue

You’re out of free articles.

Subscribe to access Heatmap's exclusive climate and energy polling, award-winning journalism, and subscriber-only events. Save $57 on an annual subscription, just $156 $99/year.
To continue reading
Create a free account or sign in to unlock more free articles.
or
Please enter an email address
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
AM Briefing

Carbon Complaint

On Guterres naming a villain, how Masayoshi Son ‘overdid it,’ and Vance’s Venezuela trader

An Exxon sign.
Heatmap Illustration/Getty Images

Current conditions: A major Atlantic storm called Storm Charles is bearing down on Portugal, which closed schools, canceled all non-essential services, and called off the second day of the WebSummit in Lisbon • A potential nor’easter is threatening New York City with heavy rain and flooding • Jackson, Mississippi — where Democrat Scott Colom declared victory last night to become the state’s first Black senator in nearly 150 years — is set to reach a warm, sunny, 71 degrees Fahrenheit today before dropping off by nearly 20 degrees overnight.


THE TOP FIVE

1. UN chief’s closing climate message: Fossil fuels are ‘killing our planet’

When the Intergovernmental Panel on Climate Change released its landmark report on the closing window to keep global warming within the range set by the Paris Agreement in 2018, António Guterres was just a year into the job as the United Nations’ secretary-general. The left-wing former Portuguese prime minister quickly developed a knack for delivering speeches that contained exactly the kind of rousing soundbites that blared in headlines across the world. That year, he proclaimed climate change “the defining issue of our time – and we are at a defining moment.” As emissions continued to grow, he ratcheted up his language. In 2022, he warned of a world in “great peril.” In 2023, he lamented that “humanity has opened the gates of Hell.” In his likely final speech before the annual global climate summit as the UN chief, Guterres raged against a world still on “the path to mutually assured destruction.”As “heat records keep shattering,” he said, “fossil fuel interests keep making a killing — while killing our planet.”

Keep reading...Show less
Blue
Daily Briefing

It’s the Artificial Intelligence Muddle Now

SoftBank’s error and Nvidia’s scandal suggest data centers may have already peaked as an economic and energy trend.

A data center under construction.
Heatmap Illustration/Getty Images

This is Heatmap Daily, a weekday digest written by our executive editor. Subscribe here.

Covering energy and climate change sometimes means seeing certain stories in a different light than others. And a particularly vivid hue illuminated The Wall Street Journal’s report today that the Japanese conglomerate SoftBank Group is taking a $3.7 billion loss on several gigawatts’ worth of natural gas turbines.

Keep reading...Show less
Blue
Climate Tech

Running a Smart Home Energy System Takes a Lot of Software

Lunar Energy’s latest AI-powered system aims to integrate EVs into the automated demand response mix.

A home charging system.
Heatmap Illustration/Lunar, Getty Images

In theory, it’s straightforward to assemble the smart energy home: Solar panels, home backup batteries, and electric vehicles, plus smart thermostats, heat pumps, and water heaters — all the individual pieces can be had for the homeowner who can afford the up-front cost. The challenge is getting all those pieces to talk to one another.

Bay Area-based Lunar Energy is one of the tech firms that’s been trying to crack this problem. Today, it announced an upgraded version of its artificial intelligence-powered home energy control system, which not only integrates all those separate systems but also responds tactically to energy markets. CEO Kunal Girotra told me Lunar AI saves its users money by monitoring their home 24/7 and making decisions to charge, not to charge, or discharge so that they save the most money.

Keep reading...Show less
Yellow