You’re out of free articles.
This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
Microsoft dominated this year.

It’s been a quiet year for carbon dioxide removal, the nascent industry trying to lower the concentration of carbon already trapped in the atmosphere.
After a stretch as the hottest thing in climate tech, the CDR hype cycle has died down. 2025 saw fewer investments and fewer big projects or new companies announced.
This story isn’t immediately apparent if you look at the sales data for carbon removal credits, which paints 2025 as a year of breakout growth. CDR companies sold nearly 30 million tons of carbon removal, according to the leading industry database, CDR.fyi — more than three times the amount sold in 2024. But that topline number hides a more troubling reality — about 90% of those credits were bought by a single company: Microsoft.
If you exclude Microsoft, the total volume of carbon removal purchased this year actually declined by about 100,000 tons. This buyer concentration is the continuation of a trend CDR.fyi observed in its 2024 Year In Review report, although non-Microsoft sales had grown a bit that year compared to 2023.
Trump’s crusade against climate action has likely played a role in the market stasis of this year. Under the Biden administration, federal investment in carbon removal research, development, and deployment grew to new heights. Biden’s Securities and Exchange Commission was also getting ready to require large companies to disclose their greenhouse gas emissions and climate targets, a move that many expected to increase demand for carbon credits. But Trump’s SEC scrapped the rule, and his agency heads have canceled most of the planned investments. (At the time of publication, the two direct air capture projects that Biden’s Department of Energy selected to receive up to $1.2 billion have not yet had their contracts officially terminated, despite both showing up on a leaked list of DOE grant cancellations in October.)
Trump’s overall posture on climate change reduced pressure on companies to act, which probably contributed to there being fewer new buyers entering the carbon removal market, Robert Hoglund, a carbon removal advisor who co-founded CDR.fyi, told me. “I heard several companies say that, yeah, we wouldn't have been able to do this commitment this year. We're glad that we made it several years ago,” he told me.
Kyle Harrison, a carbon markets analyst at BloombergNEF, told me he didn’t view Microsoft’s dominance in the market as a bad sign. In the early days of corporate wind and solar energy contracts, he said, Microsoft, Google, and Amazon were the only ones signing deals, which raised similar questions about the sustainability of the market. “But what it did is it created a blueprint for how you sign these deals and make these nascent technologies more financeable, and then it brings down the cost, and then all of a sudden, you start to get a second generation of companies that start to sign these deals.”
Harrison expects the market to see slower growth in the coming years until either carbon removal companies are able to bring down costs or a more reliable regulatory signal puts pressure on buyers.
Governments in Europe and the United Kingdom introduced a few weak-ish signals this year. The European Union continued to advance a government certification program for carbon removal and expects to finalize methodologies for several CDR methods in 2026. That government stamp of approval may give potential buyers more confidence in the market.
The EU also announced plans to set up a carbon removal “buyers’ club” next year to spur more demand for CDR by pooling and coordinating procurement, although the proposal is light on detail. There were similar developments in the United Kingdom, which announced a new “contract for differences” policy through which the government would finance early-stage direct air capture and bioenergy with carbon capture projects.
A stronger signal, though, could eventually come from places with mandatory emissions cap and trade policies, such as California, Japan, China, the European Union, or the United Kingdom. California already allows companies to use carbon removal credits for compliance with its cap and invest program. The U.K. plans to begin integrating CDR into its scheme in 2029, and the EU and Japan are considering when and how to do the same.
Giana Amador, the executive director of the U.S.-based Carbon Removal Alliance, told me these demand pulls were extremely important. “It tells investors, if you invest in this today, in 10 years, companies will be able to access those markets,” she said.
At the same time, carbon removal companies are not going to be competitive in any of these markets until carbon trades at a substantially higher price, or until companies can make carbon removal less expensive. “We need to both figure out how we can drive down the cost of carbon removal and how to make these carbon removal solutions more effective, and really kind of hone the technology. Those are what is going to unlock demand in the future,” she said.
There’s certainly some progress being made on that front. This year saw more real-world deployments and field tests. Whereas a few years ago, the state of knowledge about various carbon removal methods was based on academic studies of modeling exercises or lab experiments, now there’s starting to be a lot more real-world data. “For me, that is the most important thing that we have seen — continued learning,” Hoglund said.
There’s also been a lot more international interest in the sector. “It feels like there’s this global competition building about what country will be the leader in the industry,” Ben Rubin, the executive director of the Carbon Business Council, told me.
There’s another somewhat deceptive trend in the year’s carbon removal data: The market also appeared to be highly concentrated within one carbon removal method — 75% of Microsoft’s purchases, and 70% of the total sales tracked by CDR.fyi, were credits for bioenergy with carbon capture, where biomass is burned for energy and the resulting emissions are captured and stored. Despite making up the largest volume of credits, however, these were actually just a rare few deals. “It’s the least common method,” Hoglund said.
Companies reported delivering about 450,000 tons of carbon removal this year, according to CDR.fyi’s data, bringing the cumulative total to over 1 million tons to date. Some 80% of the total came from biochar projects, but the remaining deliveries run the gamut of carbon removal methods, including ocean-based techniques and enhanced rock weathering.
Amador predicted that in the near-term, we may see increased buying from the tech sector, as the growth of artificial intelligence and power-hungry data centers sets those companies’ further back on their climate commitments. She’s also optimistic about a growing trend of exploring “industrial integrations” — basically incorporating carbon removal into existing industrial processes such as municipal waste management, agricultural operations, wastewater treatment, mining, and pulp and paper factories. “I think that's something that we'll see a spotlight on next year,” she said.
Another place that may help unlock demand is the Science Based Targets initiative, a nonprofit that develops voluntary standards for corporate climate action. The group has been in the process of revising its Net-Zero Standard, which will give companies more direction about what role carbon removal should play in their sustainability strategies.
The question is whether any of these policy developments will come soon enough or be significant enough to sustain this capital-intensive, immature industry long enough for it to prove its utility. Investment in the industry has been predicated on the idea that demand for carbon removal will grow, Hoglund told me. If growth continues at the pace we saw this year, it’s going to get a lot harder for startups to raise their series B or C.
“When you can't raise that, and you haven't sold enough to keep yourself afloat, then you go out of business,” he said. “I would expect quite a few companies to go out of business in 2026.”
Hoglund was quick to qualify his dire prediction, however, adding that these were normal growing pains for any industry and shouldn’t be viewed as a sign of failure. “It could be interpreted that way, and the vibe may shift, especially if you see a lot of the prolific companies come down,” he said. “But it’s natural. I think that’s something we should be prepared for and not panic about.”

This Halloween, get 20% off using code ADVANCED
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
When it comes to energy and data centers, everyone loves Texas. Its pro-business political consensus, unusually deregulated electricity market, wide-open plains, sunny skies, and large natural gas and oil deposits have attracted data center developers, renewables developers, liquefied natural gas export terminals, and battery storage entrepreneurs alike.
But this all happened under decades of unified Republican control of Texas’ government. That’s ending on January 19, when Gina Hinojosa is sworn in as governor alongside every other holder of statewide elected office who won this year. In Austin, they will join a Democratic majority Texas House of Representatives, which has been under Republican control since 2003.
Immediately following the election, stocks linked to data center development in Texas swooned — Elon Musk’s SpaceX is down 12.5% since Tuesday, data center developer CoreWeave is down almost 19%, Oracle is down 9%, Texas-based independent power producer Vistra is down 19%. Sterling Infrastructure, a civil construction company headquartered outside Houston, has seen its shares fall 32%.
On the campaign trail, Hinojosa called for a moratorium on data centers until the legislature could pass legislation putting guardrails around development, including protecting residential ratepayers from electricity price hikes and giving local communities more leeway to restrict and condition development. Two weeks before election day, she released a video criticizing Governor Greg Abbott’s “Batch Zero” review process — which had been broadly characterized as a “pause” when it was announced over the summer — for allowing new permits, and she said that she would issue a “ban” on all data center approvals until new laws could be passed.
When Abbott introduced his pause over the summer, Texas’s electricity market ERCOT had 474 gigawatts of data center interconnection requests in its queue (almost all from data centers), a figure he said was around five times the electricity market’s peak demand. That review is due to end next month, shortly before Hinojosa is due to take office, leaving little time for new projects to get approved before the moratorium goes into effect.
Some observers and investors took a sanguine view of Hinojosa’s data center policies. Gavin Baker, a longtime investor in SpaceX, said on X that Hinojosa’s policies “sound reasonable” and pointed to an interview she gave saying that the moratorium would be on new permits and would not affect the pipeline of permitted projects.
The data center and energy industry, however, is in wait-and-see mode when it comes to the severity of the moratorium.
“If she was thinking of trying to go after projects that had begun the construction process,” Brandt Vermillion, U.S. research lead at Modo Energy, said, “I think it would change the overall outlook a ton.”
According to Modo Energy analysis, there are some 25 gigawatts worth of projects under construction in Texas, another 4.6 gigawatts permitted, and another 90 gigawatts that are either just announced or have only submitted grid studies. If Hinojosa “is only going after non-permitted projects,” Vermillion added, then anyone thinking about the future path of data center development in Texas should be more concerned about supply chain constraints like obtaining enough chips to power the data centers.
That being said, the Texas legislature’s session doesn’t end until May 2027, meaning that Hinojosa’s pause could last several months before lawmakers put guardrails into law.
“I don’t think we’re going to not build another data center in the state,” Joshua Rhodes, a research scientist at the University of Texas at Austin, told me. “But I think that they’re going to be under quite a bit more scrutiny.”
That being said, analysts are now much more uncertain about the future path of electricity demand in the state. “Texas demand is difficult to project after Gina Hinojosa’s surprise win,” Jefferies analyst Julien Dumoulin-Smith wrote in a note to clients on Thursday.
That means more trouble for developers in Texas, especially for storage projects, which had already been seeing extremely volatile monthly revenue.
“Batteries and energy storage have been counting on demand to go up because they’re having a rough time out there right now in terms of revenues,” Rhodes said. “Demand will have a pretty big impact on supply.”
One thing the battery storage industry, as well as solar and wind developers, can cheer is that Democratic control of the governorship and the state House means that the threat of anti-renewables bills has fallen to essentially zero.
The renewables industry is hoping that data center development does continue in Texas, but that it looks more orderly and grid-connected.
Going forward, Vermillion expects that data center developers will have a harder time getting tax abatements, which means that a “well-capitalized hyperscaler” could potentially still pursue projects.
“Project A that was going to go about development in a certain way of seeking tax abatements and buying a bunch of reciprocating engines and trying to run themselves off grid” is much less likely to be able to go forward in Hinojosa’s Texas, Vermillion told me, especially as she is able to appoint new commissioners to the Texas Public Utility Commission or the Texas Commission on Environmental Quality.
Tim Woodruff, the data center lead at Modo, told me similarly. “In the near term, if you're one of the neo clouds, maybe now you start pushing a little harder on your projects that you have in MISO or in CAISO,” he said.
Invest in Tomorrow Coalition says it took out clean energy adversaries in the midterms. Now it’s setting its sights on 2028.
A pro-renewables Super PAC – Invest in Tomorrow Coalition – is taking a victory lap, claiming it played a key role in the blue wave and announcing plans to be involved in the 2028 presidential primaries.
When I first heard of the Invest in Tomorrow Coalition, it was clearly a revenge operation. Backed by renewables companies and crypto magnate Chris Larsen, the Super PAC waded into primary elections this year to take out Republicans who voted to repeal most of the Inflation Reduction Act. Tom Matzzie, a renewables executive leading the Super PAC, described the organization to me as “focused on accountability for elected officials who decide they want to attack the clean energy industry.” Shortly afterwards, Invest in Tomorrow announced an investment in seven races before ultimately expanding to 18 races.
Now that the dust is settled, Matzzie told me that most of the races they intervened in wound up flipping red to blue: “I think we’re on track to win 12 or 13 of the 18 we invested in. We had seven or eight marquee races and we’re winning the majority of those. We were hopeful we’d get one in a tough district. We didn’t expect to get this many.”
Their favorite trophy is Indiana’s 5th congressional district in the northern Indianapolis region, where Rep. Victoria Spartz lost a historically comfortable GOP seat to J.D. Ford, a Democratic state senator. Matzzie told me the Super PAC invested $2 million in the race to beat Spartz, which he claimed is more than both campaigns spent combined. (My search of FEC records shows that may be true, if you don’t count other outside assistance.)
After Spartz was declared the loser, the Super PAC sent an email blast to the media with a short statement: “Tell Victoria Spartz. We want her to know it was us.”
The Super PAC also claims at least partial responsibility for helping oust Rep. Lauren Boebert of Colorado, who lost by just a few thousand votes. I’m told they invested $1.5 million in the race, including on a digital ad centered around an incident where Boebert was escorted out of a live stage performance of “Beetlejuice.” The ad claimed Boebert couldn’t be trusted around children. It prompted Boebert to do a whole segment bashing the Super PAC while guest hosting former Rep. Matt Gaetz’s One America News show.
“Oh, I love it when they complain about us. I love it when they whine about us. We want them to spread the word to other members of Congress about what we’re doing,” Matzzie told me. “We want to send a message that we will do what is necessary to defeat you in your next election, including getting down in the mud if needed, and we have limits on what we say and won’t say, but it has to be truthful.”
Since it is already time for 2028 discussions, I asked Matzzie if the Super PAC had any ambitions to be involved in the presidential primaries next. Absolutely, he said. First that involvement will look like education. That could look like having pro-renewables voices urging GOP candidates to be more receptive to the sector, whether they be representatives of the business community or landowners with solar on their properties.
“The accountability part of this comes later as people firm up their point of view on what they’re running on and we don’t know what that is yet. We totally invite all of the candidates to be supportive of the clean energy industry if they’re running for president. That is our ideal outcome,” Matzzie said.
But if candidates don’t get the message will they go on the attack against primary candidates? “I have no hesitation about doing it.”
On electrification’s shortfall, AI for nuclear, and Alva Energy’s big plans
Current conditions: Heavy rain is overflowing rivers in the Dominican Republic’s eastern inland towns, including Monte Plata, where floodwaters are washing away cars • With weeks to go before the Atlantic hurricane season officially ends, a new tropical storm may be forming between the Bahamas and Bermuda • It’s cloudy and 51 degrees Fahrenheit in London, where the British are marking Guy Fawkes Day, a holiday commemorating the 421st anniversary of the failed plot by English Catholics to assassinate King James VI of Scotland and I of England by blowing up the House of Parliament.
It’s a rebuke of President Donald Trump! A new era! A sign that President Lyndon B. Johnson’s prediction that the Democrats would lose the South until the end of young Bill Moyers’ lifetime (he died last year) was true! Maybe it’s all of these things. But one thing is certain: Democrats’ big victory Tuesday night halts what my colleague Robinson Meyer called “Trump’s energy revolution,” meant to defy the economics of renewables. There’s still much to dissect — we don’t even know who won shockingly competitive U.S. Senate races in Mississippi and Alaska. But my colleagues have a nice slate of stories to help us get started:
Vice President JD Vance is openly blaming the Trump administration’s war with Iran for Republicans’ midterm shellacking, and Democrats are formulating a new approach after campaigning against the conflict and its associated energy shock. Iran, meanwhile, is signaling its openness to peace talks, even as Tehran turns to guerrilla tactics to regain control over the Strait of Hormuz. All that looks to oil traders like more crude hitting the market. On Wednesday, the price of West Texas Intermediate crude, the U.S. benchmark, fell more than 8% to $88 per barrel. Brent crude, the global price measure, plunged nearly 9% to just under $95 per barrel. Murban crude, the stuff that leaves a Persian Gulf port in the United Arab Emirates, dropped 1% to just under $101 per barrel.

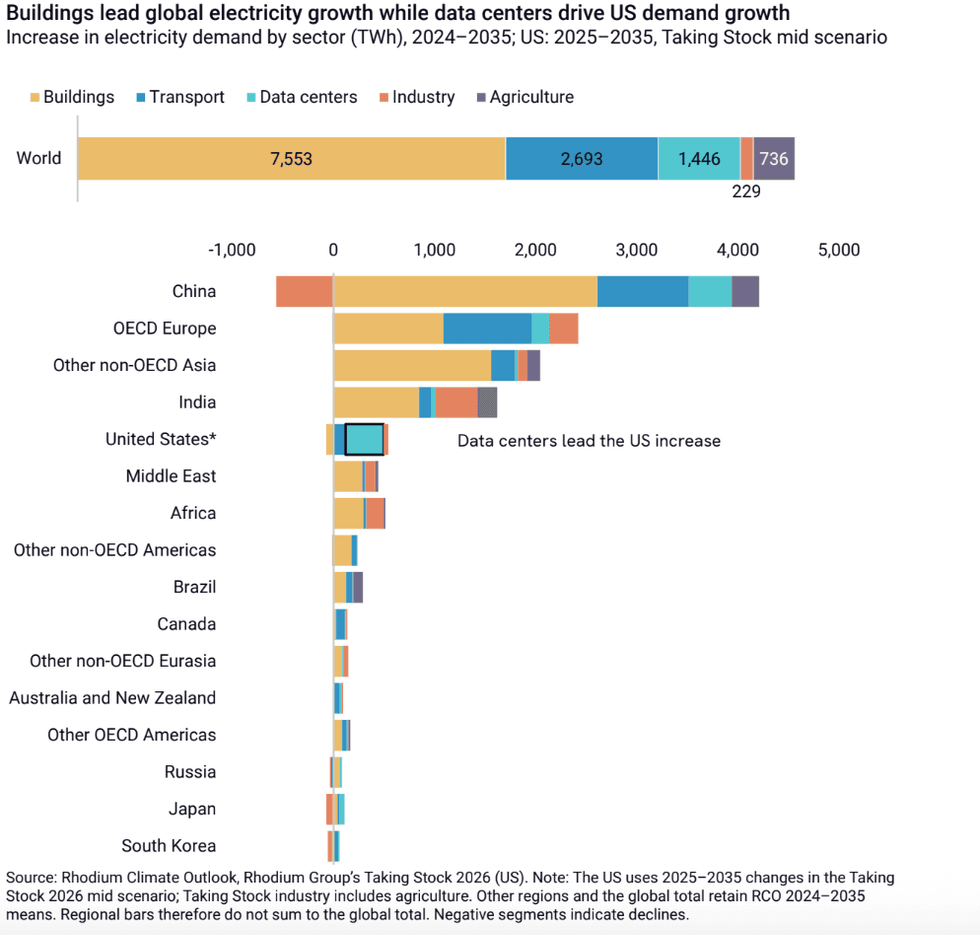
Big meals, big trucks, big computers — it’s the American way. Only one of those is a problem for electricity prices — a problem that’s also uniquely American. New projections from the Rhodium Group suggest that the U.S. is the only major market where data centers are the primary driver behind surging electricity demand, constituting between 62% and 77% of gross demand growth. In China, Europe, India, and the Middle East, residential and commercial buildings are by far the biggest new sources of demand for electricity to power air conditioning, heating, and appliances. Meanwhile, according to data from the consultancy Cleanview, upward of 41% of planned data centers in the U.S. are in states where newly elected governors are considering moratoria on new projects
.

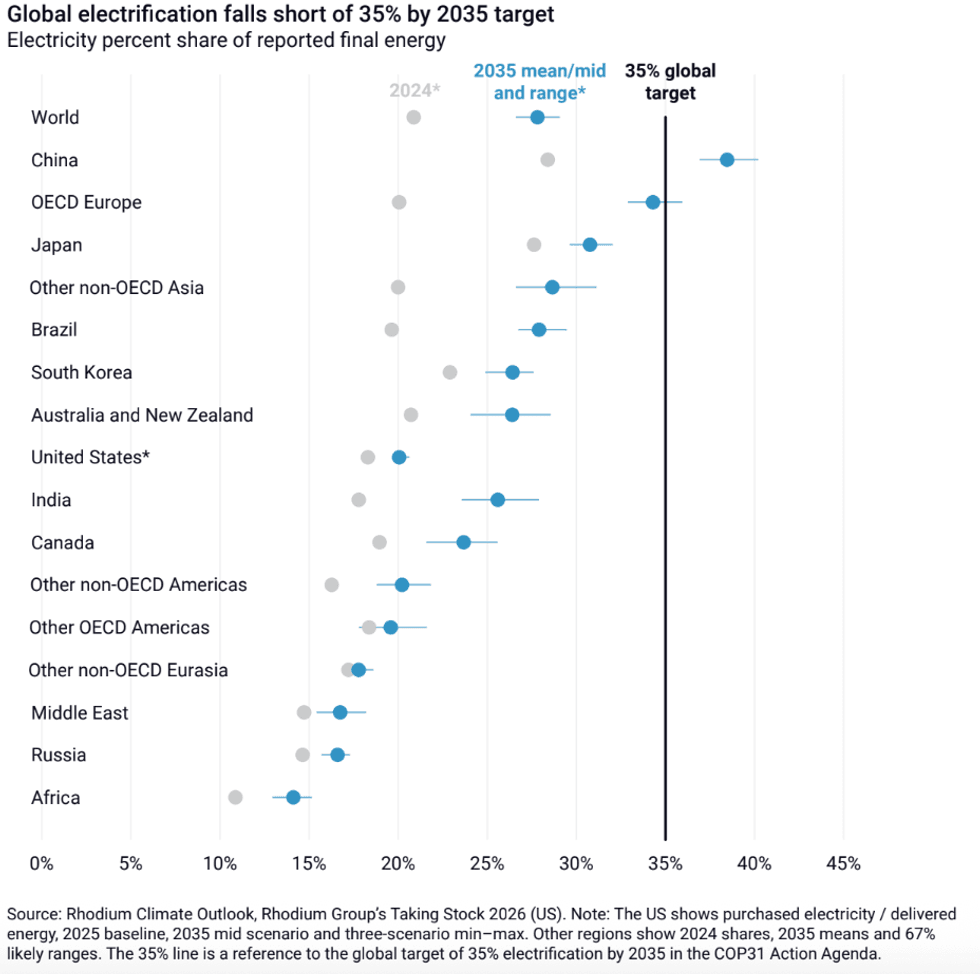
The Rhodium forecast also shows big global challenges for the fight to slow global warming. Electricity serves just 21% of the world’s end-use energy; by 2035, countries pledged to raise that figure to 35%. But the global average for electrification is on track to hit just 28% in the next nine years, threatening to maintain planet-heating pollution levels even as renewables surge and power emissions fall. Low-carbon sources of electricity are on track to generate upward of 80% of the power in China and the world’s richest economies, with variable renewables such as wind and solar producing the bulk of the output. Clean firm sources such as nuclear power and geothermal maintain a steady share of total output as variable sources eat into fossil fuels’ market. As a result, emissions shift to the parts of the world where fossil fuels will remain dominant. China and rich countries will account for 37% of emissions in 2050, down from 54% in 2024. India’s emissions will rise 26% by the middle of the century, and the entire African continent’s output by 37%. Worldwide industrial emissions are on track to stay static as the benefits of low-carbon steel are offset by the spike in production from coal-fired blast furnaces.
Sign up to receive Heatmap AM in your inbox every morning:
Whenever OpenAI or Anthropic releases a new model, the healthcare industry, say, can measure its capabilities by seeing how quickly it can pass a medical board test. Last year, the AI startup Atomic Canyon — which formed to help nuclear plant operators sift through mountains of documents using large language models — inked a deal with the Idaho National Laboratory to create a test that can check the software’s ability to work with a nuclear plant. Fourteen months later, the partnership has yielded results. On Thursday, I can report exclusively for this newsletter, Atomic Canyon is set to launch what it calls NuclearBench, the first open-source benchmark designed specifically to evaluate how LLMs perform on questions related to nuclear energy. “Think about it like an open-book exam for AI models,” Trey Lauderdale, Atomic Canyon’s founder and chief executive, told me. The company worked with INL to design a 280-question exam, which can then be administered to AI models, whose answers are judged by accuracy and context.
“As you’d expect, the more advanced models perform better. You’ve got OpenAI, Google, and Anthropic all vying at the top,” Lauderdale said. “Nothing we wouldn’t expect, but it’s nice to have actual metrics and information that validate general hypotheses you might have. You could instinctively say, This model is doing better. But it’s really important as an industry that you start benchmarking what these models can do.” Atomic Canyon’s test is not yet at the level of a medical board exam, he said. But the company plans to continuously update its exam to account for the growing sophistication of LLMs. Eventually, Lauderdale hopes to roll out more targeted tests focusing on safety and risk, reactor engineering, emergency preparedness, radiation, and other factors. “It’s the equivalent of the tests to become a general physician or those to become a cardiologist, dermatologist, or gastroenterologist,” he said.
Last month, I told you when tech giants announced a series of deals to help fund “uprates” at existing nuclear plants, renovations that potentially squeeze hundreds of megawatts of new generation out of reactors that are already running. The deals with Google and Amazon looked to generate more than a gigawatt of new power through uprates across PJM Interconnection, the most stressed grid system in the U.S. Now a startup specifically designed to affordably uprate reactors is considering projects to generate as much as 1.2 gigawatts of new power out of existing plants — and it just received a major endorsement from a utility industry heavyweight. I can exclusively report that, on Thursday, the developer Alva Energy plans to announce that Jeff Lyash, the former chief executive of the Tennessee Valley Authority and Ontario Power Generation, would join its board of directors. Lyash has plenty of nuclear experience. OPG, owned by Canada’s most populous province, operates the second-largest nuclear fleet in North America after the U.S.-based Constellation Energy. It’s also building the continent’s first small modular reactor, the first of GE Vernova Hitachi Nuclear Energy’s 300-megawatt units. The federally owned TVA, from which Lyash retired last year following Trump’s return to the White House, operates three nuclear plants and is building what’s expected to be America’s first SMR, the second GE-Hitachi BWRX-300 after OPG’s project at its Darlington plant. Lyash will be the fifth member of Alva’s board. After former Intel CEO Pat Gelsinger, he’s the second to come from outside the company; the other three board members are Alva’s co-founders.
“What’s been pretty amazing is that we’re starting to attract top-tier industry talent,” James Krellenstein, Alva’s chief executive and co-founder, told me. “Jeff joining the board has been pretty transformational because he brings a massive amount of experience in modifying existing plants.” At OPG in particular, Krellenstein said, Lyash oversaw refurbishments of the utility’s CANDU reactors. He also sits on the boards of the utility Dominion Energy, the Canadian construction giant Aecon, the industrial conglomerate Curtiss-Wright, and the European reactor startup Newcleo, which Krellenstein said lends Alva greater insight into other sectors’ large-scale project management. “What the economy of the United States is looking for is sources of clean, 24/7 power. Nuclear power uprates are a way in the short term to get that demand fulfilled in the United States while simultaneously rebuilding the execution capability necessary to create new plants. That’s the exact scaling strategy that Alva is working on.”
It’s no Norway, where electric vehicles make up nearly 99% of new car sales. But EVs’ share of Germany’s new car market soared to a record 37% last month, according to data from the country’s national motor vehicle authority, the Kraftfahrt-Bundesamt. That, according to Electrek, equates to 94,086 new battery-electric vehicles, up nearly 80% from the 53,425 sold a year earlier.