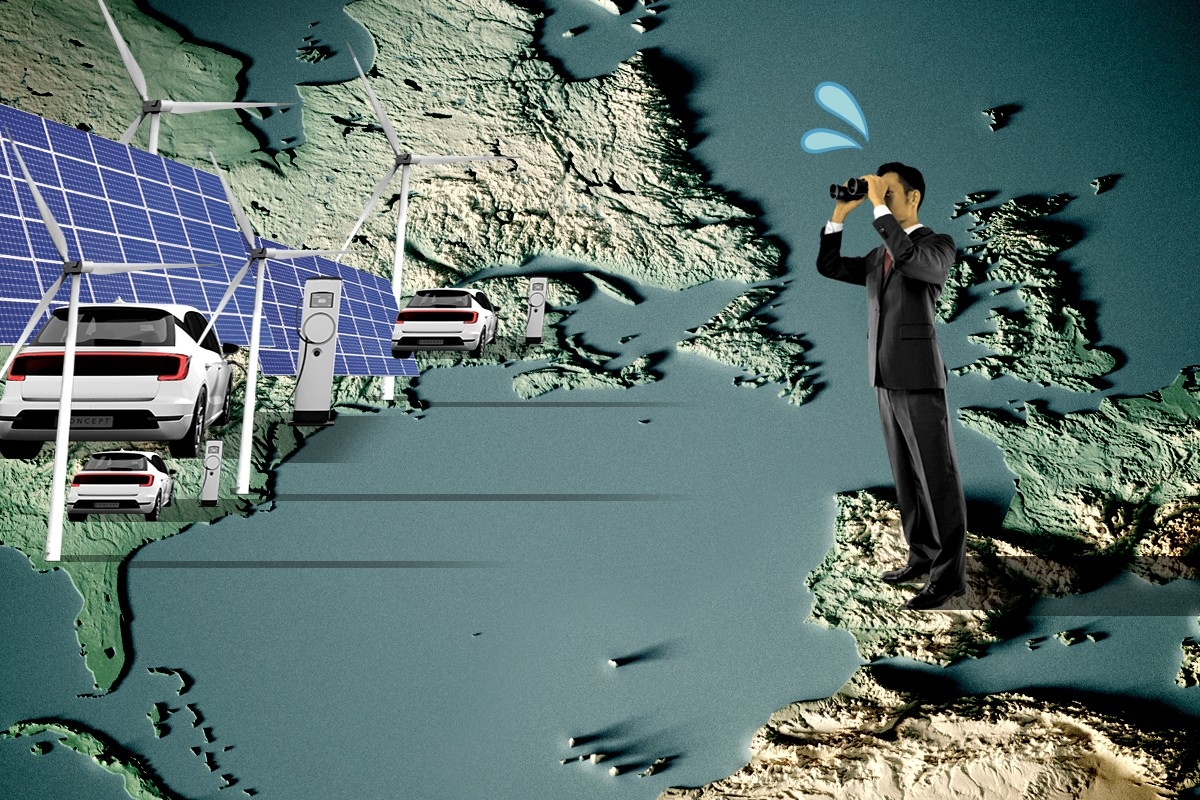
European elites have been annoyed or worse by the U.S. Inflation Reduction Act. Its name is misleading; this is the largest American industrial policy since the New Deal — one that intends not only to drastically reduce greenhouse gas emissions, but also to stand up a whole new industrial supply chain for green energy and manufacturing located in the U.S. and North America.
That project doesn’t sound great to many Europeans. French President Emmanuel Macron complained it was “super aggressive.” The French and German economic ministers traveled to Washington in February to lobby the Biden administration for exemptions from IRA rules (and actually got a receptive hearing). More recently Europe seems to have softened on the law; Bloomberg reports that elites are making their piece with EU businesses setting up shop in North America to be eligible for IRA subsidies. But this is still not ideal.
In the abstract, one can sympathize with European complaints over the U.S. flexing its still-unparalleled economic might to direct a greater share of cutting-edge economic production towards itself. But this isn’t merely a question of economics. As the recent IPCC report details, the world is still careening towards catastrophic global warming even given the fairly extensive climate policies most countries have enacted. Fighting that crisis trumps any possible complaint about economic unfairness.
But there’s a deeper problem here. The European Union taken together has economic heft not far off from the United States, with a population of 450 million and a price parity GDP of about $24 trillion. It absolutely has the capacity to enact an IRA-style industrial policy scheme — indeed, the continent has been crying out for one for over a decade. The IRA is a perfect opportunity to clear away the irrational and deeply harmful budget rules that have hamstrung the EU economy, return prosperity to the continent, and fight climate change to boot.
For the last 15 years most of the European Union, and especially the eurozone currency area, has been suffering a largely self-inflicted crisis of economic stagnation.
When the 2008 financial crisis hit, Europe barely avoided a galloping economic collapse, but it still faced a serious recession, particularly in the eurozone periphery of Greece, Spain, Italy, and Portugal. These countries were confronted with classic debt problems as revenues fell while spending on social benefits rose — a situation made worse because those nations did not control the European Central Bank and thus couldn’t rely on it to print money to prevent a self-perpetuating debt crisis. The EU eventually responded by essentially bailing out the banks that had lent to the ailing countries, but they disguised it as broader economic relief and then demanded punishing austerity measures in the rescued countries.
The austerity binge after 2010 pummeled the broader EU economy, and created a Great Depression-scale catastrophe in Greece and Spain. In the eurozone, unemployment had peaked and started to come down by mid 2010, but once the debt crisis and austerity poison took hold, it soared again to over 12 percent by 2012, where it remained for two years, and came down only with agonizing slowness. In Spain unemployment peaked at 26 percent, in Greece 28 percent.
Since 2009, eurozone growth has been dismal compared to America — which itself suffered a growth disaster during the 2010s, as I have previously argued. Yet the U.S. still managed inflation-adjusted growth per person of 19 percent between 2009 and 2021; the eurozone figure is 11 percent. In France the figure is just 8 percent; in Spain 1 percent, and in Greece negative 17 percent. Italy has not grown at all for more than 20 years. Adding insult to injury, all that austerity didn’t even help with Greece’s debt-to-GDP burden, because its economy shrank just as fast as the debt total.
This was a disaster for climate change and European energy security. European investment in renewable energy plummeted during the 2010s, from a high of about $30 billion in 2011 to just $10 billion in 2018. In sunny Spain and Italy investment virtually ceased during this period. Instead many European countries, particularly Germany, came to rely on cheap Russian natural gas for their core energy needs. That made them greatly vulnerable to Russia pressure when Vladimir Putin cut down gas supplies in an attempt to force Europe to stop supporting Ukraine’s effort to fight off Russian aggression.
To be fair, as I previously wrote here at Heatmap, Europe has been conducting a crash renewable investment program in response to Putin’s war that has been an amazing success, all things considered. But if it had spent the 2010s building out green energy, it would have been far less vulnerable to Russia coercion, its emissions would be much lower, European inflation today (driven by skyrocketing energy costs) would be considerably less, and Putin might even have thought twice about the invasion.
What is called for is a Europe-wide spending, borrowing, and investment policy to add to existing EU renewable subsidies. Rather than just decarbonization, the goal should be to restore full employment and production, and create a green energy and technology supply chain in Europe itself.
In other words, Europe needs its own Inflation Reduction Act. But still one hears austerity dogmatism from the highest European quarters. The EU is currently renegotiating its budget policies and German Finance Minister Christian Lindner recently published an article in the Financial Times arguing that “[s]ound public finances are a prerequisite for enabling economic growth in the EU,” and therefore the old strict rules about deficits and debt “must remain untouched.”
It would be hard to imagine a better disproof of this argument than the evidence cited above. The result of the old rules was the Greek crisis that threatened the structure of the EU itself. Europe’s lousy economic performance undoubtedly contributed to the decision of British voters to leave the EU in 2016. Yet Lindner has learned nothing.
The actual proposed reforms to the pact were released this week, and while they are a step in the right direction, they are mainly a loosening of the austerity straitjacket, not a removal of it — allowing countries more leeway as to how they will cut debt and deficits. That’s far short of what’s needed.
European commentators who aren’t austerity addicts often point to the political obstacles to doing Europe-wide industrial policy. But America has its own obstacles that are nearly as difficult to overcome. Thanks to our anachronistic Constitution, we had to get our climate bill past Joe Manchin, a literal coal baron. It’s frankly shocking that Democrats managed to pass anything with a zero-seat majority in the Senate, let alone the largest climate bill in history.
So for any Europeans who can see sense, the IRA should be seen as a golden opportunity. As noted above, the EU’s lunatic budget rules are most vulnerable in a crisis, and this can be such a crisis.
It may seem presumptuous for an American — coming from the land of suburban sprawl, four-ton SUVs that get eight miles to the gallon, and 3,000 square foot desert McMansions — to be lecturing Europe about what it needs to do about climate and economics. But I’m coming from a place of deep affection for the continent. I have been inspired by Europe’s welfare states, its city infrastructure, and even its tax authorities. America’s institutions in these areas are humiliating, pathetic failures by comparison.
That’s precisely why I want to see Europe strong, prosperous, and confident once more — so it can be the best version of itself, and provide an even better example for the rest of the world.