You’ve reached your free article limit
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Sign In or Create an Account.
By continuing, you agree to the Terms of Service and acknowledge our Privacy Policy
Welcome to Heatmap
Thank you for registering with Heatmap. Climate change is one of the greatest challenges of our lives, a force reshaping our economy, our politics, and our culture. We hope to be your trusted, friendly, and insightful guide to that transformation. Please enjoy your free articles. You can check your profile here .
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Subscribe to get unlimited Access
Hey, you are out of free articles but you are only a few clicks away from full access. Subscribe below and take advantage of our introductory offer.
subscribe to get Unlimited access
Offer for a Heatmap News Unlimited Access subscription; please note that your subscription will renew automatically unless you cancel prior to renewal. Cancellation takes effect at the end of your current billing period. We will let you know in advance of any price changes. Taxes may apply. Offer terms are subject to change.
Create Your Account
Please Enter Your Password
Forgot your password?
Please enter the email address you use for your account so we can send you a link to reset your password:
The same technology that powers your cell phone also helps expand the reach of renewable energy.

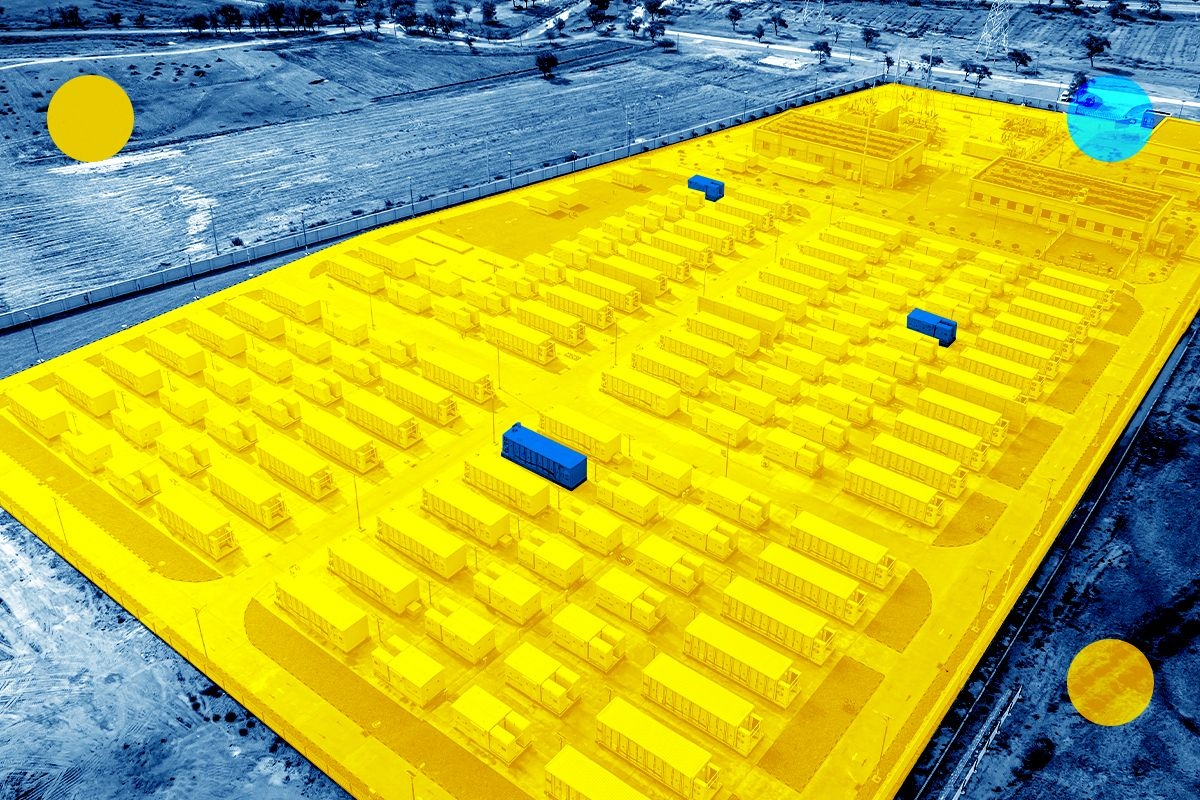
Batteries are the silent workhorses of our technological lives, powering our phones, computers, tablets, and remotes. But their impact goes far beyond our daily screentime — they’re also transforming the electricity grid itself. Grid-scale batteries store excess renewable energy and release it as needed, compensating for the fact that solar and wind resources aren’t always available on demand.
The price of the most ubiquitous battery technology — lithium-ion — has fallen remarkably in the past 15 years. That’s allowed for an enormous buildout of battery storage systems in the U.S. and beyond, which has in turn helped to integrate more renewables onto the grid than ever before. With the assistance of batteries, California ran entirely on clean energy for the equivalent of 51 days last year, while South Australia managed the same for 99 days.
Even as deployment accelerates, startups and other innovators are working to improve on standard lithium-ion tech — or in some cases, supplant it. We’ll get into all that soon, but first, let’s start with a little Battery 101.
All electrochemical batteries — that’s everything from your standard AA to grid-scale lithium-ion systems — work by turning chemical energy into electrical energy through what’s known as an electrochemical reaction. These batteries have three primary components:
Grid batteries charge when there’s excess renewable energy on the grid or when demand for energy is low. When a lithium-ion battery is charging, lithium ions move from the cathode to the anode, where they’re stored. When the battery discharges electricity back to the grid, lithium ions move from the anode to the cathode. This movement triggers the release of electrons at the anode, which move through an external wire that carries power to the grid.
There’s variation within the realm of lithium-ion batteries. For example, some use different cathode chemistries, a solid electrolyte, or a pure lithium metal anode. Within the broader world of electrochemical batteries, there are also a variety of alternate chemistries including sodium-ion, lithium-sulfur, and iron-air (more on those below).
But if one broadens the definition of a battery to include any system that stores energy, that’s when the possibilities really open up. In this sense, a battery could be a pumped hydropower storage system, in which energy is stored by moving water uphill into a reservoir and later releasing it to generate electricity through kinetic energy. A battery could also be energy stored as heat or compressed air. Many of these mechanisms rely on converting stored energy into electricity by turning a turbine or generator.
Batteries help to stabilize the electric grid and help communities and grid operators to take full advantage of their renewable energy resources by providing a reliable power supply when, as the saying goes, the sun isn’t shining and the wind isn’t blowing. New solar or wind plants combined with battery storage can also be highly cost-effective, achieving power prices that are competitive with or lower than those of new natural gas facilities in many cases.
Homes and businesses can also install their own personal battery storage systems to bank energy from rooftop solar panels or directly from the grid. This allows individuals and companies to lower their electricity bills by charging their batteries when grid prices are low and using stored energy when prices are high.
By the end of last year, the installed capacity of utility-scale batteries in the U.S. reached about 26 gigawatts, surpassing the cumulative capacity of pumped hydro for the first time. So while pumped hydro can still store a larger amount of total energy, batteries can now deliver more instantaneous power to the grid than any other energy storage resource. And though that 26 gigawatts represents a mere 2% of the U.S.’s total 1,230 gigawatts of generation capacity, the battery sector is growing rapidly. The International Energy Agency reported in February that planned capacity additions for this year totaled 18.2 gigawatts for the U.S. alone.
Lithium-ion batteries weren’t originally designed for grid-scale energy storage. Rather, they were commercialized in the early 1990s for use in portable consumer electronics such as camcorders, cell phones, and laptops. These batteries proved to be more energy dense, lighter, and longer lasting than their predecessors, and were thus eventually adopted for a whole host of applications, including the growing electric vehicle market in the 2010s.
As electric vehicle production ramped up throughout the decade, manufacturers scaled up their production of lithium-ion batteries, quickly driving down prices — from 2010 to 2020 the cost of battery packs declined nearly 90%. Production became primarily concentrated in East Asia, where companies such as CATL, LG Energy Solution, and Panasonic emerged as dominant players.
As the cheapest and most mature battery tech on the market, lithium-ion thus became the default for grid developers looking to manage the variability of intermittent solar and wind resources. As renewables deployment surged, adding battery storage to these facilities started to become more cost-effective than building new fossil-fuel facilities in some markets and provided a reliable way to regulate the grid’s frequency. Lithium-ion batteries can begin absorbing or delivering power at a moment’s notice, which is integral to keeping the grid balanced.
While lithium-ion batteries have never been a very practical or economical option when it comes to long-duration storage — that is, the ability to dispatch energy for more than about four to eight hours at a time — they are well suited to applications such as storing excess solar produced during the day for use in the evening, or smoothing out the fluctuations in renewable resources throughout the day.
For one, China essentially has a virtual monopoly on the lithium-ion battery industry. The country made EV production a national priority beginning in the 2000s, and by the 2010s it was heavily subsidizing battery and EV manufactures alike. Thus, China came to dominate the supply chain at nearly every level, from raw materials refining to cell manufacturing, anode and cathode production, and battery pack assembly. Ideally, the U.S. would lessen its technological reliance on a nation that it’s long seen as an adversary, but building a domestic lithium-ion battery industry from scratch is an extremely complex and expensive endeavor.
In terms of technical drawbacks, most lithium-ion batteries use a flammable liquid electrolyte. That’s prone to catching fire if a battery component or surrounding equipment fails, if a cell is punctured or simply overheats, as illustrated by the Moss Landing fire in California, which broke out in January at one the world’s largest battery storage facilities. While the energy density of lithium-ion is a main selling point, the flipside is that in a fire, more energy equals more heat. And since grid-scale systems pack battery cells close together, a fire in one cell can spread quickly across an entire facility.
Finally, in terms of cost, there’s only so far lithium-ion batteries can fall due to the expense of the raw materials. The price of lithium itself has been notoriously volatile. After hitting record highs in 2022, the commodity price subsequently collapsed after a wave of new mining projects oversupplied the market. This type of volatility wreaks havoc for battery storage developers and their balance sheets, thus spurring interest in chemistries that offer lower, more stable costs, as well as technologies with potentially superior cycle life, energy density, discharge times, and safety profiles.
The most widely commercialized spin on conventional lithium-ion batteries, which are traditionally made with an NMC cathode, is a variant known as lithium iron phosphate, or LFP. The iron-phosphate bond in a LFP cathode is very strong, making it more thermally stable than those in NMC batteries. LFP materials are also more structurally durable than nickel and cobalt, meaning these batteries can be charged and discharged more times before wearing out. Finally, LFPs are also cheaper and more sustainable, as the cathode materials are plentiful and less environmentally damaging to mine. LFP’s main drawback is its lower energy density, but its many advantages have enabled it to overtake NMC as the leading chemistry for new battery energy storage systems.
All the other competitors have much lower levels of commercial maturity. But on the plus side, this means there’s an opportunity to build out domestic supply chains for them. Sodium-ion batteries, for example, replace lithium with sodium, which is far more abundant. They’re also more thermally stable. Unfortunately for U.S. manufacturers, China is already surging ahead in the race to scale up this tech. Then there’s the more nascent lithium-sulfur batteries. They have a very high theoretical energy density, which could lead to lighter and more compact energy storage systems if companies can overcome core technical challenges such as short cycle life.
Flow batteries are also an option that’s been studied for decades. These store energy in liquid electrolytes held in external tanks rather than in solid electrodes. This presents a promising option for longer-duration energy storage since the design can be scaled easily — more energy simply means bigger tanks. Because the active materials are liquid, these batteries also have a very long cycle life, and their water-based designs are non-flammable. Flow batteries are also much bulkier, however, and haven’t yet scaled enough to become cost-competitive with lithium-ion under most circumstances.
Getting into the realm of long-duration storage also opens up possibilities such as iron-air batteries, which are being commercialized by the Massachusetts-based Form Energy. In theory, these can discharge for 100-plus hours by taking in oxygen from the air and reacting it with iron to form rust, releasing electrons in the process. When the battery is charging, an electrical current converts the rust back into iron. Because iron is cheap and plentiful, this tech could also be significantly less expensive than LFP batteries. And since it uses a water-based electrolyte, these batteries aren’t flammable. The first iron-air battery plant is set to come online at the end of the year.
Beyond the electrochemical domain, there’s a wider, weirder world of energy storage technologies, many of which are being explored for their long-duration storage potential. Pumped hydro can only be built only in very specific geographies, so it’s not a main competitor in many regions today. But gravity-based storage companies such as Energy Vault often take inspiration from this approach, storing energy by using excess electricity to raise heavy objects such as concrete blocks. When energy is needed, the blocks are lowered, causing the motors that lifted them to run in reverse and act as generators to produce electricity.
Canadian company Hydrostor is pursuing another method, which involves using surplus energy to compress air and pump it into a water-filled cavern, displacing the water to the surface. To discharge, water is released back into the cavern, pushing the air to the surface, where it mixes with stored heat to turn an electricity-generating turbine.
Then there’s thermal energy storage — essentially storing energy as heat in materials such as carbon blocks. This method has the potential to decarbonize industrial processes such as steel and cement production, which demand high temperatures that are difficult to achieve with electricity. Via resistance heating — the same technology as a toaster — electricity from renewable energy is converted into heat, which is then stored in thermally conductive rocks or bricks. When that heat is needed, it can be delivered directly as hot air or steam to the facility, or in some cases converted back into electricity for use at the facility or on the grid.
Experts say that none of the aforementioned technologies is likely to fully replace lithium-ion anytime soon. That’s in large part because lithium-ion is a fully mature technology with well-established supply chains, but also because it’s simply efficient and cost effective for what it can do.
Many of the technologies mentioned could, however, become effective complements to lithium-ion on the grid. For example, it’s possible that some combination of iron-air batteries, gravity energy storage, and compressed air energy storage could meet longer-duration needs — in some cases discharging continuously for days at a time. Thermal energy storage could also play a role here, as well as in decarbonizing high-heat heavy industries, which don’t make economic sense to electrify with lithium-ion batteries.
Sodium-ion batteries could eventually become cheaper than LFP, but because the tech has yet to scale and reach that price point, it’s still primarily viewed as a complementary solution. Having other viable battery chemistries such as sodium-ion would help reduce the overall demand for lithium, thus working to stabilize prices and risk in the battery supply chain as a whole. But because sodium-ion is less energy dense, it probably won’t make sense in space-constrained regions.
As for lithium-sulfur, the tech is just beginning to hit the market as companies such as Lyten focus on early applications in drones, satellites, and two- and three-wheelers. But it doesn’t yet have the cycle life to make sense for any grid-scale applications, and whether it will ever get there has yet to be discovered.
Yes, but battery recycling — especially for battery energy storage systems — is still a nascent industry. And it remains uncertain whether recycling and reusing battery materials is financially viable in an environment where lithium prices have plummeted and other key battery minerals such as nickel, cobalt, and graphite have become significantly cheaper. LFP’s cost efficiency improvements have further depressed interest in recycling their materials. But there’s still interest in this sector as it could help establish a domestic mineral supply chain, greatly reduce the need for environmentally disruptive mining projects, and ameliorate problems such as toxic chemical leaching and fire risk, which can occur when batteries are improperly disposed of.
Because grid-scale battery deployments didn’t begin to ramp in earnest until 2019, most systems have yet to reach the end of their useful life, which can last on the order of 10 to 20 years. As such, most leading battery recyclers — such as the well-funded startup Redwood Materials — are primarily focused on old EV batteries for now. Redwood says it can recover, on average, over 95% of battery materials such as lithium, nickel, cobalt, copper, aluminum, and graphite. Recently, the company has also been working to repurpose old EV batteries with some life left in them to make grid-scale battery storage systems, and it’s made forays into recycling grid batteries as well.
One of the industry’s former leaders, Li-Cycle, filed for bankruptcy in May, while another player, Ascend Elements, has paused construction on its recycling facility in Kentucky due to “changing market conditions.” As the U.S. seeks to develop a more localized battery supply chain, however, recycling will only become more critical.
It’s a mixed bag. On the one hand, President Trump’s steep tariffs on Chinese goods are set to substantially increase prices for domestic battery energy storage systems, given that the U.S. imports nearly all of its battery cells from China. This will threaten developers’ margins, potentially leading to project cancellations or delays.
Trump’s One Big Beautiful Bill maintained tax credits for battery energy storage projects through 2032, however stringent foreign sourcing rules now apply, withholding tax credits from projects that source a certain percentage of their components from Russia, Iran, North Korea, and most importantly, China. Given how China-centric the battery supply chain is, achieving the required sourcing levels could prove difficult, though exactly how difficult ultimately depends on forthcoming guidance from the Treasury department.
On the bright side, the administration is also bullish on bolstering the U.S. supply chain for critical minerals and rare earths. In a recent meeting, White House officials told a group of critical minerals firms that they would guarantee a price floor for their products. Such a policy could, of course, bolster the domestic battery supply chain, though at the risk of making this tech more expensive.
Assuming the U.S. navigates the current political headwinds and maintains a degree of momentum in its transition to clean energy, battery energy storage will play an increasingly critical role on the future grid, both domestically and globally. As electricity demand grows and renewables make up a progressively larger proportion of the mix, batteries will help ensure grid flexibility and resiliency. That will be increasingly important as extreme weather events become more common and severe.
In some markets, solar plus storage facilities have been more economical than so-called fossil fuel “peaker plants” for years. Peakers fire up during times of maximum electricity demand, and as batteries continue to fall in price, stored renewable power becomes an ever-cheaper way to supplement supply. As long-duration storage tech advances and comes down the cost curve, renewables will be able to provide firm baseload power over a period of days or even weeks, making fossil fuel infrastructure increasingly obsolete.
The International Energy Agency reports that in order to reach net zero emissions by 2050, global grid-scale battery storage needs to expand to nearly 970 gigawatts of capacity by 2030. That means annual grid-scale deployments must average about 120 gigawatts per year from 2023 to 2030. So while last year saw a record-setting 55 gigawatts of newly installed grid-scale capacity, that type of hockey-stick growth will need to accelerate even further if batteries are to pull their weight in the IEA’s net zero scenario.
Log in
To continue reading, log in to your account.
Create a Free Account
To unlock more free articles, please create a free account.
Heatmap News is looking for an ambitious, energetic senior editor to join our growing newsroom.
The senior editor will report to the deputy editor of the website and will be tasked with assisting in running all aspects of our coverage. This individual will be the primary editor on many of the site’s stories, including breaking news, features, and long-term projects, on topics ranging from permitting reform to decarbonized fuels to greenhouse gas accounting to the electric vehicle market. This person will also play a role in overseeing and furthering our cross-platform efforts such as newsletters, events, and podcasts. Additional duties will include managing and maintaining the site’s social media presence and digital production on stories, newsletters, and podcasts.
Candidates should be intellectually curious news junkies with a deep interest in climate change and the energy transition. They should have a proven ability to work in a fast-paced digital newsroom, spot great angles, line edit stories, and change hats quickly as needed. They should also be responsible, reliable, and a good colleague.
Candidates should have 5+ years experience editing for a digital publication. A background in climate or energy coverage is an obvious plus, but compelling candidates from other verticals, particularly politics and business, will also be considered. Heatmap is a fully remote workplace, so candidates from all U.S. locales are encouraged to apply.
Above all, candidates should be passionate about Heatmap’s mission and absolutely thrilled about building something from the ground up.
The salary minimum is $100,000 and the maximum is $120,000. Competitive benefits, unlimited paid time off, and a generous equity plan, which gives employees a real stake in the company, are also offered. This position is remote.
Interested candidates should send a brief cover letter and resume to editors@heatmap.news with the subject line ‘Senior Editor Application.’
Heatmap News is a new media platform with a team of alums from The Week, The Atlantic, Vox, Grid, and Grist focused on the biggest story of our time: climate change.
Heatmap News is an Equal Opportunity employer. All qualified applicants will receive consideration for employment without regard to sex, gender identity, sexual orientation, race, color, religion, national origin, disability, protected Veteran status, age, or any other characteristic protected by applicable law.
To sample Heatmap’s work, poke around the site and sign up for our newsletter:
Current conditions: Japan is bracing for two major storms as Typhoon Nolo and the newly formed Typhoon Koguma barrel toward the country • A brief heat wave in Chicago is driving temperatures up past 85 degrees Fahrenheit today • It’s a sunny day in San Salvador Island, where the Genoan explorer Christopher Columbus first set foot in the Americas exactly 534 years ago today, when the indigenous Lucayan people called the smallest inhabited part of the Bahamas “Guanahani.”
In the Gulf of Mexico, Hurricane Isaias plunged thousands along the Alabama and Florida coastlines into darkness and left at least four dead. In the Pacific off Southern California, Tropical Storm Rachel stirred a surf that badly battered Long Beach’s iconic boardwalk. Further south in the eastern Pacific, Hurricane Simon pounded Mexico’s west coast as a Category 4 storm with sustained winds topping 150 miles per hour. Isaias, the only one of the tempête a trois in the Atlantic, forced nearly two-thirds of U.S. oil and gas production in the Gulf offline, as I told you last week.
The storm threatened to put further pressure on the fuel market as refineries went on pause. But in a post on his Truth Social platform Friday, President Donald Trump announced a surprise deal with Russian President Vladimir Putin to lift Moscow’s restrictions on diesel exports and release nearly 2 million tons of the fuel onto the market. “This is a very big and important announcement,” he wrote. On Sunday, the U.S. president posted another update that, “effectively immediate, there is an ENERGY CEASEFIRE” in the war between Russia and Ukraine, insisting “both parties have agreed.” Whether that holds longer than the last so-called energy ceasefire Trump claimed to have brokered between the two sides remains to be seen. Either way, it didn’t stop the Houthis from twice striking the main airport in Riyadh over the weekend, killing at least a dozen and injuring hundreds amid an oil industry summit in the Saudi capital, the Saudi Arabia-based Arab News reported.
Representative Jared Huffman, a progressive climate hawk from California, wants you to know that he sees your breathless defenses of the bipartisan permitting reform bill and considers them a red flag. “It’s going to be very interesting for everyone to take stock after this election and think about what it means,” he told my colleague Jael Holzman in an interview we published this morning. “I was immediately attacked by right-wing Twitter and some of the boosters of this deal for simply saying, let’s see how this election goes. To me, that’s common sense! And no one is going to vote on this until after the election, anyway! The hypersensitivity tells you something.”
When Jael asked what, exactly, it tells him, he responded: “There’s this choreographed attempt to preemptively flood the zone and prevent any kind of serious scrutiny about this. I think it should be a red flag for my colleagues and serious policymakers to have an attempt to shut down serious scrutiny and debate, or pretend there’ll never be another deal and this one can never be improved, and that it’s now or never or nothing. That’s just fishy and not intellectually honest.”
After construction, automakers buy the most steel of any industry. That makes car companies key factors in how eagerly steelmakers decarbonize. In January, research by the climate advocacy group Mighty Earth concluded that roughly 60% of primary steel made in the U.S. went to automakers who had promised to support greener steel but remained top customers for the metal made from coal-fired blast furnaces. Now the group is out with a new analysis on the European Union, shared exclusively with me for this newsletter, that traced purchases of coal from blast furnaces in France, Spain, Germany, and Italy to vehicles made by Ford, General Motors, Honda, Stellantis, Tata Motors, Toyota, and Volkswagen.
“We always talk about how Europe is leading the charge on green steel, which is true,” Matthew Groch, the senior director of decarbonization at Mighty Earth, told me. “But when you are looking at where these auto companies are being ranked, Europe is still falling behind.” The report proved more challenging than the U.S.-based research given that, in the EU, “it’s a little tougher because, with the common market, they don’t track the actual shipments like we were able to do with anything coming into the U.S.” Still, he said, the team was able to track the commercial relationships through things such as awards given out for “supplier of the year.” What the report ultimately suggests is that advocates of greener steel should seek to pressure shareholders in major automakers on both sides of the Atlantic to clean up their supply chains to spur more demand for lower-carbon materials.
Sign up to receive Heatmap AM in your inbox every morning:

Long one of the world’s top producers of uranium, Kazakhstan faced a choice with major geopolitical implications earlier this year when the Central Asian giant selected bids to build its first nuclear power station. Astana split the difference between its two powerful neighbors, inking a deal for a Chinese nuclear plant in February and another for a Russian atomic power station in March. The shareholders of the state-owned Kazatomprom, Kazakhstan’s state nuclear and uranium company, are proving less diplomatic. The firm’s stockholders voted by nearly 89% to approve a deal to supply uranium to China’s State Nuclear Uranium Resource Development Company, according to an official tally on Kazatomprom’s website. At the same general meeting, which NucNet called “extraordinary,” a deal to supply Russia’s Uranium One died with roughly 88% abstaining.
Kazakhstan has drawn unprecedented distance between itself and Moscow since the start of the Ukraine war, which Astana refused to back even though the Kremlin had helped quell domestic unrest in its Central Asian neighbor just weeks before the 2022 invasion. Beyond increased investment from China, Kazakhstan has attracted more interest from the United States, as critical mineral prospectors such as Cove Capital look to expand across the region.
China ramped up investments in hydrogen and its derivative products, such as green methanol and ammonia, late last year when the central government opened its budget for the first time to directly subsidizing an industry hitherto left to the provinces. The timing proved prescient as the Iran War put the squeeze on China’s crude imports and further accelerated the shift toward more domestic electricity-based resources. Two stories over the weekend show just how swiftly progress is underway. On Friday, Hydrogen Insight reported that the world’s first green ammonia-powered dry bulk vessel had set sail on its maiden voyage from a shipyard in China to Australia. Then, on Sunday, China Hydrogen Bulletin, a newsletter written by analyst Jian Wu, highlighted that China’s first long-distance pipeline dedicated to green hydrogen was approaching its first trial run.

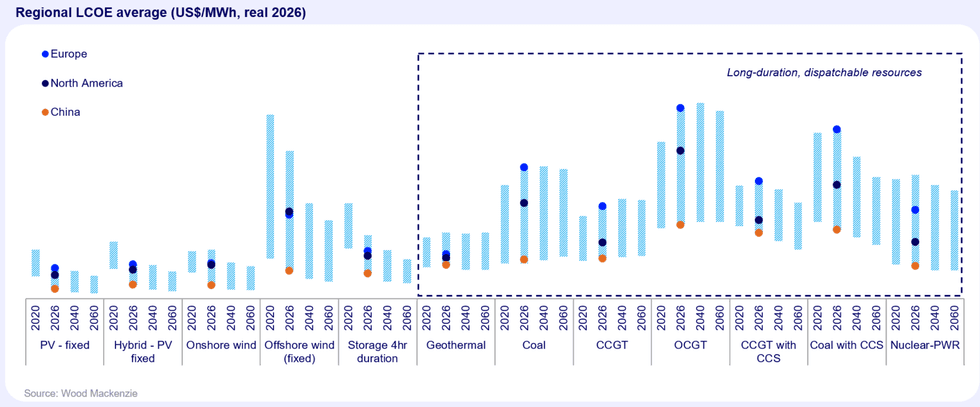
In markets with a lot of wind and solar, there tends to be a lot of gas to serve as backup and keep the lights on when the weather can’t. But batteries are rapidly getting cheaper. Four-hour battery storage is now less expensive than open-cycle gas turbines in all 43 markets where both technologies were modeled, according to a new Wood Mackenzie analysis published last week. “This economic shift is decisive and widening,” Ahmed Jameel Abdullah, principal analyst at Wood Mackenzie, said in a statement. “Gas turbine shortages and rising fuel volatility are driving up peaking costs, while expanding battery manufacturing continues to push storage costs down.” A word of caution: The report is comparing levelized cost of energy, a metric that — while popular — has some real problems, as my colleague Matthew Zeitlin wrote last year.
The California Democrat and current ranking member of the House Natural Resources Committee is suspicious of all the “now or never.”
The most important voice in Congress criticizing the Senate’s bipartisan energy permitting deal is Representative Jared Huffman.
A California Democrat who previously worked in environmental legal advocacy, Huffman has long been among the most impassioned lawmakers on climate issues. Under the first Trump administration, his voice was often the loudest calling for oversight and accountability on energy and climate policy. Under the second Trump administration, he has been a spirited defender of offshore wind.
Should Democrats take control of the U.S. House of Representatives in the coming midterm elections, as expected, then Huffman is first in line to become chair of the lower chamber’s Natural Resources Committee. This makes him one of the few people able to armchair quarterback permitting talks in Congress right now.
The proposed legislation currently on the table, known as the Bipartisan American Affordability and Jobs Act, or BAAJA, would fundamentally reshape how federal project permitting happens. It would constrain National Environmental Policy Act reviews. It would radically alter transmission approvals. It would let companies sue the government for damages if they can show that an agency was unduly discriminating against them based on fuel type. It would limit state and tribal authority to object against projects under the Clean Water Act. And it would make this whole process more transparent by instituting digital reporting requirements.
Huffman thinks it also gives too much benefit to oil and gas interests, and is an unnecessary capitulation to fossil-friendly Republicans who will likely lose power in this November’s midterm elections, anyway. He wants Democratic lawmakers to wait until after election day to consider what they do with the bill.
I reported on Congress for years and often spoke with Huffman in the Capitol hallways; he knew me on a first-name basis. So last week, when a friend pointed me to a tweet of his criticizing the Senate bill by quoting my writing, I took note. His issue concerned the discrimination provision in the bill, which sets a rolling five-year average for approvals as a baseline for what constitutes normal regulatory behavior. Successful lawsuits under this provision would be paid out of the Judgment Fund, a Justice Department account Trump has used for his offshore wind developer buyouts.
This part of the bill, Huffman wrote, “might pay some clean energy developers money from the judgment fund when they are screwed, but nothing to actually approve their projects. This is potentially a replay of the fake settlements that have bought out offshore wind projects,” he added.
I reached out to Huffman’s team and asked to talk about what he meant by that. What followed was a 20-plus-minute back-and-forth about the future of permitting reform in the U.S. and what may happen after a midterm election defined by public anger over a rush to build another type of large-scale infrastructure: data centers.
The following transcript has been lightly edited for clarity.
So let’s start with your tweet. You quoted a portion of our story about BAAJA that I had written about the “permitting certainty” provisions in the bill, and specifically the fact that developers could be awarded damages under the bill for discriminatory treatment. Could you elaborate on your point?
I don’t want to get too deep into the weeds, but this is the big thing being offered as an end to the war on clean energy, which was always the threshold matter before you get to a bipartisan permitting deal.
It is built on this framework, basically, of cutting checks from the judgment fund. And I believe that requires some close scrutiny and consideration because we have seen this gamed already to the tune of $4 billion to buy out offshore wind developers.
Well I know this can get quite technical, but the underlying point you were making was, this may not be as helpful as people think. I guess I was just wondering if you can you walk me through —
It depends what you want.
If you’re a clean energy developer and you’re worried about your shareholders and your balance sheet, this gives you at least some money when you get screwed. And it may come with some strings attached, like you have to turn around and invest it in [liquified natural gas]. That’s been the playbook from the Trump administration.
If you’re a clean energy CEO — some of them, at least — that helps you mitigate risk. That’s probably better than nothing and will be attractive to some people. But if you care about climate policy [and] whether this is a meaningful assurance of permitting certainty to renewables, I think there’s a lot more to question here.
You also said in your tweet that there’s nothing in the bill to get projects approved. Can you speak to that? Because those who negotiated it clearly say otherwise.
Well, there are shot clocks and all sorts of other things that are designed to speed things up. There’s also broad categories of exemptions — categorical exemptions and other things like that, most of which will benefit fossil fuel projects.
I have no doubt there’s going to be permitting acceleration and certainty for fossil fuel projects. You also have this five-year baseline mechanism being codified here that will further cement a high level of fossil fuel projects for many years to come, and will really operate as a ceiling.
Help me understand what you mean by that, because I’m interested in understanding your concern there.
People are going to want to look at this much more closely and think about how it’ll operate in practice, not just some model. Because in practice, Trump is going to keep doing exactly what he’s done for the last two years. He’s going to find ways not to permit renewables, even if some of them go through this new gauntlet of legal theories and challenges and at the end of the day get a check written to them from the judgment fund.
You make this point about models versus reality. I spent last week trying to understand the implications of the bill for the nation’s buildout of AI data centers and associated energy infrastructure. How do you see that data center conversation weighing on your evaluation of the bill?
It’s part of the context, for sure. It’s driving a lot of this — we have to be honest about that. This is about data centers and pipelines and grid improvements necessary to meet all this surging demand that’s mostly coming from data centers.
That’s not to say we don’t need a more functional and robust grid. We do. Whatever you think about AI and data centers, we do need that. I’m not going to hold up a chance to improve our grid just because I have big concerns about data centers. I am concerned about how all this huge demand for energy in the next few years is going to be met. If we are stacking the deck for fossil fuel to meet a lot of this demand, that is deeply non-responsive to the climate crisis.
In terms of “stacking the deck,” passing the bill or not passing the bill — which reality is a cleaner grid and cleaner buildout of these data centers?
I mean, I would love to give you an absolute answer to that, but it depends. It depends how you assume this is going to play out in practice.
Looking at the conversations around the bill and considerations about federal permitting, as well as the politics, I’m struck by this timeline we’ve found ourselves in. Over the next month, voters will be hearing about data centers, which is something they don’t want in their communities, per polling. They also will be hearing about energy prices, which people want to bring down. Faced with those two different signals, I’m wondering how any kind of lame duck conversation about permitting happens after those two signals land in the ballot box.
It’s going to be very interesting for everyone to take stock after this election and think about what it means.
I was immediately attacked by right-wing Twitter and some of the boosters of this deal for simply saying, let’s see how this election goes. To me, that’s common sense! And no one is going to vote on this until after the election, anyway! The hypersensitivity tells you something.
What does it tell you?
There’s this choreographed attempt to preemptively flood the zone and prevent any kind of serious scrutiny about this.
I think it should be a red flag for my colleagues and serious policymakers to have an attempt to shut down serious scrutiny and debate, or pretend there’ll never be another deal and this one can never be improved, and that it’s now or never or nothing. That’s just fishy and not intellectually honest.
I’m not on the Hill as much anymore, which means I don’t see you as often. But in my many years covering Congress, I can’t tell you how many times I’d ask your late colleague from Arizona, former House Natural Resources Chairman Raul Grijalva, about his conversations with former Senate Energy and Natural Resources Chairman Joe Manchin.
I’m not going to sit here and expect you to read the minds of senators any more than I would expect senators to read the minds of House members. But can you, someone known as a climate champion, speak to how things are going with Senators Sheldon Whitehouse and Martin Heinrich, two people also respected in the climate community, when it comes to your reservations about this legislation?
I mean, it pains me to have a different view of some of this than these two friends of mine I respect enormously. But this may be one of those deals where reasonable minds can differ about tactics, details. That’s what this is coming down to.
I am sure negotiating with the hand they had over the past few months that they did pretty good work. Period. But I am sure with a better hand they and the rest of us could probably get a better deal.
A better deal the president will sign?
Yeah, that’s how it works. Let’s just take the logic of that argument you’re posing, which I hope is a devil’s advocate. Let’s say the president said he’ll agree to this and therefore we have to take the deal. By that reasoning, you should just always do what Trump demands. Always. And I find that absurd.
Any time I hear that kind of reductive reasoning … Has no one been watching Trump his entire life? He’s a bluffer. He’s a threatener. And he changes his mind all of the time.
Yeah I mean, to that effect, we asked Energy Secretary Chris Wright on stage at Climate Week if Trump would publicly post that he will sign off on approving more wind projects, and Wright said we shouldn’t count on that.
I’m very suspicious of the whole thing. There’s so much posturing and choreography going down right now.
They’re going to make it look like they won’t release any hostages, and then they will. It’ll be a very partial release of hostages. It’ll be maybe a dozen or so onshore wind projects that already have all their other approvals and [are] just waiting for the Department of Defense national security hold that is specious to be lifted, even though it’s never going to be held up in court. That’ll be shown as this big breakthrough that lets all this move through at lightspeed.
That’s the charade we’re being walked through right now.
To your point, I checked the court filings this morning, and the Justice Department did just tell the federal court hearing the challenge to the Defense Department that they’re now processing about that number of projects.
But if I can ask you, to that point, I’ve known you almost as long as I’ve been a reporter — almost a decade. I also knew your colleague, the late Raul Grijalva, quite well. I don’t remember a single time when Grijalva was chair of the Natural Resources Committee that he ever supported a bipartisan permitting deal. I remember his opposition to the Barrasso-Manchin bill quite vividly, and a lot of other times that was the case —
Well that might be a difference. I was ready to negotiate improvements in Barrasso-Manchin and try to get to something I could support, in part because I was worried what a Republican Congress and a Trump administration would do if we didn’t try in good faith to get to a deal at that time.
I think we missed an opportunity there. But that was largely because the opportunity was shut down by Republicans. I can’t say what Grijalva would’ve done, but I can say what I would’ve done. I would’ve rolled up my sleeves and tried to get a deal.
Well, I just pulled up a quote from you about that bill, in which you said, “We need to find a way to kill the zombie one more time.”
There was also an opportunity to fix the problematic parts of it.
I guess what I’m asking is, what would you say to people who claim there’s no bipartisan deal in the offing like this bill that you would support? Because any deal like that would obviously have to provide some things to industries like fossil fuels that you don’t want to sign off on.
That’s the problem. If the “deal” has to always get worse, then yeah, that’s a zombie deal we’ve seen time and again, where it’s just the wishlist of the fossil fuel industry or nothing. That is the downward race to the bottom we’ve been on when we talk about permitting reform. But if you want grid improvements, if you want some of the other good provisions in this package — look at the fact I cosponsor Sean Casten and Mike Levin’s bill, [the Energy Bills Relief Act,] to do a lot of these things.
Would you rather that bill is the starting point in the new Congress?
Of course I would. That’s a good transmission bill that doesn’t come with all the other baggage. I’m pointing that out to say I’m not just against things but I’m for things, and you can see that from a longstanding record.
My last question — and I want to ask it because people are raising it — if this bill doesn’t get passed, there are going to be at least some people who point fingers after it fails at the people who stopped it. Those people will say those who stopped it don’t want anything. I know you’re pointing at Levin-Casten and —
No, I know your question, Jael, and I have to run here in just a minute.
If we get to that point and you hear all this whining and recrimination, you know what I will say to those people? Shut up and get in the room and let’s work on a deal. [laughs] I mean honestly it’s just so absurd. If you want permitting reform, you’ve got to be willing to work in a more thoughtful way instead of all these absolutes. This or nothing. Now or never.
I mean, you’ll see. What I can tell you is that you’ll see if we get to that scenario.