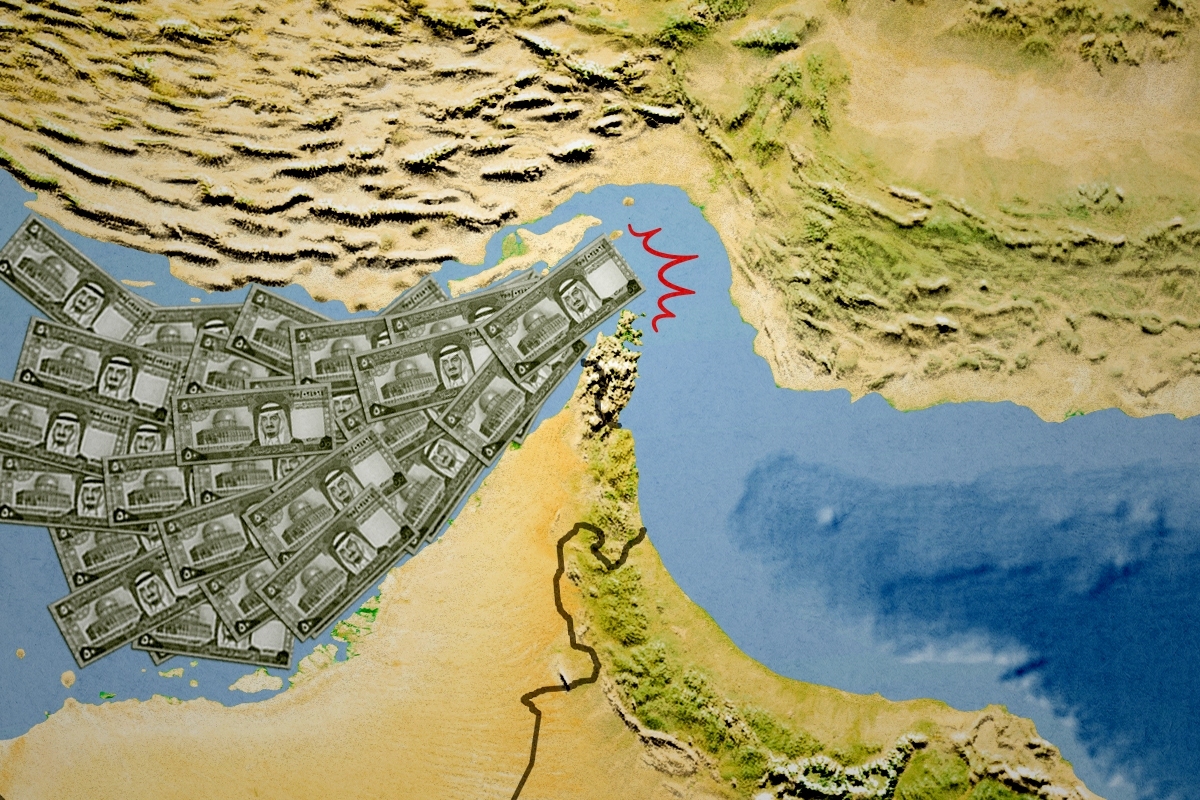
The closure of the Strait of Hormuz has already propagated across the global energy and climate ecosystem in countless ways. To name just a few, there’s skyrocketing gasoline prices, a coal comeback, tailwinds for U.S. liquified natural gas, and aluminum price spikes that raise costs for solar panels.
But if you continue to follow the money, you could start to see repercussions for emergent climate technologies, too — think electric mobility, clean hydrogen, alternative fuels, carbon removal, and carbon capture.
Billions of dollars from Gulf states — including the United Arab Emirates, Saudi Arabia, Kuwait, and Qatar — flow into climate tech every year via sovereign wealth funds and the investment arms of regional oil and gas giants such as Saudi Aramco and the Abu Dhabi National Oil Company. With attacks on energy infrastructure causing extensive damage and millions of barrels of oil — the region’s largest export — and other petrochemical products now stranded in the Gulf due to the strait’s effective closure, fossil fuel revenues are falling across much of the region, even as commodity prices spike. The longer this status quo remains, the greater the threat could be to these countries’ ability to disburse climate tech capital.
This could have significant repercussions for decarbonization startups, Johanna Wolfson, co-founder of the early-stage climate tech investment firm Azolla Ventures, told me. Outside of the U.S. government’s current favored technologies — data centers, nuclear, geothermal, and critical minerals — “there’s increasingly scarce early-stage risk-embracing venture dollars,” she said. That’s a gap that strategic investors such as oil and gas-backed investment vehicles typically help fill, as many of them “have patient long term capital, or at least a different way of evaluating business outcomes or ROI than a typical venture investor would.”
Now, Wolfson said, she wouldn’t be surprised to see regional investors pulling back on some of these more forward-looking initiatives.
The ecosystem linking climate capital with Gulf money has grown increasingly tangled over the years, especially since COP28 in Dubai. There, the United Arab Emirates launched Altérra, a climate focused investment fund that’s since deployed $6.5 billion to anchor multi-billion dollar climate funds from Brookfield Asset Management, Blackrock and TPG Rise Climate. The specific companies and projects these institutional giants have gone on to back, however, remain largely undisclosed. Meanwhile, Saudi Arabian pension fund Hassana has also invested $1.5 billion in TPG Rise Climate.
Following the money is unsurprisingly easier for venture investing. Aramco Ventures, the oil giant’s VC arm, led the seed round for direct air capture company Spiritus, while also backing big names such as long-duration battery startup Form Energy, green steel developer Boston Metal, and thermal energy storage company Rondo Energy.
As for the region’s primary investment vehicle — sovereign wealth funds that manage surplus capital largely derived from oil and gas revenues — their capital flows are also often obfuscated. When they invest as limited partners their names are typically kept private, and they frequently funnel money through subsidiaries operating under different monikers.
Some big name deals have broken through, though. The Saudis, for example, have been enthusiastic backers of electric vehicles. The Public Investment Fund took a roughly $2 billion stake in Tesla back in 2018, and owns a majority share in luxury EV-maker Lucid Motors, which plans to start manufacturing vehicles in the kingdom by year’s end. Abu Dhabi Investment Authority funded utility-scale solar company Arevon, another Abu Dhabi-based fund, Mubadala, backs the offshore wind company Skyborn Renewables, and the Qatar Investment Authority co-led the Series D round for EV battery producer Ascend Elements.
“There’s a good reason that Saudi and other sovereign wealth funds are investing in these technologies and these startups,” Daan Walter, principal at the clean energy think tank Ember, told me. “It’s a really good hedge for their own oil business, and many U.S. banks are highly exposed to fossil fuels.”
That doesn’t mean these investments will remain attractive if Gulf states’ oil revenues continue to suffer, however. “Those looking to raise capital in the region should probably allow for some slow responses for a while,” Paul O’Brien, the former deputy chief investment officer at the sovereign wealth fund Abu Dhabi Investment Authority, told ImpactAlpha. That said, he figures that “deal flow should resume soon after the Strait of Hormuz opens.”
Restarting regional clean energy projects may prove more challenging. Wolfson told me the war is already affecting some companies in Azolla’s portfolio that are evaluating pilot opportunities in the Gulf, a region marked by both unique climate risks and a willingness to embrace early-stage tech. “We definitely are seeing a pause on those activities, understandably” she told me. “When this is going on in one’s backyard, you need to pause things that are not critical.”
What’s certain, Francis O’Sullivan, a managing director at the firm S2G Investments, told me, is that even once the strait opens back up, “this is not a switch it back on and everything is fine kind of dynamic.” Since the conflict broke out, many Gulf producers have been forced to cut oil production as their storage tanks fill up. Once hostilities subside, oil wells and refineries could still take weeks to ramp up to prior levels. Then it might be a matter of months before the backlog of fuel, food, and other materials clears the strait and shipping supply chains return to normal. The energy infrastructure that’s been damaged — such as the Ras Laffan LNG terminal in Qatar — could take years and billions of dollars to rebuild.
Restoring business as usual could draw the Gulf’s sovereign wealth funds away from their core climate-related priorities like green hydrogen, clean fuels, and carbon capture. Saudi Arabia’s Public Investment Fund, for example, could abandon its stated target of investing over $10 billion in green projects by year’s end. The kingdom has ambitious aims to generate 50% of its electricity from renewables by 2030, and has previously declared its intention to become the planet’s largest hydrogen supplier by 2030 as well as to develop one of the world’s largest carbon capture, utilization, and storage facilities by 2035. These hydrogen and CCUS goals were absent from the country’s latest national development plan released in April of last year, however, indicating that enthusiasm was perhaps already waning.
Walter isn’t surprised. In his view, the climate tech priorities of oil-rich Gulf states tend to favor industries that preserve the existing energy order, and their commitments may not be deeply held. After all, carbon capture helps clean up fossil fuels, while hydrogen for transport and heavy industry can complement rather than replace oil. “I’ve always seen that more as a way to keep the status quo running and argue, we’ll fix this in the future,” he told me. “I’m sure those projects will be scrapped first.”
Sure enough, blue hydrogen production, which pairs fossil-fuel derived hydrogen with carbon capture and storage, is becoming increasingly uncertain amid low investor demand. Saudi Aramco has scaled back its target from 11 million to 2.5 million annual metric tons while ADNOC has indefinitely postponed one of its blue hydrogen projects. And while Saudi Arabia is also attempting to build the world’s largest green hydrogen project to help supplement its oil exports, this too has been struggling to secure international buyers.
Perhaps it goes without saying that the Iran war will do little to buoy the financial fortunes of overly ambitious mega-projects and industries already grappling with limited demand. But even if the Gulf-to-climate tech funding pipelines remain disrupted and attention shifts to urgent regional priorities like rebuilding damaged infrastructure, the reality remains: Deploying renewables and battery storage is often the most reliable — and cost-effective — way for nations to secure their energy supply and shield themselves from future fossil fuel price shocks.
Since the last major energy price spike following Russia’s invasion of Ukraine, costs for solar panels and battery systems have continued to fall — with panels roughly halving in price and battery systems dropping by about 36%, according to Ember. “This is the first oil shock where there is a superior alternative.” Walter told me. And the first “that doesn’t require countries to intervene.” He expects that when left to their own devices, consumers will make economically rational choices, leading to a significant uptick in adoption of rooftop solar, home batteries, EVs, and heat pumps — particularly in emerging economies outside the U.S. and Europe, where tariffs on Chinese clean tech don’t exist.
When it comes to tech that has yet to be commercialized, such as clean fuels, long-duration energy storage, and carbon capture and removal, Walter is counting on governments to step in where hobbled Gulf investors may no longer be able to. “There’s a wishful thinking component to it, which is that surely governments realize that this is the solution,” he told me. And yet he believes they truly are beginning to see the light, as the importance of energy security becomes more apparent by the day.
“Surely they realize that you cannot now throw the startups in the space by the wayside because they really, really need the support,” he told me. “I hope that governments across the West are prescient enough to realize that someone else needs to step in to bridge the gap for the coming years.”
Editor’s note: This story has been updated to clarify the context of Johanna Wolfson’s remarks.
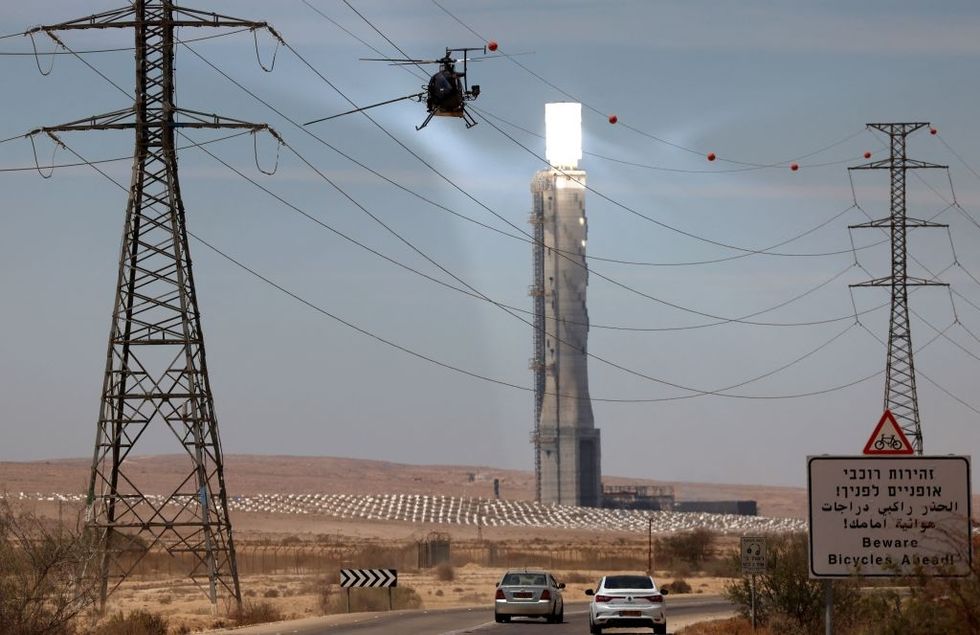 A crew cleans power lines at Israel’s Ashalim solar plant.EMMANUEL DUNAND/AFP via Getty Images