In the waning weeks of the midterm election cycle, the question of who will serve as Oklahoma’s next insurance commissioner is unlikely to be a topic of intense speculation at dinner tables around the country — or in Oklahoma, for that matter.
For one thing, it’s about as down-ballot a race as you can get, another bubble to be filled in alongside state treasurer and superintendent of public instruction. For another, it’s difficult to imagine it will be much of a competition: It’s been two decades since a Democrat last won statewide office in Oklahoma.
But if there ever were a race for an upset, this would be it. Oklahoma is one of the most expensive places in the country to purchase home insurance, with an average annual premium in 2024 of over $5,819 for $350,000 in dwelling coverage — well above the national average of $3,303 and behind only Florida and Louisiana, per the most recent numbers from the Consumer Federation of America. That’s even more staggering given the local cost of living: Oklahomans spend more of their median household income, $65,039, than residents in any other state on home insurance — almost 9%.
When it comes to arguing for greater industry regulation, Democrats are typically on more comfortable footing against their conservative counterparts. Craig MacIntyre, the Democrat in the Oklahoma insurance commissioner race, has promised to use the state’s new “file and wait” law to review rate increase requests closely before they’re implemented. But in a strange reversal of roles, Republican candidate Bob Sullivan won a four-way primary and subsequent runoff that centered on the conservatives arguing over who would be the toughest industry regulator.
The topsy-turvy politics don’t stop there. Republicans in the state have also called out the impacts of extreme weather on premiums, albeit without going quite so far as to blame climate change. Sullivan unabashedly models himself after Trump (“Make insurance fair again!” “Drain the insurance swamp!”) but also set himself apart from the competition by challenging the narrative that severe weather — not climate change, per se — is the primary explanation for the state’s high rates — putting him more in line with the Democrat, who almost hasn’t mentioned weather at all.
It’s a notable break. Extreme weather has long been the go-to explanation for Republicans about the state’s high homeowners’ premiums. “We get our fair share of weather in Oklahoma,” the state’s outgoing, term-limited insurance commissioner Glen Mulready told me. “We’re right next to Texas and Kansas and Arkansas, so they get the same weather we do — that’s the quote we hear all the time,” he added, “which is just simply not true.”
Oklahoma Watch, a nonprofit investigative newsroom that reports extensively on the state’s insurance crisis, has suggested that the insurance industry and its allies in the state might be using hail in particular “as a scapegoat to justify high rates,” given that other states with high instances of hail pay far less in premiums.
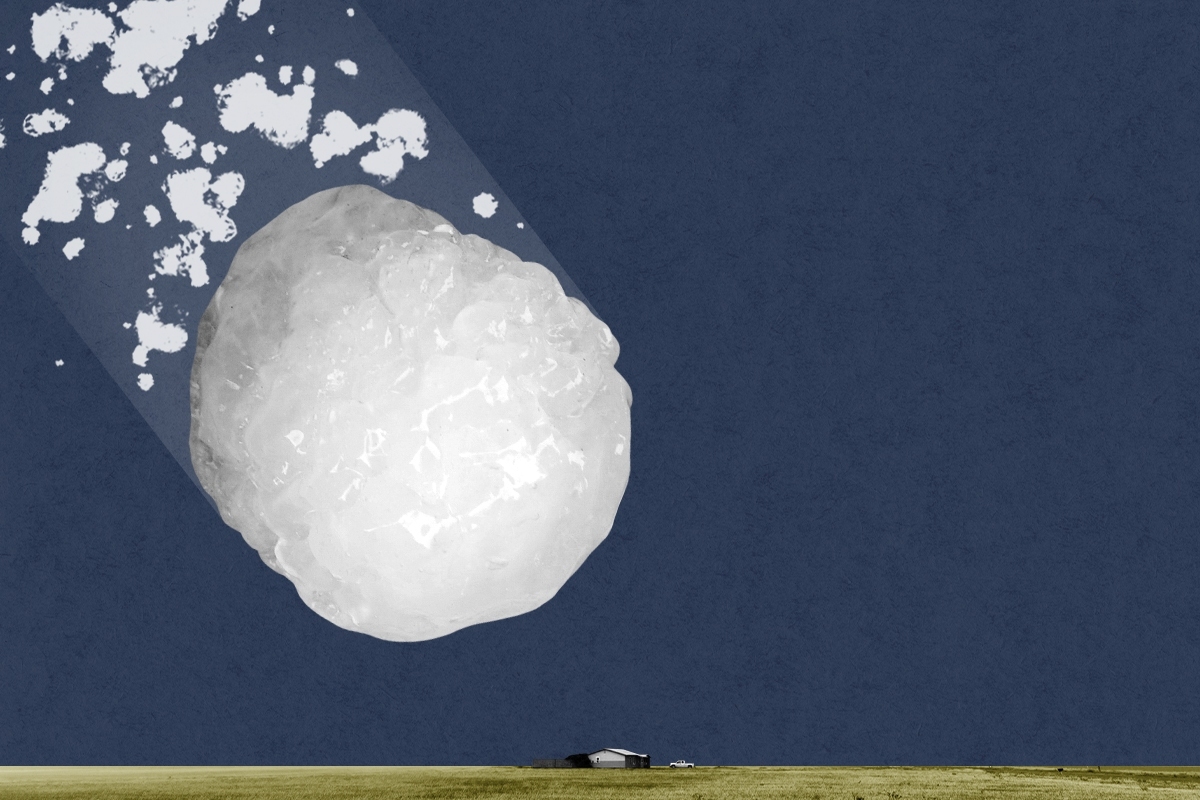
It’s true, though, that Oklahoma seems to be a particularly bad place for hail, which is responsible for an estimated $1 billion in annual property and crop damages in the United States. In most of the state, even at the tiny geographical scale of an individual roof, you have about a one-in-10 chance each year of seeing two-inch or larger hail, Ian Giammanco, a lead research meteorologist at the Insurance Institute for Business & Home Safety, told me. Verisk, a risk assessment firm, also found that over the last four years, nearly 50% of Oklahoma roofs were hit by severe hail — the highest rate nationwide.
"Hail gets overlooked, but it’s a huge contributor to rising insurance costs," Michael DeLong, a researcher at the Consumer Federation of America, told me.
Hail’s climate signal isn’t obvious to researchers yet. “We haven’t seen any observational fingerprints that hail appreciably changes” in a warming world, Giammanco said. But while the number of days with severe hail across the U.S. hasn’t changed much, “there may be an upswing in severity that’s just starting to be able to be observed,” he noted. Warmer air, for example, may raise the potential for “really big hail, while the lower end may actually decline.”
Hail is one piece of Oklahoma’s nasty extreme weather cornucopia. Increasingly frequent wildfires, extreme heat, and severe storms and tornadoes also threaten homes (not to mention seismic activity from injecting fossil fuel wastewater underground). Between 1980 and 2024, the state averaged about 2.6 weather disasters per year that cost more than $1 billion in damages, adjusted for inflation, but in the last five years of that timeframe — 2020 to 2024 — it averaged six, including droughts, tornado outbreaks, and blizzards. (The Trump administration retired the National Centers for Environmental Information’s U.S. Billion-Dollar Weather and Climate Disasters database last year, so there isn’t more recent data.)
But the affordability problems don’t exist in a vacuum, and are compounded by historic infrastructure and materials choices. New home construction, for example, peaked at an average of over 2,800 square feet in 2015, meaning a bigger target for hail. “We have lots of field observations of 300 hailstones in a square foot area,” Giammanco told me; in a given storm, more than 800,000 might pummel a house. And while slate and tile roofs — popular construction before the post-war suburban boom — withstand hail well, they’re also slow and difficult to install. Asphalt shingling, on the other hand, is cheap, easy, and popular — and “highly vulnerable to hail, especially as it ages,” Giammanco added.
Republicans have traditionally argued that relatively little can be done about Oklahoma’s high homeowners’ insurance rates, given the state’s weather and larger nationwide trends in inflation-driven rebuilding costs and reinsurance. Karen Collins of the American Property Casualty Insurance Association, an industry advocacy group, further warned the Oklahoma House of Representatives in a hearing last year that cracking down on the industry could drive insurers out of the state. “We’ve seen … when government regulates directly or indirectly price controls on markets with escalating losses, it does turn those affordability challenges into an availability crisis,” she said.
When I asked the APCIA for comment, Walter Gonzalez, the assistant vice president of state government relations, told me in an email that “the story in Oklahoma today is not accelerating rate increases. It’s decelerating rate increases.” He pointed me to data showing that average rate increases among the state’s largest insurers fell from 16.4% in 2023 to 5.3% by 2025, and they’re at just 2.9% so far in 2026. Still, what homeowners actually pay is a different story: Oklahoma was among six states nationally to see homeowners’ premiums increase by more than 20% in 2025, an Insurify report found.
Gonzalez also pointed out that insurers paid close to or more in losses and expenses than they made in premiums over the past several years. In a blog post last year, Mulready wrote that Oklahoma’s top 20 insurers paid out $129 in claims for every $100 in premium collected in 2023, improving slightly to $97 in claims for every $100 in premiums collected in 2024. Critics of the industry, however, argue that focusing on underwriting losses elides a major source of profit for insurance companies: their investments.
Birny Birnbaum, the executive director of the Center for Economic Justice, a nonprofit that works on insurance advocacy for low-income and minority consumers, agreed that recent years have been challenging, especially after the reinsurance market retrenched and doubled prices following Florida storms in 2021 and 2022. But those rates have since stabilized and even declined, he said, yet “the insurance companies haven’t been reducing their premiums to reflect that.” Birnbaum has also been highly critical of Mulready’s approach — a hands-off, free-market approach to the insurance industry designed to spark competition and drive down prices. The insurance commissioner never denied a home insurance rate increase requested by an insurance company during his eight-year tenure, Mulready confirmed to me. Indeed, state statute barred him from doing so, he said. “There is no excessive rate in a competitive market,” he told me.
Birnbaum is not convinced. “For some reason, in virtually every state, the regulatory model is: If we allow the insurance companies to do whatever they want, that will bring them back into the market,” he said. He likened that argument to someone claiming that if we removed the Affordable Care Act’s preexisting condition protections, we’d ultimately end up with more people insured. If you heard that, “you’d go, ‘That’s the stupidest thing I ever heard in my life,’” he said, minus an expletive.
A loose regulatory environment might also mean that Oklahoma ends up subsidizing insurance in higher-risk, more tightly regulated ones. When national insurers take big losses in states like California that have stricter rules around rates, they may increase costs in states where it’s easier to do so, Ishita Sen, a professor of finance at Harvard Business School, told The New York Times. (Mulready has vehemently denied this on his podcast.)
Whether Oklahoma’s insurance market is truly competitive is even an open question to some. The insurance industry’s stance, like Mulready’s, is that the Oklahoma market is competitive, and “market-share concentration alone is not a measure of whether consumers have meaningful coverage choices.” And yet Allstate and State Farm alone represent a little over 40% of the market in Oklahoma.
Breaking with Mulready and the APCIA, Sullivan, the Republican candidate for commissioner, told E&E News that he plans to declare the state’s insurance market “non-competitive” if elected. (In an odd quirk of state law, there is no benchmark at which a market becomes competitive or not; it is entirely at the insurance commissioner’s discretion to declare it as such, so long as they hold a public hearing first.) MacIntyre, the Democrat dark horse, has described the market the same way.
Mulready told me that doing so would be a “mistake.” “The only data point that anyone ever presented to me only proved a competitive market,” he said, citing both the Herfindahl-Hirschman index and the four-firm concentration ratio, two popular forms of measurement. An investigation by Oklahoma Watch, however, found that the Oklahoma Insurance Department counted companies, not insurance groups, giving it rosier numbers on the HHI and CR4 scales and distorting the picture of a “potential oligopoly.” Birnbaum, the executive director for the Center of Economic Justice, told me that Oklahoma has “a complete seller’s market” and describing it as competitive is “laughable.”
That said, either choice for the office on the ballot in November would be “lightyears ahead of the current commissioner,” Birnbaum added. “The two candidates who are running both have better ideas and better values and better understanding of how insurance markets operate,” he said.
The winner will have his work cut out for him, though. Birnbaum stressed that the state has done little to assist in residential storm-proofing — one of the most important levers for bringing down costs — and the existing grant program for roof replacements is woefully insufficient. “It would take probably 50 years at this current level of funding to reach all these [homes], and none of these programs actually require insurance companies to have any skin in the game,” he told me, pointing to Wisconsin and Louisiana as examples of states that require insurance companies to offer discounts that incentivize loss prevention. (Mulready told me the first-come, first-serve grant program, which draws on unused funds of the Insurance Department, has helped replace around 700 roofs since it began in 2025).
In addition to reviewing rate increase requests and opening investigations into insurance companies’ claims payment processes, DeLong echoed the need for a much larger grant mitigation program. “Admittedly, that’s going to be expensive,” he conceded. “But it will be a lot more expensive if you don’t do anything.”
Mulready, meanwhile, laughed when I asked him for his advice for his successor. “That could be awhile,” he said. But he directed Sullivan or MacIntyre to “make decisions based on the data.” That’s what he did, he said. And the years, he mused, have gone fast.
 French leftist leader Jean-Luc Mélenchon. Photo: Kenzo TRIBOUILLARD / AFP via Getty Images